Connect the whole journey before the first investment
Living in the UAE often means managing two financial lives. Your salary, rent and everyday expenses may be in dirhams, while family support, an existing property, retirement plans or an investment portfolio connect you to India. The useful starting question is what you want the money to do, where you will eventually use it, and which route can carry it there.
A successful account application answers only one part of that question. Your bank account, investment access, residency position, tax records and eventual withdrawal need to fit together. An attractive rupee return can lose much of its value after currency conversion. A familiar Indian account can still need a status update after moving abroad. A UAE residence document can establish identity without settling a tax-treaty claim.
This guide is the starting point for the UAE section of RegalTicker's NRI Investing Academy. It brings the decisions together and directs you to the detailed guide when you need documents, calculations or a product-specific explanation. If you are ready to apply for banking, go straight to the existing NRI account-opening guide from UAE.
⚡ Quick answer
Can an Indian living in the UAE invest in India?
Eligible UAE-based NRIs can invest through permitted Indian banking and product routes after completing the required onboarding. Start with your FEMA status, the source of funds and your need to use the proceeds outside India. Then confirm the bank, broker or fund setup for the actual investment. Assess Indian tax and any India–UAE treaty claim separately. Record the AED conversion costs and the documents needed to move proceeds later. The sections below explain how to connect these checks.
Key takeaways
Your goal currency and access to money matter alongside the investment return.
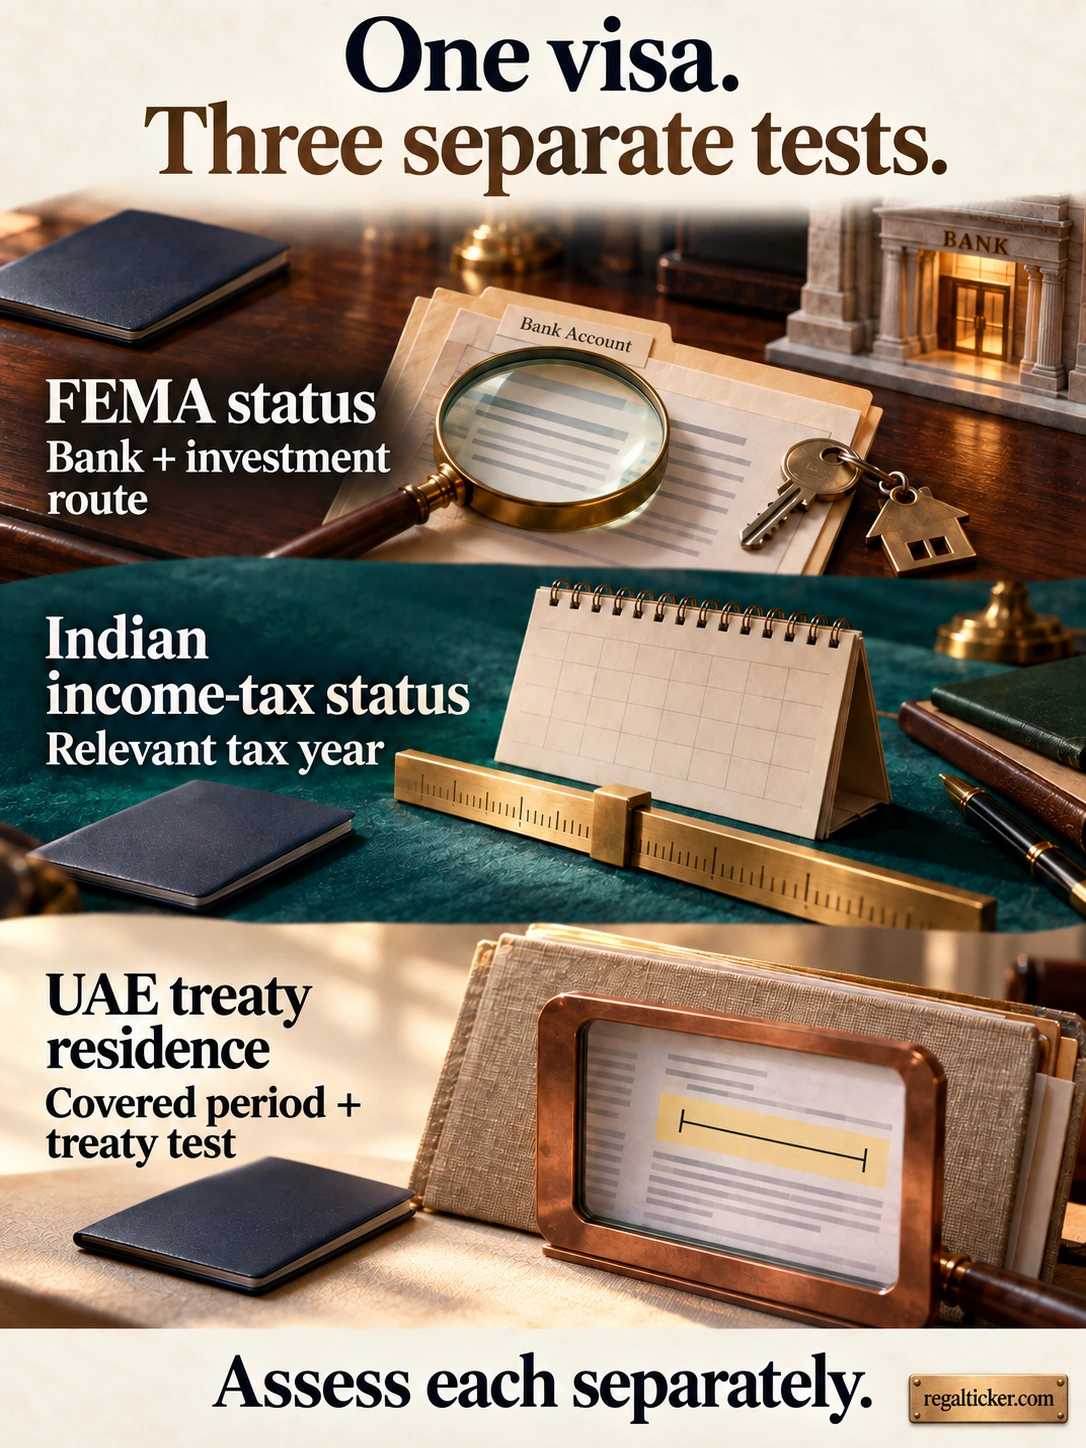
FEMA status, Indian income-tax residence and UAE treaty residence are separate checks.
A bank account and an investment route must be considered together.
UAE personal-investment tax treatment does not remove the need to assess Indian tax.
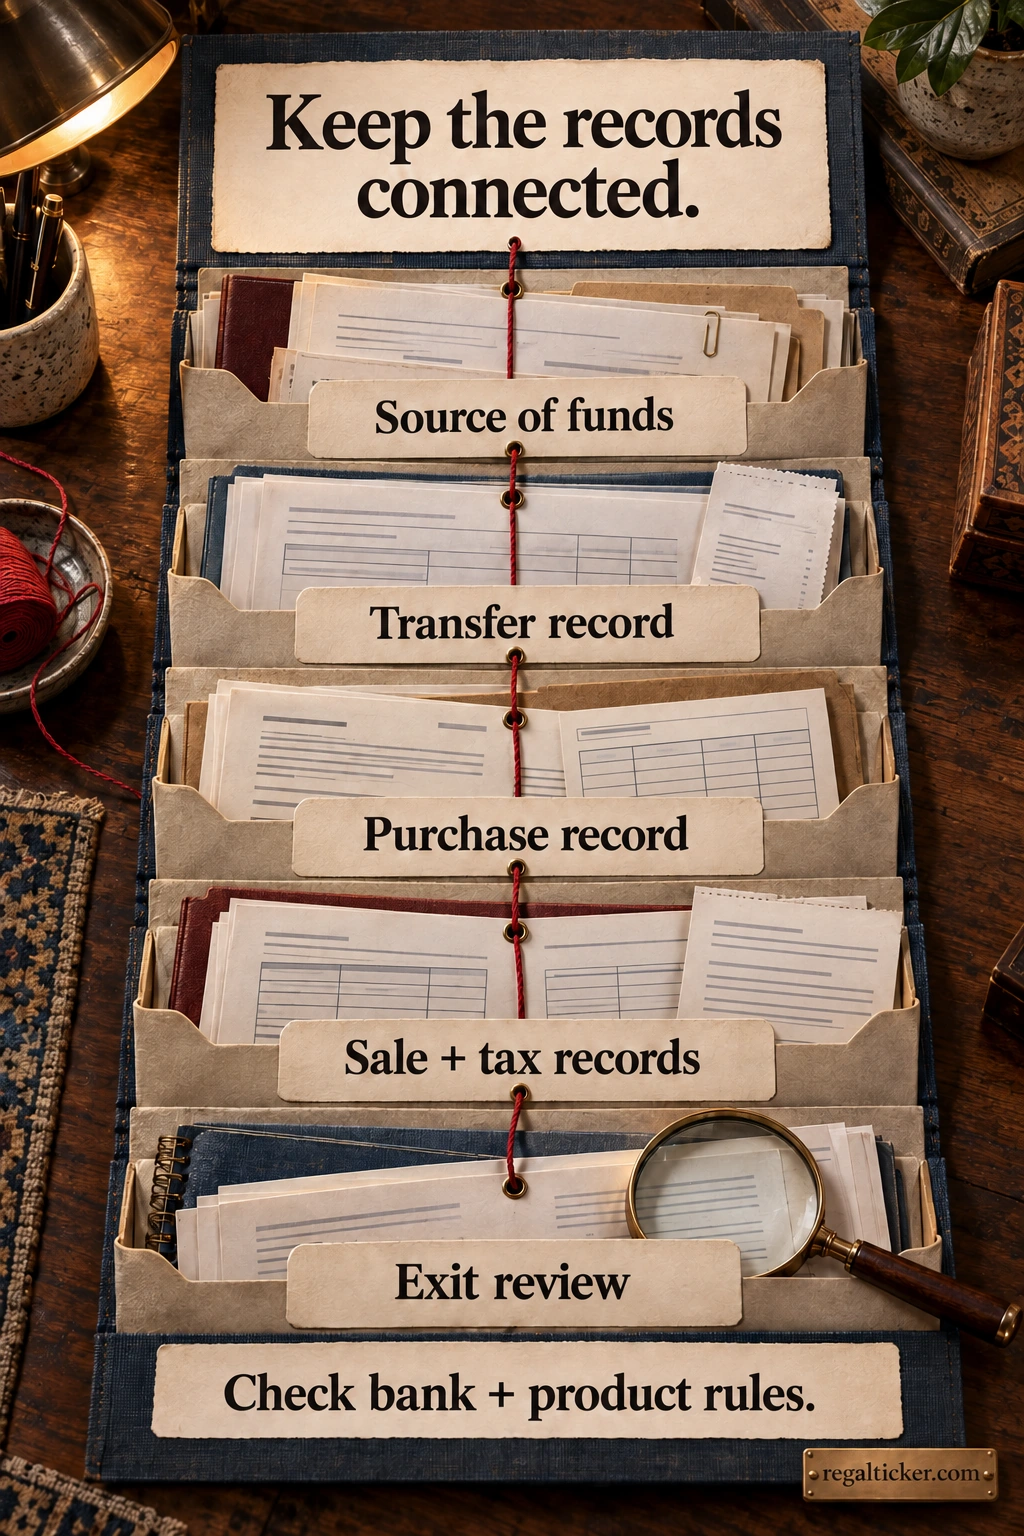
A clear funding trail helps with investing, tax review and later remittance.
Review the setup when you change country, change contact details or return to India.
1. Start with the situation that matches your life
You do not need to read every NRI guide before taking a useful next step. Begin with the point at which your money or records need attention, and follow the links that resolve it. This is especially helpful if you have lived in the UAE for years and already own Indian assets.
On a phone, scroll the tables sideways to read every column.
| Your situation | The decision to resolve first | Where to continue |
|---|---|---|
| You recently moved from India to the UAE | Check the status of existing accounts and investment records | NRI vs resident investing and residency explained |
| You want to invest part of your UAE salary | Decide the source-of-funds and future-use route | NRE vs NRO vs PIS |
| You need your first NRI banking relationship | Choose the bank's current UAE application channel | Account opening from UAE |
| Your banking is ready and you want Indian shares | Match the bank route to NRI broker and Demat onboarding | NRI Demat account setup |
| You want a fund or an ETF rather than individual shares | Check the product, provider acceptance and operating route | NRI mutual funds and NRI ETFs |
| You have Indian income or recently sold an asset | Separate the tax calculation from permission to send money abroad | Capital gains and TDS and repatriation |
| You plan to move back to India | Prepare account, residency and overseas-record updates | Returning to India checklist |
Write down the job of the money
A future expense in India and an expense in the UAE can justify different planning questions even when the same investment is available. An education payment due in dirhams, support for parents in rupees, and a possible retirement in India have different currencies and different dates.
Write a short purpose statement before comparing products: the approximate spending date, the spending currency, whether the amount is essential or flexible, and whether it must remain available outside India. This does not pick a portfolio for you. It makes the trade-offs visible.
For example, money committed to an imminent UAE rent payment has a different role from money intended for an uncertain retirement date. A market fall, withdrawal delay or unexpected conversion cost is much more disruptive when the spending date cannot move.
Identify the investor, as well as the country
This page primarily addresses Indian citizens living in the UAE. Eligible OCI investors can use certain routes too, but citizenship, OCI status, the asset and the intermediary's acceptance policy still need checking. A jointly held account, a family company and an individual's personal portfolio should each be assessed on their own facts.
If the Indian market itself is unfamiliar, start with the core NRI stock-market guide. It provides the foundation for understanding the market before country-specific logistics begin.
2. Check residency through three separate lenses
The word “resident” appears in several systems. A document or day count relevant to one system can be insufficient for another. It helps to label the question each time you use the word.
FEMA: which Indian financial routes fit your status?
FEMA residence concerns India's foreign-exchange framework. It affects banking and permitted investment arrangements. Your reason for leaving or returning, employment and intention to stay can matter; treating it as a single travel-day shortcut can produce an incomplete answer.
The practical question for your bank is whether your current records and proposed transactions match your actual status. Ask it to review an existing resident account rather than assuming that opening a new account fixes every older relationship. Use the FEMA and income-tax residency guide to prepare that discussion.
Indian income tax: what is your status for the relevant tax year?
The Income Tax Department confirms that individual residency tests continue under the Income-tax Act, 2025, including the special rules for certain departing or visiting Indian citizens. The new Act governs tax years beginning on or after 1 April 2026; earlier tax years remain under the earlier Act. Some cases involve the ₹15 lakh income threshold, a modified visitor test or deemed residence. These should be examined with the precise statutory conditions, rather than from a visa alone. See the Department's non-resident FAQs.
A UAE salary earner should not conclude that an absence of salary tax automatically settles the Indian deemed-residence question. “Liable to tax” and actually paying a tax amount are different issues. A fact-specific review is useful where the relevant income and residency conditions may apply.
UAE residence and the India–UAE treaty: which test and period apply?
UAE domestic tax residence can follow physical-presence or other connection tests, as explained in the FTA's tax residence and TRC guide. The applicable treaty has its own test. Article 4 of the India–UAE synthesised treaty text specifies at least 183 days of UAE presence in the calendar year concerned for an individual on the UAE side. Dual-residence facts can require the treaty's tie-breaker analysis.
Keep records for the correct period
Your Indian tax-year record and the treaty's calendar-year record should remain distinguishable. A spreadsheet with arrival date, departure date, country and supporting travel reference is more useful than a single remembered total. Keep evidence of employment and residence alongside it.
Consider someone who relocates part-way through a year. The passport, visa and employment start date may tell a coherent story, yet the qualifying presence period for a treaty claim still needs its own calculation. This is why a certificate issued for one period should not casually be reused for a different claim.
Investor note
Ask what a document proves
An Emirates ID can help establish identity. A bank's KYC acceptance can establish that its onboarding checks are complete. A tax-residence certificate supports a specified residence position and period. Keep a note of the question each document answers before relying on it elsewhere.
3. Choose banking around the funds and the intended exit
Banking decisions become clearer when you separate new UAE savings, Indian receipts and existing investments. The account name is one part of the arrangement; the source, permitted credits and product route also matter.
NRE, NRO and FCNR(B) serve different purposes
RBI's Deposit Regulations distinguish rupee NRE/NRO accounts from foreign-currency FCNR(B) deposits. NRE commonly receives eligible overseas remittances and other permitted credits. NRO commonly handles legitimate Indian dues and other permitted credits. FCNR(B) is a term-deposit structure in a permitted foreign currency. It does not provide securities trading access by itself.
| Structure | A question it helps you investigate | A separate check to complete |
|---|---|---|
| NRE | Where should eligible funds from abroad enter the Indian arrangement? | Will the specific investment preserve the intended repatriation treatment? |
| NRO | How should Indian receipts and relevant existing balances be handled? | What category of later outward remittance would apply? |
| FCNR(B) | Is an eligible foreign-currency deposit relevant to the savings objective? | Which currency, maturity, withdrawal conditions and funding route are offered? |
| Demat and trading | How will permitted securities be held and bought or sold? | Which bank account and product route are linked to this setup? |
This table is a starting set of questions. For the full account comparison and the role of PIS terminology, read NRE vs NRO vs PIS.
Indian income needs its own traceable trail
If you receive rent in India while earning salary in the UAE, keep separate records of both sources. It becomes harder to explain a later transfer when an account statement mixes rent, family transfers, sale proceeds and older balances without supporting notes.
The amount credited to an account is only the beginning of the record. Keep the rent agreement or receipt, sale contract, investment statement or other evidence that explains the source. Record which amounts are income and which amounts represent previously invested capital.
Some permitted Indian current income can be credited to NRE when the applicable conditions and tax checks are met. That exception is a reason to ask the authorised dealer about the precise credit, rather than treating every Indian receipt identically.
Confirm the investment route before selecting the bank–broker combination
RBI's foreign-investment Master Direction distinguishes investment on a repatriation basis from investment on a non-repatriation basis. Its listed-equity arrangements include designated banking requirements. Operational labels used by a provider should be checked against the actual permitted transaction.
Ask for a clear answer on the funding account, purchase route, settlement destination and sale-proceeds destination. Save that answer. A banking relationship advertised to NRIs may still require a separate securities setup.
Avoid choosing the combination solely because a broker's headline trading fee is low. Add the bank's relevant charges, service access from the UAE, account maintenance requirements and ability to provide records. The useful comparison is the complete relationship you will operate.
4. Complete the UAE onboarding without unnecessary paperwork
Your application channel shapes document verification. A process that works at a bank's UAE office may differ from an application sent directly to India. The detailed UAE account-opening guide explains these channels and the questions to ask before certification or couriering.
Build a document folder that is easy to maintain
Prepare clear, current copies of identity, UAE status, address, bank and tax-identity documents relevant to the provider's checklist. Keep the original document date, expiry date and version visible in your own filing system. When an updated address proof replaces an older one, archive the older copy rather than allowing both to circulate without context.
The purpose is consistency. A shortened name at one institution, an outdated overseas address at another and an old resident declaration at a third can slow an otherwise straightforward application. Resolve discrepancies before adding a new relationship.
| Record group | What to organise | What to confirm with the provider |
|---|---|---|
| Identity and status | Passport, relevant UAE residence/status evidence and OCI evidence where applicable | Accepted document combination and validity |
| Address and contact | Current UAE address evidence, Indian address where requested, working email and mobile | Accepted proof, overseas contact access and update process |
| Banking and funds | Account details and evidence explaining the original money | Permitted funding account and name matching |
| Investor and tax declarations | PAN where required, KYC, tax-residence information and relevant FATCA/CRS details | Current form, verification channel and update obligations |
The checklist differs by institution and product. It should be downloaded from the selected provider before money is spent on certification. A treaty-purpose TRC should be considered as part of a tax claim, rather than treated as a universal account-opening prerequisite.
Test the relationship after activation
Check whether you can access statements, update contact details, receive verification messages and reach support from the UAE. A successful account number does not demonstrate that every service you will use later is working.
For securities, complete the separate NRI Demat and trading process. Before making the first substantial transfer, confirm that the funding route, investor status and settlement arrangements are correctly recorded. Keep the acknowledgement or confirmation in the same folder as the application.
Keep control of your own access
A helper should not become the only person who can retrieve your statements or identify your holdings. Record your own account and folio details securely. Understand any mandate or power of attorney before signing it, including the scope of authority and the revocation process.
Use the NRI KYC, compliance and investor-safety guide for ongoing maintenance. It is especially relevant when a document expires, an overseas address changes or a provider asks for re-KYC.
5. Match the Indian investment to a permitted, workable route
The UAE is your location; it is not a separate asset class. Choosing a product still requires understanding what you own, how it can lose value, how easily it can be sold and how the intermediary handles your status.
Individual Indian shares
For direct shares, investigate company economics, valuation, concentration and the operational route together. Access to a trading screen does not replace either business research or route confirmation.
Review the NRI investment-limits guide if you need to understand holding restrictions. Large positions, restricted activities or unusual transactions deserve a specific check before an order is placed. Do not assume that a familiar ticker means every proposed transaction is permitted for your account.
Keep a reason for each holding in your own words. If the original explanation depends entirely on someone else's tip, it will be difficult to reassess the position when the price falls or the business changes. The fundamental-analysis checklist provides a process for that review.
Mutual funds
A mutual fund can simplify security selection, but it still requires checking the scheme, risk, costs and provider's NRI acceptance. Country-of-residence acceptance and document requirements should be confirmed for the actual AMC or platform.
The tax classification follows the instrument and applicable law, not the word “fund” on a marketing page. A fund holding equities, debt, overseas securities or a mixture can raise different questions. An equity-oriented scheme and a debt-oriented scheme should not automatically share the same tax worksheet.
Read NRI mutual-fund investing before choosing the mandate and purchase channel. For an ongoing contribution plan, estimate what you can maintain through changing UAE expenses; a projected calculator result is not a commitment to a future return.
India-listed ETFs
An ETF has a quoted market price and an underlying portfolio. Understand the exposure, trading liquidity, spread, tracking difference and order process. A fund name containing a familiar index is insufficient to compare two products.
If your broker accepts the investment, confirm the permitted funding and settlement setup for that ETF as well. The NRI ETF guide brings the Demat, product and operating questions together.
IPOs and corporate actions
An IPO is a specific offer with its own terms and application process. Read the offer documents and confirm NRI eligibility, application category and payment arrangements before applying. The NRI IPO guide explains the process; a proposed listing gain should not be treated as assured.
Existing holdings can also generate rights offers, dividends, buybacks, mergers or other events while you are abroad. Keep your email and banking records current so you can identify a deadline and locate the relevant announcement. Use corporate actions for NRIs when an event affects tax, holdings or proceeds.
Deposits, bonds, NPS and property
These deserve their own eligibility, liquidity and tax review. A deposit and a listed share solve different problems, and property can involve title, maintenance, transaction costs and remittance issues that do not appear in a broker account.
The NRI investment-options guide is the place to compare the broader menu. Choose the product because its features fit the purpose, after confirming the route.
Risk
Count concentration across your whole financial life
Your job, business, property, future spending and investments can create overlapping exposures. Review those exposures together. Several account statements can still represent one concentrated economic bet, while a diversified-looking portfolio can remain poorly matched to a near-term spending need.
6. Separate Indian tax, UAE treatment and treaty relief
The practical tax sequence is to identify the taxpayer, the income, the asset and the relevant period. Then assess domestic rules and any applicable treaty provision. A country label is not enough to produce the answer.
What UAE treatment does, and what still needs review
The FTA states that wages, personal investment income and qualifying real-estate investment income are outside the business-income categories considered for natural-person corporate tax. Its natural-person guidance distinguishes those categories from a business or business activity with turnover above AED 1 million in the calendar year. Income earned through a business requires its own classification.
For an Indian portfolio, separately determine the Indian tax consequences. Keep personal investing distinct from business investing in your records and in the facts provided to an adviser. The treatment of an individual's savings should not be copied to a company or trading business.
The asset matters under the India–UAE treaty
Article 13 of the official synthesised treaty distinguishes share gains and gains on other property. Indian-company share gains can be taxable in India under the relevant provisions. Paragraph 5 allocates gains on property outside the preceding categories to the residence state. Applying that residual category to a particular instrument requires classification, eligibility and an anti-abuse review; it is not a blanket exemption for every Indian investment.
This distinction can be relevant to fund units, but a marketing claim about “UAE tax-free funds” should not determine a sale. Obtain an analysis of the actual instrument and your facts before relying on a treaty position. Dividends and interest also require their own treatment rather than a capital-gains shortcut.
TRC and Indian Form 41 support the claim
The FTA's certificate service distinguishes certificates for treaty purposes from certificates for other purposes. Choose the request that matches the claim and period.
India's e-filing portal identifies Form 41, previously Form 10F, and its Form 41 manual explains the supporting particulars for a non-resident treaty-relief claim. Check the form applicable to the relevant period, complete the required verification and retain the acknowledgement.
For the broader documentation sequence, read DTAA for NRIs: TRC and Form 41. A certificate establishes evidence relevant to residence; the claim must still fit the income and treaty article.
Distinguish TDS from the completed tax position
When tax has been deducted, reconcile the deduction with the transaction and the return position. The deducted amount should not automatically be treated as the final liability, nor should an expected refund be treated as cash already available.
Keep gross proceeds, acquisition cost, fees, tax withheld and the resulting bank credit as separate entries. This helps explain why the broker's sale value differs from the money actually received. The NRI capital-gains and TDS guide covers the listed-share calculations in detail.
If a treaty claim, residency uncertainty or unusual asset materially changes the result, resolve it before committing to a sizeable transaction. The useful deliverable from a cross-border tax adviser is an explained position with supporting documents, rather than a verbal promise of a lower deduction.
7. Compare UAE-to-India transfers by the amount that arrives
For an inbound investment transfer, compare quotes at the same time and for the same total dirham debit. A “zero fee” label tells you little if the conversion rate gives fewer rupees. A better displayed rate may also be offset by charges elsewhere in the journey.
Use one clear comparison basis
Ask each provider for the total AED debited and the net INR expected in the beneficiary account. Clarify whether an intermediary or receiving-bank deduction can change the quoted amount, whether the rate is locked, and what happens if the transfer needs additional documents.
🧮 Simple calculation
The net-credit comparison can overturn a zero-fee headline
Hypothetical quote A debits AED 10,000 and delivers ₹218,500 after all stated charges. Quote B debits the same AED 10,000 and delivers ₹220,000 after all stated charges. Quote B delivers ₹1,500 more. The effective received rates are ₹21.85 and ₹22.00 per AED respectively. These are illustrative quotes, not current rates or provider offers.
This comparison only works if the assumptions match. If one quote excludes a charge that another includes, obtain the missing amount before comparing. Save the quote alongside the completed receipt so you can reconcile what actually happened.
Keep family support and investment funding understandable
Money sent for family spending and money intended for your own investment can have different beneficiary and record requirements. Describe the actual purpose accurately. Avoid routing investment funds through an unrelated person's account simply because it is familiar or convenient.
For your own investing arrangement, confirm the permitted receiving account with the bank and product provider. Keep a receipt connecting the original AED debit to the Indian credit and the subsequent investment. If the provider asks about source of funds, a clear salary or savings trail is easier to explain than several unexplained intermediate transfers.
Separate transfer execution from market timing
A favourable currency quote does not establish that a share or fund is attractively priced. Similarly, a decision to invest does not mean the transfer quote is competitive. Review the two choices separately and record the assumptions for each.
Repeatedly waiting for a perfect rate can leave a spending or investment plan undefined. Equally, transferring everything at once without considering upcoming UAE expenses can create avoidable pressure. A workable plan should explain how much remains needed locally, when the transfer is useful, and what would cause you to change the plan.
8. Measure the result in the currency you will spend
A rupee statement answers what happened to the investment in INR. If you later spend the proceeds in AED, you need the conversion result too. Currency movements can amplify, reduce or reverse the result measured in the other currency.
A simple two-rate example
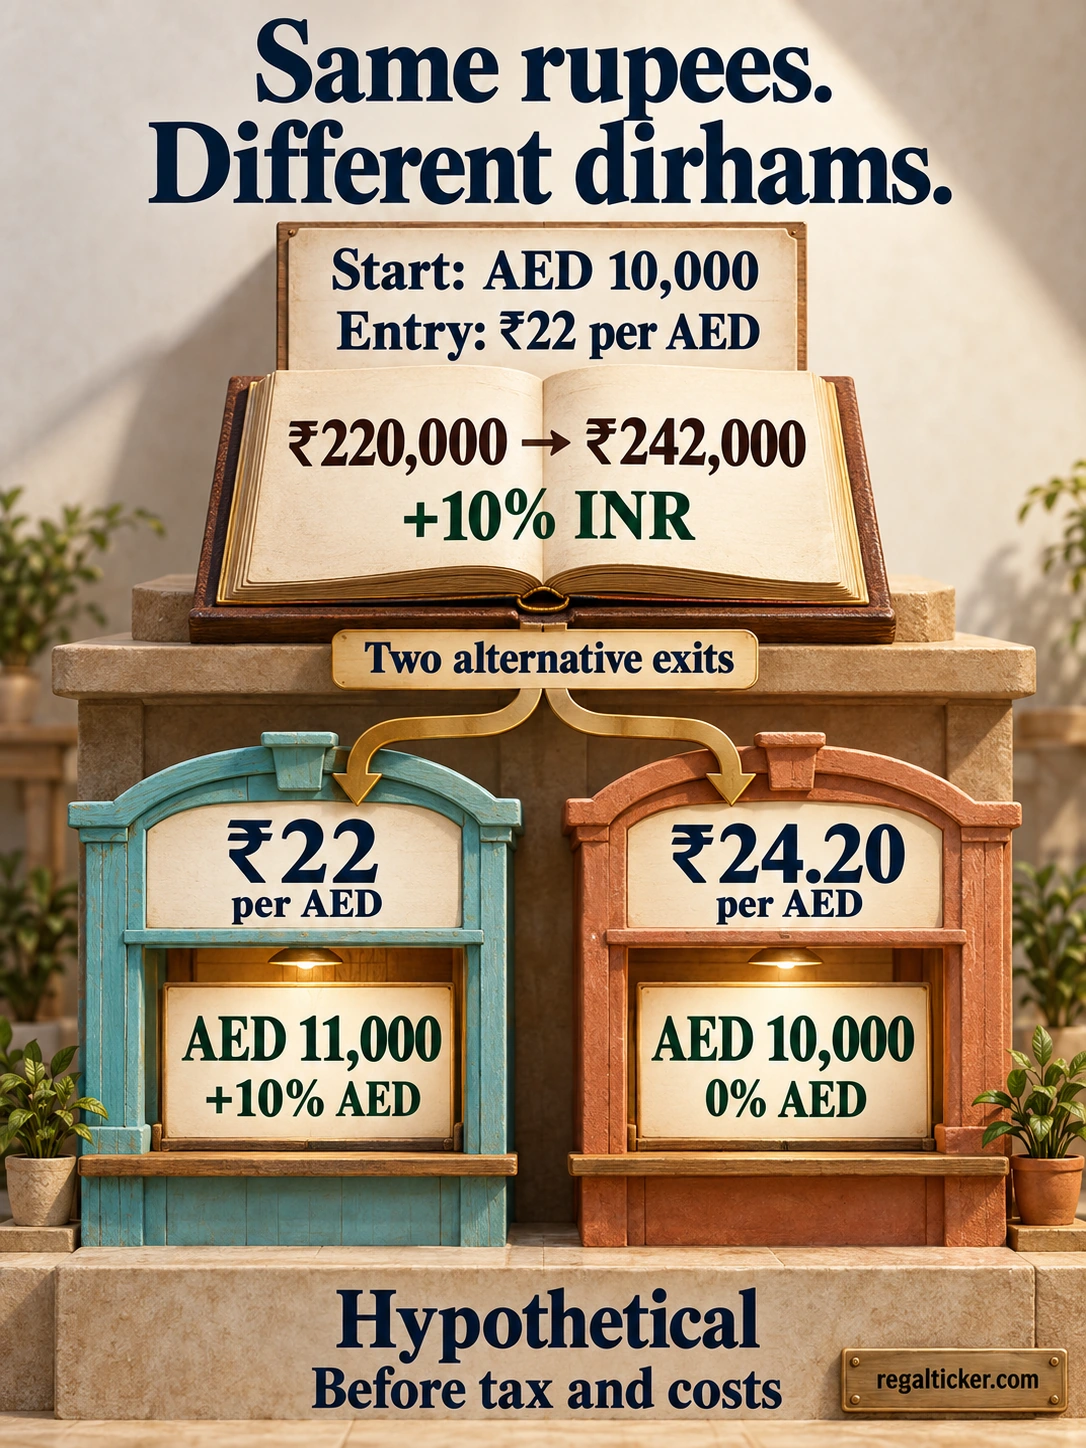
Assume AED 10,000 is converted at ₹22 per AED, producing ₹220,000. The investment rises by 10% to ₹242,000. Ignore tax, fees and distributions for this illustration.
| Exit conversion rate | AED value of ₹242,000 | Return relative to AED 10,000 |
|---|---|---|
| ₹22 per AED | AED 11,000 | +10% |
| ₹24.20 per AED | AED 10,000 | 0% |
| ₹20 per AED | AED 12,100 | +21% |
All three outcomes use the same ending investment value in rupees. The difference comes from the conversion rate. When the number of rupees needed to buy one dirham rises, those rupees buy fewer dirhams. When it falls, they buy more.
Use a formula with the rate direction labelled
For one initial conversion and one final conversion, with no interim flows, the before-cost formula is: AED return = (1 + INR investment return) × (entry INR per AED ÷ exit INR per AED) − 1.
In the zero-AED-gain row: 1.10 × (22 ÷ 24.20) − 1 = 0. The rates are hypothetical and the result is mathematical, not a forecast about the rupee or any investment.
Tax, spread and transfer charges reduce the amount available to spend. Where distributions, repeated contributions or withdrawals occur, track the actual dated cash flows instead of forcing them into this single-transfer formula.
Keep the rupee and dirham ledgers together
For each contribution, record the date, AED paid, INR received, transfer charge and investment amount. For a withdrawal, record the INR sold or redeemed, relevant deductions, INR available for conversion and actual AED received. This provides a consistent audit trail and a more meaningful personal return measure.
RegalTicker's XIRR calculator can help analyse dated cash flows when every input uses one consistent currency. For an AED view, use the actual AED contribution and receipt values; do not combine INR entries with AED entries in the same calculation. Hypothetical future conversions remain assumptions.
For an INR goal, the rupee result remains relevant. The point is to match the measurement to the goal while remaining aware of the other currency exposure. Familiarity with Indian assets does not remove that exposure.
9. Plan the route back to the UAE before the exit
A sale or redemption and an outward remittance are separate actions. Before selling for a UAE expense, find out which account will receive the proceeds, what documents the bank needs and when the funds can become available for conversion.
Identify the category of money
RBI distinguishes remittance of current income from the conditional facility covering eligible NRO balances and asset proceeds up to USD 1 million in an Indian financial year. NRE balances have their own repatriable framework. Tax compliance and the authorised dealer's checks still matter. The accounts FAQ sets out these distinctions.
There is an important investment-specific check too. Annex 4 of the foreign-investment Master Direction restricts repatriation of the invested amount and appreciation for the equity/LLP investments covered there on a non-repatriation basis. Do not assume that crediting sale proceeds to NRO makes those restrictions disappear under a general remittance limit.
Ask the bank to trace the actual asset and original route. Older resident-held assets, a newly acquired investment and Indian current income need not produce identical documentation or treatment. Use the NRI repatriation guide for the complete process.
Use the current reporting forms when required
For the applicable new-law process, the Income Tax Department provides Form 145 and Form 146, formerly Form 15CB. Form 145 succeeds the earlier Form 15CA reporting framework; Form 146 is the accountant's certificate used where required. The relevant form part and any exception depend on the payment and applicable rules. A CA certificate is not an automatic requirement for every transfer.
Confirm the requirements with the authorised dealer and your tax adviser before scheduling the transfer. A form labelled with an older number in a bank's article should be checked against the current process, rather than copied without review.
Leave room for records and settlement
Where a UAE payment has a firm due date, identify the steps that must finish first: sale or redemption, settlement, tax documentation, bank review, conversion and transfer. Check the current timelines of the relevant providers. There is no useful universal promise that this complete chain always takes a fixed number of days.
Maintain a readily available document pack: original funding evidence, acquisition and sale records, bank statements, relevant tax certificates and completed reporting acknowledgements. It is easier to obtain missing information before an account or overseas contact changes.
10. Maintain the setup as your life changes
A good investment arrangement should be understandable six months later, not only on application day. Changes in address, employment, family circumstances or country can affect records even if the holdings stay the same.
Review access and declarations periodically
Check your contact information across the bank, broker, depository and fund relationships you use. Confirm you can retrieve statements and that nomination records reflect your current wishes. Review a re-KYC request through the provider's official channel.
Tax-residence declarations should describe the actual facts. If you move from UAE to another country, tell the relevant institutions and check product acceptance again. An earlier UAE onboarding decision should not become a permanent assumption after you relocate.
Make the portfolio discoverable to your family
Maintain a secure inventory of banks, brokers, folios, account identifiers and the location of important records. It should help a trusted person identify the institutions and process without exposing passwords or encouraging shared login access.
Nomination, ownership and inheritance involve different legal questions. Review the NRI nomination, gifting and inheritance guide before assuming that one name in a nominee field settles every succession issue. Families with assets or heirs in multiple countries may need coordinated legal advice.
Prepare a return to India before closing UAE access
Before relocating, download relevant UAE statements, employment records, transfer history and investment cost information. Identify how you will obtain any outstanding tax-residence or travel evidence after departure. Update contact channels while you can still access them.
Returning can require changes to Indian banking and investor records as the relevant status changes. Possible RNOR treatment follows its own conditions; it should not be assumed from the fact of returning alone. The returning-to-India investment and tax checklist connects these steps.
A relocation is a reason to review holdings, liquidity and records. It does not by itself provide an investment reason to sell everything. Separate the required administrative updates from the financial decisions and keep a record of both.
11. See how the decisions connect in three everyday cases
The following people are fictional. Their situations show how to organise a review; they do not imply a preferred bank, product, allocation or tax outcome.
Meera starts investing part of a Dubai salary
Meera has worked in Dubai for several years and wants to begin an Indian portfolio. She expects some future spending in India but has not decided whether she will retire there. Her first task is to write down which money must remain available for current UAE expenses and which can serve the longer-term goal.
She lists her existing Indian accounts and asks the bank to review their status. She then confirms the source-of-funds and investment route with the bank and chosen intermediary. Her folder connects the original AED transfer, Indian credit and first purchase. She keeps the INR portfolio result and AED cost together, making a future currency review possible.
Her next reading depends on the chosen product: the Demat guide for direct securities, or the mutual-fund guide for a fund journey. She can move forward without treating every account application as the same process.
Imran has Indian rent and wants money for a UAE expense
Imran receives rent in India and also holds investments acquired at different times. He needs to move some money for a UAE expense. He separates the rent record from investment sale proceeds and asks the authorised dealer to identify the applicable remittance category for each.
Before selling, he obtains the relevant tax and acquisition records and checks the original investment route. He does not use an account balance alone as evidence that every rupee has the same outward-transfer treatment. His useful next guide is repatriation from India.
Kavya plans to move from Abu Dhabi back to India
Kavya is preparing for a permanent move. She downloads overseas statements and transfer records, identifies upcoming commitments, and makes a list of institutions that need updated contact and status information. She obtains a year-specific residency review instead of trying to infer her Indian tax position from the moving date.
She also reviews nomination and access arrangements so her family can locate the portfolio. Her sequence begins with the returning-to-India checklist and then branches into the banking, tax and ownership guides relevant to her records.
12. Use a practical review before the next transaction
The purpose of a review is to identify the next unresolved question. It does not need to become a stack of paperwork unrelated to the transaction you are making.
Before transferring, buying, selling or relocating
- State the goal, spending date and spending currency in one sentence.
- Identify the taxpayer, investor and source of the actual funds.
- Check the relevant status and period; preserve travel and residence records.
- Confirm the permitted receiving account and product-specific investment route.
- Check provider acceptance, documents, fees and access from your current country.
- Save evidence connecting the transfer to the investment and later proceeds.
- Identify the income or instrument before applying a tax or treaty position.
- Compare transfers using the net amount delivered on the same debit basis.
- Plan the exit account, reporting documents and onward currency conversion.
- Update the arrangement when your country, contacts, ownership or residence changes.
Use calculators after defining the assumptions
The SIP calculator can illustrate a contribution plan, and the stock-return calculator can help with a share-return calculation. They do not establish which investment is permitted for you or predict its future result.
The capital-gains tax calculator is useful within the transaction types and assumptions it supports. Treat any NRI withholding, treaty claim, currency conversion and bank remittance review as separate checks. Read the tool's scope before interpreting its output.
If one item remains uncertain, use the relevant guide or ask the institution a specific question. “Where are the sale proceeds credited under this route?” is easier to resolve than “Is this account best for all my investments?” Save the response with the transaction records.
Frequently asked questions
Can I invest in Indian shares while living in Dubai or Abu Dhabi?
Eligible investors can use permitted Indian routes with the required bank, broker, Demat and investor onboarding. Confirm the actual investment, funding route and provider acceptance. Start with the NRI Demat guide when banking is ready and securities access is the next step.
Should every UAE NRI use only an NRE account?
Identify the source and purpose of each balance first. A UAE salary transfer and Indian receipts can require different handling. Read NRE vs NRO vs PIS, then ask the authorised dealer about the precise credits and investment route you intend to use.
Does a UAE residence visa make my Indian investment gains tax-free?
A visa establishes a residence-related fact; it does not calculate Indian tax or identify the treaty article for an asset. Check the taxpayer, income, relevant period and eligibility. The UAE and Indian questions need separate review.
Can I use one UAE TRC for any year or income?
Match the certificate purpose and covered period to the proposed claim. Then assess the relevant income and treaty provision. The certificate does not itself explain the tax treatment of every asset. Use the FTA service and India's current treaty-documentation process for the actual case.
Are all Indian mutual-fund gains exempt under the India–UAE treaty?
Do not assume this from the country of residence or fund label. Classification of the actual units, treaty eligibility, documents and anti-abuse conditions need review. Resolve a material claim before a sale rather than relying on a general advertising statement.
Can I complete account opening from the UAE without visiting India?
Providers offer different application and verification channels. The available route depends on the bank and applicant. The UAE account-opening guide explains how to confirm the current process before arranging certification or travel.
Can I keep using my old resident accounts after moving to the UAE?
Ask each relevant institution to review the status and records against your changed circumstances. Banking and investment records can require separate updates. Opening an additional account should not leave the earlier relationships unreviewed.
Can a positive INR return become a zero or negative AED return?
Yes. In this guide's hypothetical example, a 10% rupee gain produces a zero dirham gain before costs when the INR-per-AED conversion rate also rises by 10%. Tax, spread and fees can further change the spending amount. Track both currencies using consistently labelled rates.
Does the NRO USD 1 million facility override every investment restriction?
Do not treat the general facility as permission for every balance or asset. Ask the authorised dealer to identify the source and original investment route, including any specific non-repatriation restrictions. The detailed repatriation guide is the next step.
Must every remittance have a chartered-accountant certificate?
The applicable reporting and certificate requirements depend on the payment and rules. Identify the taxability, form part and any exception with the authorised dealer or adviser. India's current portal provides Forms 145 and 146 for the relevant new-law process; older periods and procedures should be checked separately.
What should I review if I move from UAE to another country?
Update contact and tax-residence information, check product acceptance for the new country, and preserve the earlier transaction records. Reassess future spending currency and any treaty claim. The earlier UAE arrangement may need changes even if you keep the same assets.
What should I read first if I am completely new to investing?
Begin with the NRI stock-market introduction, then follow the situation table near the beginning of this page. Understanding the asset and the purpose of the money makes the account and country-specific decisions easier to assess.
Final takeaway
Make the next decision with a complete picture
Begin with your own situation and resolve the next practical question: status, account, product, tax, transfer or return to India. Keep the records that connect each step. A useful UAE-to-India plan explains where the money came from, what it is intended to do, which route it follows and how it becomes available in the currency you eventually need.
Verify through official sources
Official references
- RBI — Deposit Regulations, amended through June 2026
- RBI — Non-resident accounts FAQ
- RBI — Master Direction on Foreign Investment in India
- Income Tax Department — Non-resident FAQs under the Income-tax Act, 2025
- Income Tax Department — India–UAE DTAA synthesised text
- UAE FTA — Tax Resident and Tax Residency Certificate guide
- UAE FTA — Issuance of Tax Certificates for Tax Residency
- UAE FTA — Basis of Taxation for Natural Persons
- Income Tax Department — Form 41 and legacy Form 10F
- Income Tax Department — Form 41 User Manual
- Income Tax Department — Form 145 and legacy Form 15CA, User Manual
- Income Tax Department — Form 146 and legacy Form 15CB
Educational disclaimer: This page provides general investor education, reviewed on 7 October 2026. It does not provide personalised investment, tax or legal advice. The correct treatment depends on the investor, instrument, period and transaction. Use current official rules and provider requirements, and obtain qualified advice where your facts or a material treaty claim require it. The people, transfer quotes and currency rates used in examples are hypothetical.