⚡ Quick answer
Indian equities delivered their strongest weekly performance in six months during the week ended 16 October 2026, but the headline rebound did not remove every risk that had pressured the market in recent weeks.
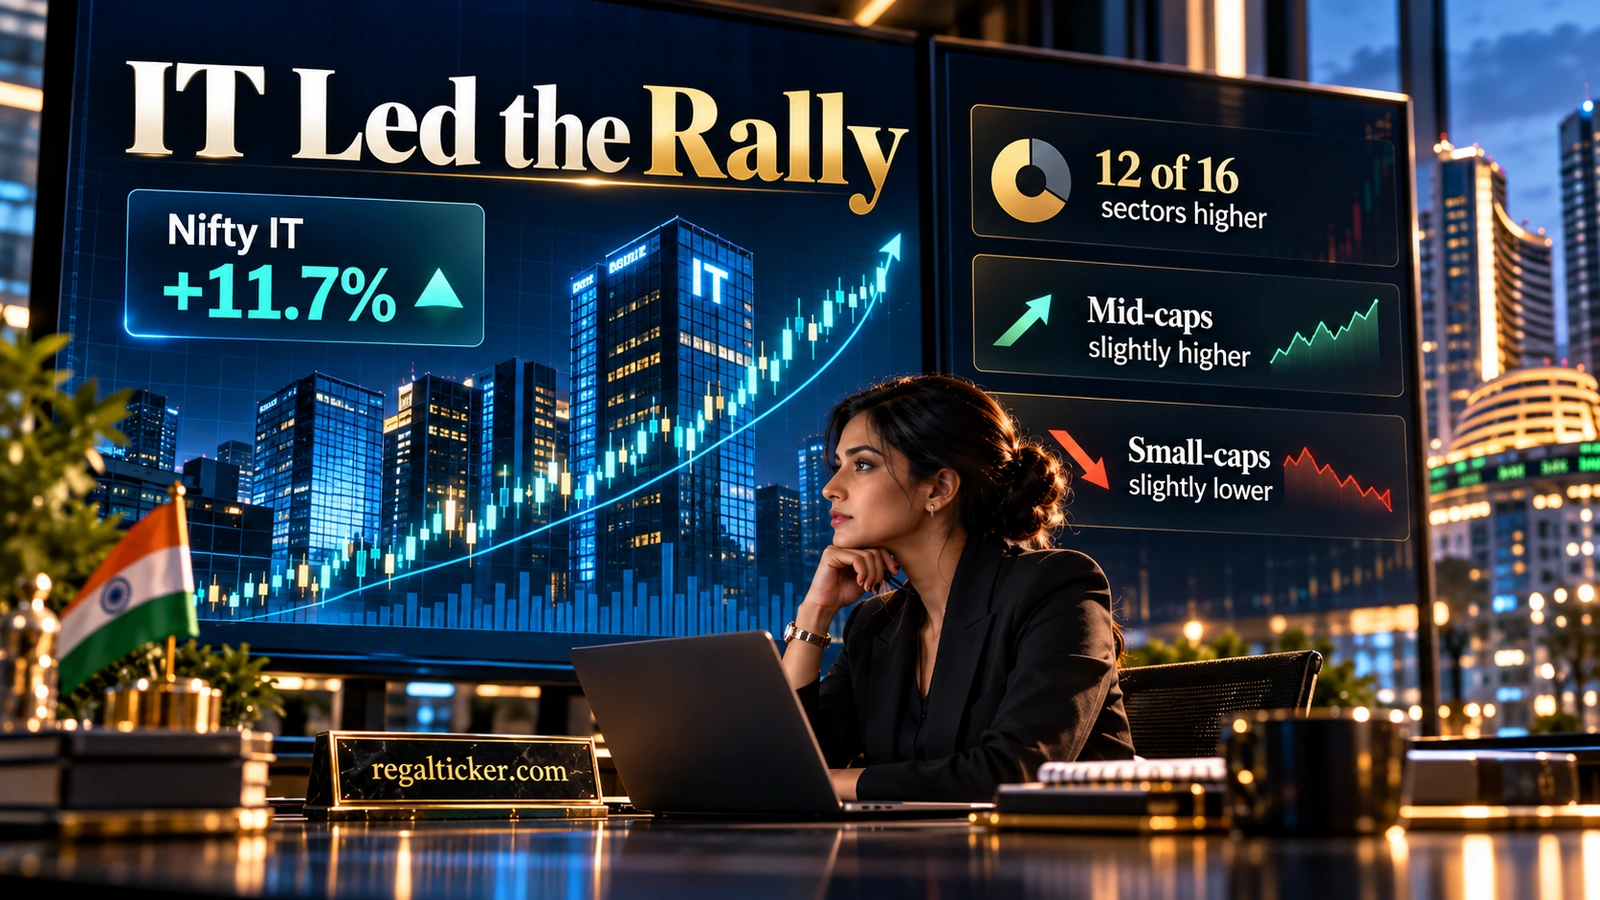
The Nifty 50 rose 2.8% to 23,146.15 and the BSE Sensex gained 3.1% to 74,729.27. The biggest driver was information technology: Nifty IT jumped 11.7% for the week, its strongest weekly advance in about 18 years, after a run of better-than-feared quarterly results revived interest in large technology companies.
The recovery was important because it followed a difficult period of foreign selling, high crude oil prices, a weak rupee and concern about tighter monetary conditions. Yet the week was not a simple broad-market risk-on move. Mid-cap shares only edged higher and small-caps finished slightly lower, even as 12 of 16 major sectors advanced. Foreign institutions also remained net sellers across the five-session week despite turning buyers on Friday.
This weekly review separates those signals instead of treating the index rebound as a forecast. It looks at benchmark performance, sector leadership, institutional flows, the rupee and crude oil, earnings, and the events that may shape the next trading week.
Why This Matters
The week’s main message was not simply “the market went up.” Large-cap IT drove a powerful rebound, the rupee strengthened sharply and foreign cash-market flows improved on Friday, but crude remained above $100 a barrel and broader-market participation was much less convincing than the benchmark gains.
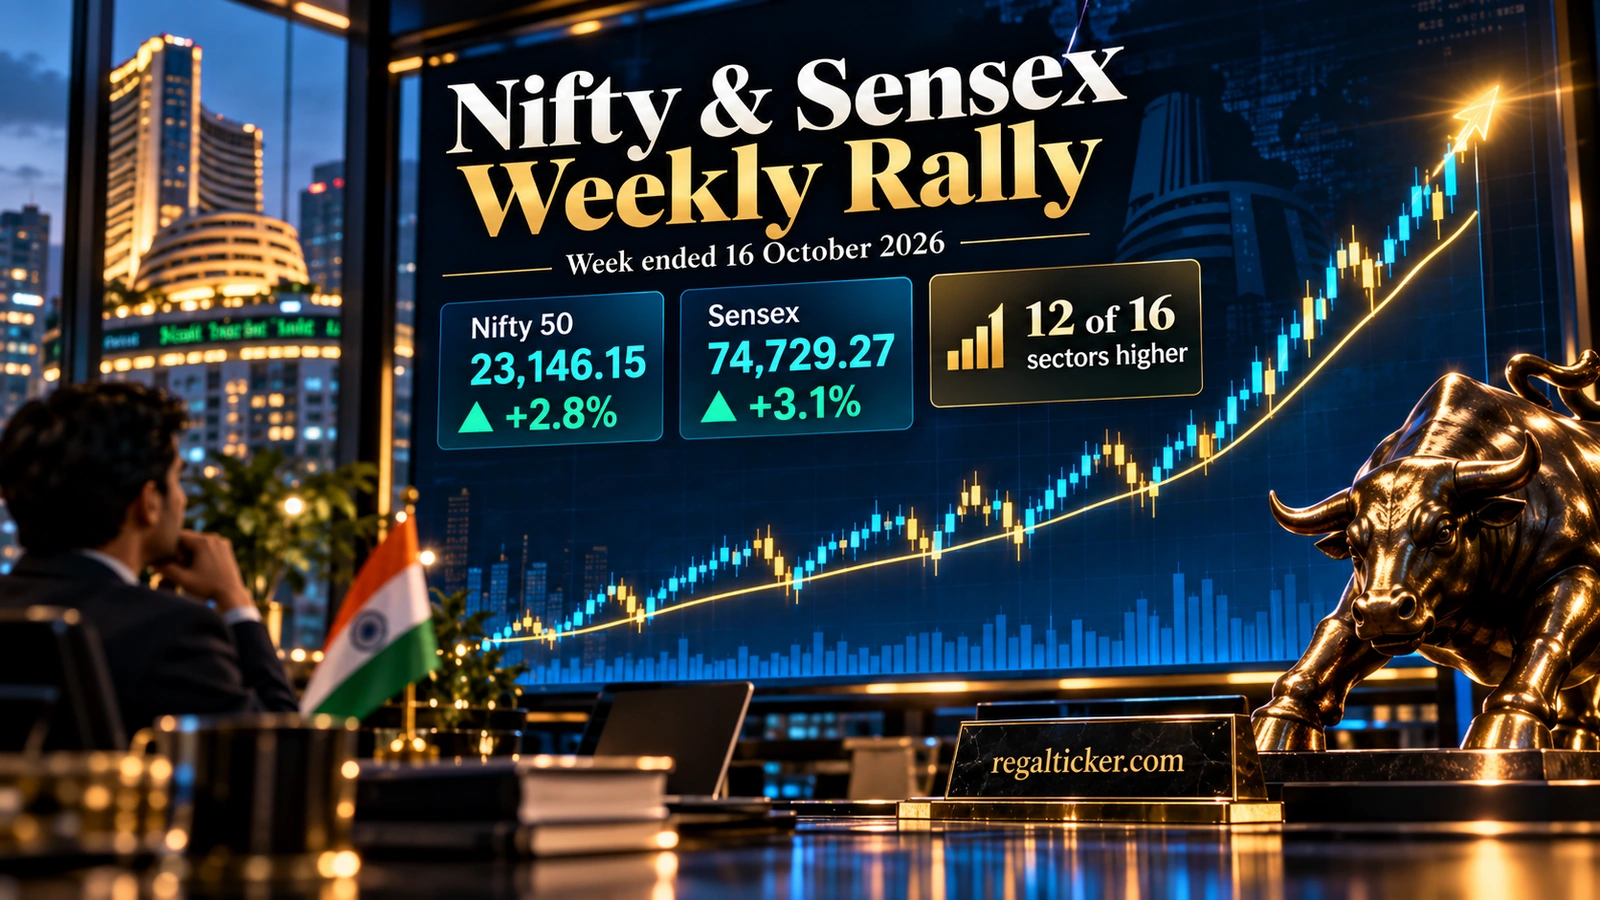
Indian Stock Market Weekly Snapshot: 12–16 October 2026
The benchmark recovery was substantial.
| Market measure | Week ended 16 October 2026 | Weekly picture |
|---|---|---|
| Nifty 50 | 23,146.15 | +2.8% |
| BSE Sensex | 74,729.27 | +3.1% |
| Nifty IT | — | +11.7% |
| Major sectors advancing | 12 of 16 | Broad sector participation, but uneven |
| Mid-caps | — | Slightly higher |
| Small-caps | — | Slightly lower |
| Indian rupee | ₹94.96 per US dollar | About +2% for the week |
| Brent crude | About $105.92 per barrel on Friday | About +1.2% for the week |
The benchmark numbers make the recovery look broad, but the detail matters. A large part of the week’s strength came from technology stocks. That concentration means investors should distinguish between a benchmark rebound and a complete change in market character.
For readers who want the index mechanics behind these moves, see What Are NIFTY 50 and SENSEX? before interpreting a weekly percentage change as a statement about every listed company.
Highlight
Key point
A rising Nifty does not mean every segment of the market participated equally. Index weights, sector concentration and the behaviour of large companies can make benchmark performance stronger than the broader market.
Why Nifty and Sensex Rose This Week
The week began with several of the same concerns that had dominated recent trading: foreign outflows, high oil prices, inflation risk and uncertainty about the path of Indian interest rates. The change came as the week progressed.
Better-than-expected corporate results, particularly from technology companies, encouraged a sharp rotation back into large-cap IT. On Thursday, Indian benchmarks posted their biggest single-day gain in four months, and Friday extended that recovery. By the close on 16 October, Nifty and Sensex had recorded their best week in six months.
This rebound also coincided with a stronger rupee and some easing in global risk pressure. Those factors reduced part of the immediate stress that had been weighing on Indian assets.
However, a weekly rally should not be confused with proof that every earlier concern has disappeared. A one-week rebound also does not by itself redefine the broader market regime; readers who want that distinction can review Bull, Bear and Sideways Markets. Crude oil remained elevated, year-to-date foreign outflows were still large and the broader market did not match the benchmark’s strength.
Investor note
Important point
A strong rebound can be genuine and still remain incomplete. Weekly reviews are most useful when they separate what improved from what remains unresolved.
Nifty IT Was the Week’s Biggest Story
Technology was the clear sector leader.
Nifty IT rose 11.7% over the week, its steepest weekly advance in about 18 years. TCS, Infosys, HCLTech and Tech Mahindra were among the major contributors, with gains across the group ranging roughly from 13% to 18% over the week.
The trigger was earnings. HCLTech, Tech Mahindra and Wipro delivered results or commentary that improved sentiment around demand, margins or the possibility that delayed deals could convert in coming quarters. Wipro, for example, reported second-quarter revenue above analyst expectations, even though deal bookings remained weaker year on year and guidance stayed cautious.
That combination is important. The market did not suddenly receive evidence that every structural challenge in global technology spending had vanished. Instead, expectations had become weak enough that better-than-feared results were sufficient to produce a powerful re-rating.
💡 Real example
Simple example
A sector can rally sharply even when its long-term questions are not fully resolved. When expectations are depressed, earnings that are merely better than feared can produce large price moves because the market is repricing the gap between pessimistic assumptions and actual results.
The practical lesson is to separate a stock-price reaction from the underlying business evidence. A weekly sector surge is useful context, but investors still need to examine earnings quality, deal conversion, margins, cash flow and valuation company by company. If quarterly results are driving the move, How the Three Financial Statements Are Connected provides a useful framework for checking whether profit, cash flow and the balance sheet tell a consistent story.
Market Breadth: Large Caps Led, Broader Markets Lagged
The sector count looked healthy: 12 of 16 major sectors finished the week higher. But the market-cap picture was less impressive.
Mid-cap shares edged up, while small-caps ended slightly lower. This suggests that the strongest part of the rebound remained concentrated in larger companies and sectors such as IT rather than becoming a uniform broad-market rally.
That distinction matters because broader participation can help show whether improving sentiment is spreading beyond index heavyweights. A narrow rebound can still continue, but it carries a different message from a rally in which large-, mid- and small-cap segments all strengthen together.
| Large-cap-led rebound | Strong benchmark gains can occur quickly because heavyweight shares have large index influence. |
|---|---|
| Broad-market rebound | Mid-caps, small-caps and a wider group of sectors also participate, suggesting stronger market breadth. |
| This week | Sector participation improved, but small-caps still lagged and the recovery remained heavily influenced by IT. |
FII and DII Flows: Foreign Selling Persisted, Then Reversed on Friday
Institutional cash-market activity remained one of the most useful reality checks on the rally.
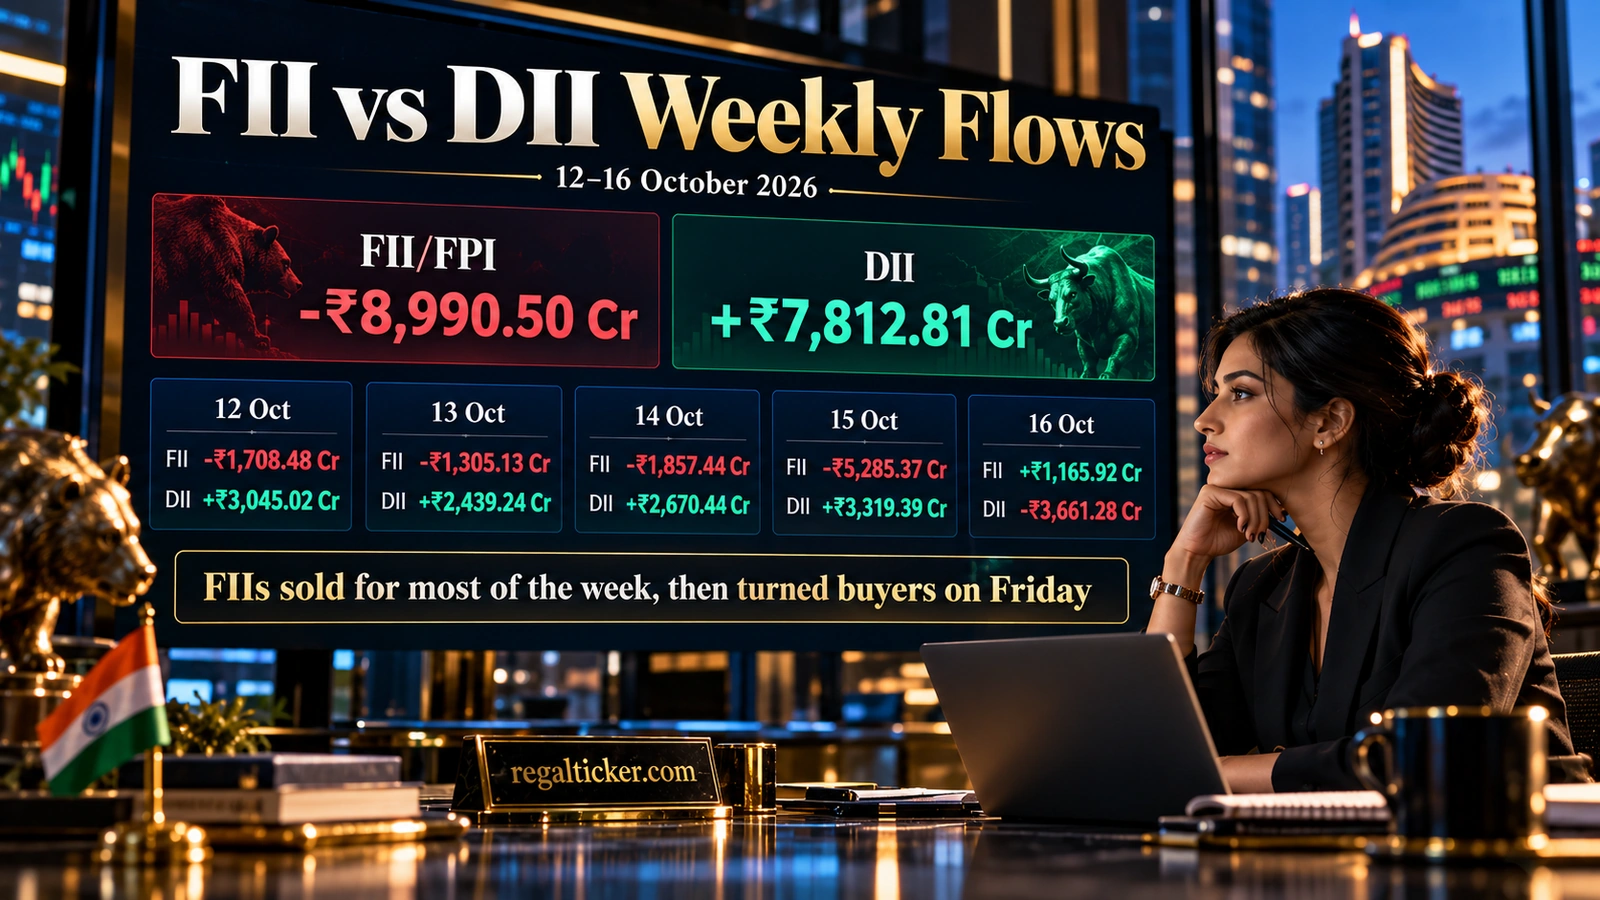
Using provisional exchange cash-market data, foreign institutions were net sellers on each session from Monday through Thursday. They turned net buyers on Friday, while domestic institutions moved to net selling.
| Date | FII/FPI net flow | DII net flow |
|---|---|---|
| 12 Oct | -₹1,708.48 crore | +₹3,045.02 crore |
| 13 Oct | -₹1,305.13 crore | +₹2,439.24 crore |
| 14 Oct | -₹1,857.44 crore | +₹2,670.44 crore |
| 15 Oct | -₹5,285.37 crore | +₹3,319.39 crore |
| 16 Oct | +₹1,165.92 crore | -₹3,661.28 crore |
| Week total | -₹8,990.50 crore | +₹7,812.81 crore |
The Friday reversal was notable because it broke the week’s earlier pattern. But one positive FII session is not enough to establish a durable return of foreign capital.
For a full explanation of what these numbers do and do not mean, read FII vs DII in Stock Market. The most important limitation is that cash-market net flow is a category-level balance for a stated segment. It does not reveal every institution’s complete position, derivatives exposure or reason for trading.
Caution
Check this carefully
Do not read “FII buying” or “DII selling” as an automatic market signal. Daily provisional flows describe completed activity. They do not predict the next session.
Rupee Strengthened, but Crude Oil Stayed Expensive
The currency market delivered one of the week’s strongest positive moves.
The rupee appreciated about 2% to ₹94.96 per US dollar, its best weekly performance in seven months. The move followed RBI measures aimed at reducing pressure on the currency and improving the functioning of the foreign-exchange market.
A stronger rupee can reduce some imported inflation pressure and lower the local-currency burden of dollar-priced imports. For India, that connection is especially important when oil prices are high.
But oil remained the main macro counterweight. Brent crude was around $105.92 per barrel on Friday and was still up about 1.2% for the week. Elevated oil prices can affect India through the import bill, inflation, corporate costs, the current account and expectations for monetary policy.
This produced an unusual combination: the rupee strengthened sharply even while oil remained expensive. That is why the currency rally should be read partly in the context of policy action, not simply as evidence that India’s external risks have disappeared.

Highlight
Rupee strength improved one part of the macro picture. Crude above $100 kept another major risk alive.
Earnings and Stocks in Focus
The week’s strongest price reactions were concentrated in companies where earnings changed expectations.
Technology led the market, but other large-cap names also influenced index performance. Bharti Airtel gained during the week amid renewed interest in telecom. Jio Financial Services moved in the opposite direction after quarterly profit fell sharply from the prior year, which had benefited from a one-time dividend.
The key lesson from a weekly market review is not to build a list of winners and losers. It is to identify the evidence that changed investor expectations. For company-specific headlines, use How to Verify Stock Market News and Announcements to trace the claim back to exchange filings before treating it as investment evidence.
This week, the central earnings question was whether large IT companies are moving from a weak-demand phase toward stabilisation. The answer is still mixed. Revenue and margins showed enough resilience to trigger a rally, but deal conversion, global technology spending and AI-related investment remain important variables.
For stock-level work, combine earnings evidence with the process in How to Analyse a Stock Technically rather than treating one strong weekly candle as sufficient evidence.
What to Watch Next Week: 19–23 October 2026
The next week has several identifiable triggers.
1
Weekend bank results
HDFC Bank, ICICI Bank and Axis Bank are scheduled to report Q2 results on 17 October. The market reaction on Monday will help test whether the rebound can broaden beyond technology.
2
Jio Platforms IPO
anchor bidding is scheduled for 19 October, with the public issue open from 21–23 October. At up to about $3.2 billion, the issue is large enough to matter for market liquidity and investor attention.
3
FII/FPI flows
Friday’s return to net buying becomes more meaningful only if it continues across multiple sessions.
4
Rupee
watch whether the currency can hold its sharp weekly improvement after policy-driven support.
5
Crude oil
Brent around $100+ remains a major inflation and external-balance variable for India.
6
Market breadth
a durable improvement would be stronger if mid- and small-cap participation improves rather than the rally remaining concentrated in index heavyweights.
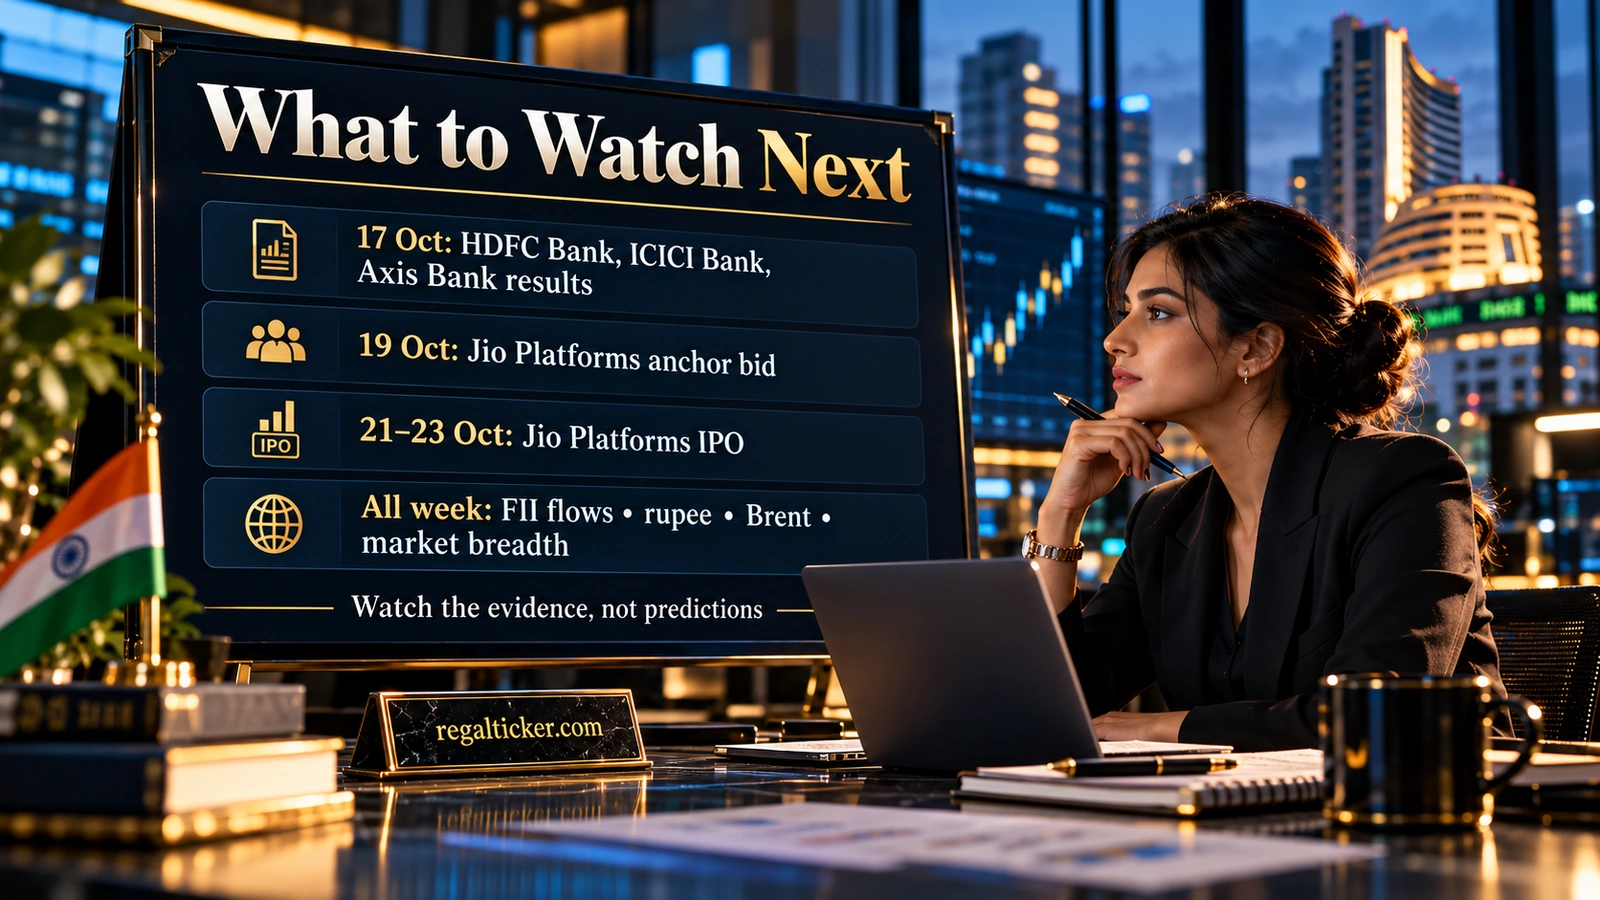
The purpose of this watchlist is not to predict where Nifty will trade next Friday. It identifies the evidence that can change the market narrative. If you are judging whether the rebound develops into a sustained price structure rather than a short-lived bounce, use the framework in Trend Analysis: Uptrend, Downtrend and Sideways Market.
What This Weekly Move Means for Investors
The strongest interpretation of the week is balanced.
The positive side is clear. Indian benchmarks delivered their best week in six months. Technology earnings improved sentiment, Nifty IT produced an exceptional rally, the rupee strengthened and foreign institutions returned as net cash-market buyers on Friday.
The unresolved side is equally important. Crude remained above $100, FII/FPI flows were still negative for the full week, small-caps did not participate in the benchmark rally and the year-to-date foreign outflow remained substantial.
For long-term investors, a weekly review should therefore be used as context rather than as a trading instruction. The week can help explain why portfolio prices moved, which sectors are changing expectations and which macro variables deserve attention. If you want to understand why changing expectations move quoted prices in the first place, see How Are Share Prices Decided?. A weekly review should not replace business analysis, valuation, diversification or personal risk limits.
Checklist before you act
- Did earnings improve, or did only the share price improve?
- Is sector leadership broadening or becoming more concentrated?
- Are FII/FPI flows improving over several sessions?
- Is the rupee strengthening without renewed oil pressure?
- Are mid- and small-cap shares participating?
- Are you changing a portfolio because of verified evidence or because of one strong week?
Frequently asked questions
How much did the Nifty 50 gain in the week ended 16 October 2026?
The Nifty 50 rose 2.8% for the week and closed at 23,146.15.
Why did the Indian stock market rise this week?
The main driver was a sharp rebound in large technology stocks after better-than-feared quarterly earnings. A stronger rupee and improved global sentiment also helped.
How much did Nifty IT rise this week?
Nifty IT gained 11.7%, its strongest weekly rise in about 18 years.
Were FIIs buyers or sellers this week?
Using provisional cash-market data for 12–16 October, FII/FPI activity was net selling of about ₹8,990.50 crore for the five sessions. They turned net buyers on Friday after selling from Monday through Thursday.
What is the biggest risk for the Indian market now?
There is no single risk, but elevated crude oil, foreign flows, inflation and the path of interest rates remain important. The durability of the earnings recovery and broader-market participation also matter.
What should investors watch next week?
The market reaction to 17 October bank results, Jio Platforms’ IPO, FII/FPI flows, the rupee, crude oil and whether market breadth improves beyond large-cap IT.
Final takeaway
What to remember
The week ended 16 October 2026 produced a genuine improvement in Indian equity-market sentiment. Nifty and Sensex posted their strongest weekly performance in six months and Nifty IT delivered an extraordinary 11.7% gain. Yet the rebound remained concentrated, weekly foreign flows were still negative and crude oil stayed above $100.
The evidence to watch next is therefore straightforward: earnings beyond IT, sustained FII/FPI participation, rupee stability, crude oil and broader market breadth. If those signals improve together, the recovery becomes more convincing. If they diverge, the headline index gain should be interpreted with more caution.
Investor note
Related tool: demerger cost records
For a shareholding affected by a demerger, use the Demerger Cost Basis Calculator with the company’s official allocation figures. Keep that working with the original acquisition records.
Verify through official sources
Official references
- Reuters — Earnings-driven IT bounce powers Indian shares to best week in six months
- Reuters — Rupee posts best week in seven months
- Reuters — Oil heads for weekly gain with focus on Middle East supply
- Reuters — Mukesh Ambani’s Jio seeks $108 billion valuation in record Indian IPO
- Moneycontrol — FII and DII cash-market activity on 12 October 2026
- Moneycontrol — FII and DII cash-market activity on 13 October 2026
- Moneycontrol — Indian market dashboard and 16 October FII/DII data
- Financial Express — HDFC Bank, ICICI Bank and Axis Bank Q2 results due 17 October 2026