“NRE Interest Is Tax-Free” Is Only an Indian Answer
An NRE fixed deposit can be exempt in India and taxable in Australia at the same time.
But Australia adds one important twist: not every Australian tax resident is taxed the same way on foreign investment income.
An ordinary Australian resident generally reports worldwide interest, including interest from Indian bank accounts. A qualifying Australian temporary resident generally does not declare most foreign investment income. That can put two people with identical NRE deposits in completely different Australian tax positions.
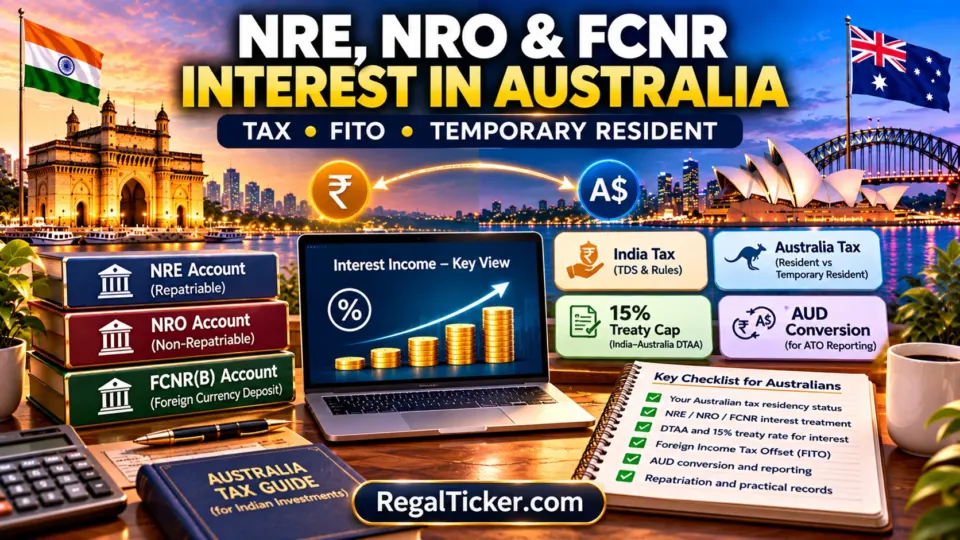
NRO interest adds a second layer because India normally taxes it too. The India–Australia treaty can generally cap Indian source-country tax on qualifying interest at 15% of the gross amount, while Australia’s Foreign Income Tax Offset can help relieve double taxation where the same interest is assessable in Australia.
FCNR(B) adds currency conversion, and cumulative deposits raise a timing question that is easy to get wrong.
The useful sequence is:
work out Australian status → identify the account → determine when interest is credited or received → apply India tax → apply treaty relief → convert to AUD → claim FITO where available.
⚡ Quick answer
Is NRE, NRO or FCNR Interest Taxable in Australia?
For an Australian tax resident who is not a temporary resident, foreign bank interest generally forms part of worldwide assessable income and must be reported in Australian dollars. Qualifying NRE and FCNR interest can be exempt in India but still taxable in Australia. NRO interest is generally taxable in India and can also be taxable in Australia; where the India–Australia treaty applies, Indian tax on qualifying interest is generally capped at 15% of the gross amount for a beneficially entitled Australian resident. A qualifying Australian temporary resident generally does not declare most foreign investment income, so ordinary Indian bank interest can fall outside Australian assessable income while that status applies.
Key takeaways
Australian tax residency and Australian temporary-resident status must be checked separately.
An ordinary Australian tax resident generally reports worldwide interest income, including Indian bank interest.
A qualifying Australian temporary resident generally does not declare most foreign investment income.
NRE interest can be exempt in India while remaining taxable to an ordinary Australian resident.
FCNR(B) interest can be exempt in India while remaining taxable to an ordinary Australian resident.
NRO interest is generally taxable in India and can also be assessable in Australia.
India’s current domestic treatment of NRO interest is generally 30% plus applicable surcharge and cess.
The India–Australia treaty generally caps qualifying Indian-source interest at 15% of gross interest when treaty conditions are met.
Indian TDS above the amount properly payable under the treaty should not automatically be treated as an Australian FITO entitlement.
Australia’s Foreign Income Tax Offset (FITO) generally applies only where foreign income tax has been paid on an amount included in Australian assessable income.
If the total FITO claimed exceeds AUD1,000, the FITO limit generally needs to be calculated.
Foreign interest and foreign tax must be converted into Australian dollars.
For individuals, ATO guidance says term-deposit interest is generally declared when it is credited or received; for many maturity deposits that means the maturity year.
Joint-account interest is generally divided equally unless the taxpayer can show unequal beneficial ownership.
Repatriating the interest to Australia is a banking step, not what creates the Australian tax event.
1. Start With Australian Tax Status, Not the Indian Account Type
The same NRE account can produce two different Australian tax outcomes depending on the account holder’s status.
ATO guidance distinguishes between:
- an Australian resident who is not a temporary resident;
- an Australian resident who also qualifies as a temporary resident; and
- a foreign resident.
For this guide, the first two are the important categories.
An ordinary Australian resident generally reports worldwide income.
A qualifying temporary resident generally does not declare most foreign investment income.
That means the correct first question is not:
“Is this NRE or NRO?”
It is:
“Am I an ordinary Australian resident or a qualifying temporary resident for this income year?”
RegalTicker’s Invest in India from Australia pillar explains that status distinction in detail.
2. Ordinary Australian Residents Generally Report Indian Bank Interest
ATO guidance specifically says Australian residents must declare interest from offshore bank accounts.
That includes interest from:
- savings accounts;
- fixed or term deposits;
- cash-management accounts; and
- other foreign deposit arrangements.
So an ordinary Australian resident with an Indian NRE, NRO or FCNR(B) deposit should not wait for the money to reach Australia.
The interest can be assessable while it remains in India.
A lack of an Australian tax slip does not remove the reporting obligation.
The account statement, deposit certificate and Indian tax record become the evidence.
3. Temporary Residents Can Be Exempt From Most Foreign Bank Interest
This is the strongest Australia-specific feature.
ATO guidance says an Australian temporary resident generally declares Australian income and certain foreign employment/service income, but other foreign income does not usually need to be declared.
Foreign bank interest is ordinary foreign investment income.
So a qualifying temporary resident can generally exclude ordinary NRE, NRO or FCNR(B) interest from Australian assessable income while the temporary-resident exemption applies.
That does not mean:
temporary visa = automatic foreign-income exemption.
The statutory temporary-resident conditions must actually be satisfied.
And the status should be checked each income year because it can change before the investment itself changes.
Investor note
Do Not Apply FITO to Income That Australia Does Not Assess
If temporary-resident rules make the foreign interest non-assessable in Australia, there is generally no Australian double-tax problem on that interest to solve through FITO.
4. NRE Interest: India Exemption, Australia Depends on Status
Current Indian guidance confirms that qualifying NRE interest remains exempt from Indian income tax where the statutory FEMA-linked conditions are met.
For an ordinary Australian resident, that Indian exemption does not carry across.
💡 Real example
Simple example
An Australian resident earns ₹200,000 of NRE interest during the year.
India may impose no income tax if the NRE exemption conditions are satisfied.
Australia can still include the AUD-equivalent interest in assessable foreign income.
Because India charged no qualifying income tax, there may be no FITO to offset the Australian liability.
For a qualifying Australian temporary resident, the result can be different because most foreign investment income is generally not declared.
That is why the phrase “NRE interest is tax-free” is incomplete without naming the country and status.
5. FCNR(B): Foreign-Currency Deposit, Australian-Dollar Tax Return
FCNR(B) deposits allow eligible NRIs to hold qualifying deposits in permitted foreign currencies.
Current Indian guidance also treats qualifying FCNR interest as exempt in India for eligible non-residents.
For an ordinary Australian resident, the foreign-currency interest generally still needs to be translated into AUD and reported.
💡 Real example
An FCNR(B) deposit earns USD1,800 of interest.
The Australian tax return does not report USD1,800.
It reports the appropriate AUD amount using the relevant conversion rules.
Keep:
deposit currency; interest credit or maturity date; foreign-currency interest; exchange-rate evidence; AUD-equivalent interest; and any Indian tax record.
For a temporary resident, ordinary foreign investment income can again fall under the temporary-resident exemption.
6. NRO Interest Is Where Both Countries Commonly Tax the Same Income
NRO interest is generally taxable in India.
Current Income Tax Department guidance describes NRO interest as taxable at 30% plus applicable surcharge and cess under domestic law.
An ordinary Australian resident can also have to report that same interest in Australia.
That creates the classic double-tax situation.
The practical record should separate:
- gross NRO interest;
- Indian TDS actually deducted;
- treaty rate claimed, if any;
- final Indian tax properly payable;
- Indian refund, if any;
- AUD-equivalent gross interest; and
- FITO claimed in Australia.
Do not treat the first TDS number shown by the Indian bank as automatically equal to the final foreign tax credit.
7. India–Australia Treaty: Why the 15% Interest Rate Matters
The India–Australia tax treaty generally permits India to tax Indian-source interest paid to an Australian resident.
Where the Australian resident is beneficially entitled to the interest and the treaty conditions are satisfied, India’s source-country tax is generally limited to 15% of the gross amount.
That can be materially lower than India’s domestic NRO withholding.
💡 Real example
gross NRO interest: ₹500,000; domestic withholding initially higher than 15%; treaty entitlement: potentially 15% of gross interest, subject to eligibility and documentation.
The excess withholding issue is then an India tax/refund problem.
The Australian FITO analysis should be based on qualifying foreign income tax, not merely the largest amount withheld.
Keep tax-residency and treaty documentation ready before interest is paid where practical.
8. FITO: Australia’s Foreign Tax Credit for Assessable Interest
Australia uses the Foreign Income Tax Offset.
ATO guidance says FITO can generally be available where:
- foreign income tax has been paid; and
- the related amount is included in Australian assessable income.
For ordinary Australian residents, that can apply to NRO interest taxed in both India and Australia.
The workflow is:
- determine gross Indian interest;
- determine Indian tax properly payable;
- convert the assessable interest into AUD;
- convert qualifying foreign tax into AUD; and
- claim FITO subject to the Australian limit.
If the total FITO claimed for the year is AUD1,000 or less, the taxpayer generally does not need to calculate the formal FITO limit.
Above AUD1,000, the limit calculation generally applies.
FITO is non-refundable and does not simply turn every rupee of Indian TDS into an Australian refund.
9. Term Deposits: Australia Usually Taxes When Interest Is Credited or Received
This timing rule is particularly useful for cumulative NRE and FCNR deposits.
ATO guidance for individuals says interest is generally declared in the year it is credited or received.
For a term deposit, that usually means the year the investment matures if the contract only credits the interest at maturity.
💡 Real example
A three-year cumulative FCNR deposit begins in 2026 and pays all interest at maturity in 2029.
If the interest is not credited earlier, ATO’s ordinary individual term-deposit guidance generally points to declaring it when credited or received—often in 2029.
If the bank credits interest annually or periodically, those credited amounts can be reportable in the relevant earlier years.
The deposit contract therefore matters.
Keep:
deposit opening advice; interest-credit frequency; maturity statement; and annual account statements.
10. Savings Interest and Periodic FD Credits Are Simpler
NRE and NRO savings accounts usually credit interest periodically.
An ordinary Australian resident generally includes the interest in the Australian income year in which it is credited or received.
The same principle can apply where a fixed deposit credits interest monthly, quarterly or annually.
For each credit, preserve:
- date;
- INR or foreign-currency amount;
- AUD conversion;
- India tax withheld; and
- account statement.
A year-end interest certificate is useful, but it should reconcile to the actual credit pattern.
11. Joint Indian Accounts Are Not Always Automatically 50/50
ATO guidance generally assumes income from jointly held assets is divided equally between the owners.
But that assumption can be displaced if the taxpayers can show they own the asset in unequal proportions.
That matters for Indian family accounts.
If an Australian resident is a joint holder merely for convenience but did not beneficially contribute half the funds, the correct Australian interest allocation may require evidence of actual ownership.
Keep:
- contribution records;
- source of principal;
- account-opening documents;
- ownership arrangements; and
- family transfer evidence.
Do not choose 50/50 simply because two names appear on the bank statement.
12. Convert Both Interest and Foreign Tax Into AUD
Australia’s return is prepared in Australian dollars.
ATO guidance requires foreign income and foreign tax offsets to be converted into AUD.
Depending on the type of amount and circumstances, a specific prevailing exchange rate or an appropriate average rate may be used under ATO rules.
For an Indian-account worksheet, keep:
| Date / period | Account | Foreign interest | AUD rate | AUD interest | Indian tax |
|---|---|---|---|---|---|
| Quarterly | NRE savings | INR | Recorded rate | AUD | Usually nil if exempt |
| Maturity | NRO FD | INR | Recorded rate | AUD | Record final Indian tax |
| Maturity | FCNR(B) | USD/GBP/etc. | Recorded rate | AUD | Usually nil if exempt |
Use a consistent method and retain the evidence.
The Australian amount is what matters on the return, not the rupee number by itself.
13. Repatriation Is a Banking Event, Not the Tax Trigger
An Australian resident often asks:
“Do I pay Australian tax only when I transfer the interest to Australia?”
Generally, no.
For an ordinary Australian resident, tax follows when the interest is derived under the Australian rules.
The cash can remain in India.
A later wire to Australia is a separate banking event.
On the Indian side:
- NRE and FCNR(B) balances are generally repatriable;
- NRO current income can generally be remitted subject to the applicable rules and tax compliance; and
- other eligible NRO balances can use the relevant remittance framework.
RegalTicker’s NRI Repatriation from India guide covers the Indian banking route.
The useful record trail is:
deposit → interest credit/maturity → India tax → Australia tax/FITO → remittance
Long-lived records matter here too. RegalTicker’s Demerger Cost Basis Calculator is a useful reminder that future tax work depends on evidence created long before money is moved.
Frequently asked questions
Is NRE interest taxable in Australia?
For an Australian resident who is not a temporary resident, foreign bank interest generally forms part of worldwide assessable income. Qualifying temporary residents can generally exclude most foreign investment income.
Is NRE interest still tax-free in India?
Current Indian rules continue the NRE interest exemption where the FEMA-linked eligibility conditions are satisfied.
Is FCNR interest taxable in Australia?
An ordinary Australian resident generally reports foreign interest in AUD even where India exempts qualifying FCNR(B) interest. Temporary-resident treatment can be different.
Is NRO interest taxable in both India and Australia?
NRO interest is generally taxable in India. An ordinary Australian resident can also be taxed in Australia on the same interest, with FITO potentially relieving qualifying double taxation.
What is India’s domestic tax treatment of NRO interest?
Current official guidance describes NRO interest as taxable at 30% plus applicable surcharge and cess for non-residents.
What is the India–Australia treaty rate on interest?
The treaty generally limits qualifying Indian source-country tax on interest to 15% of gross interest when the Australian resident is beneficially entitled and the treaty conditions are met.
Can I claim the whole Indian TDS as FITO?
Not automatically. FITO depends on qualifying foreign income tax paid on income included in Australian assessable income. Excess Indian withholding can need to be recovered in India.
What happens if my FITO claim is more than AUD1,000?
ATO guidance generally requires the foreign income tax offset limit calculation when the total claim exceeds AUD1,000.
When is interest on a cumulative Indian FD taxed in Australia?
ATO guidance generally says individuals declare term-deposit interest when it is credited or received. If a cumulative deposit only credits interest at maturity, that will usually point to the maturity year.
What if my Indian FD credits interest every quarter?
An ordinary Australian resident generally reports the credited interest in the relevant Australian income year, subject to the normal tax rules.
How do temporary residents treat Indian bank interest?
A qualifying Australian temporary resident generally does not declare most foreign investment income, which can include ordinary foreign bank interest.
Does a temporary visa automatically give the foreign-income exemption?
No. The person must satisfy the statutory temporary-resident conditions. Visa status alone does not settle the Australian tax result.
How do joint NRE/NRO accounts work in Australia?
ATO generally assumes jointly held income is divided equally unless evidence shows unequal beneficial ownership.
Is interest taxed only when I transfer it to Australia?
No. For an ordinary Australian resident, tax follows the interest derivation rules, not the later remittance date.
Verify through official sources
Official references
- Australian Taxation Office — Foreign and Temporary Resident Income — Worldwide-income rule and temporary-resident foreign-income treatment.
- Australian Taxation Office — How to Work Out Your Tax Residency — Australian residency and temporary-resident treatment of foreign income.
- Australian Taxation Office — Interest Income and Term Deposits — Offshore interest, joint ownership and timing of term-deposit interest.
- Australian Taxation Office — Foreign Income Tax Offset — FITO eligibility and offset-limit framework.
- Australian Taxation Office — Foreign Income Toolkit — AUD conversion and AUD1,000 FITO-limit guidance.
- Income Tax Department, India — Filing of ITR for Non-Residents — NRE/FCNR exemption and NRO interest taxation.
- Income Tax Department, India — Income-tax Act 2025 Transition FAQ — Confirmation that the NRE interest exemption continues and remains linked to FEMA status.
- Income Tax Department, India — DTAA Withholding Rates — India–Australia 15% treaty rate for qualifying interest.
- Reserve Bank of India — Accounts in India by Non-Residents — NRE/NRO/FCNR account operation and repatriability.
Final takeaway
In Australia, Status Comes Before the Account Label
For an Australia-based NRI, the clean workflow is:
work out Australian status → identify NRE/NRO/FCNR → determine when interest is credited or received → apply India tax → apply treaty relief → convert to AUD → claim FITO where available → repatriate separately.
The biggest mistake is assuming “tax-free in India” means “tax-free in Australia.”
The second biggest mistake is forgetting that a qualifying temporary resident can have a completely different Australian result.
Educational disclaimer: This guide is for investor education and general Australia–India tax awareness. It is not individual Australian or Indian tax, treaty, FEMA, legal or banking advice. Australian residency, temporary-resident status, interest timing, treaty entitlement, FITO, Indian withholding and repatriation depend on the account, deposit contract, ownership and tax year.