Australia Does Not Tax Every Indian Investor the Same Way
An Indian professional moving to Sydney or Melbourne can keep investing in India. The hard part is not opening a Demat account or choosing a mutual fund.
The real question is what Australia considers you to be for tax purposes.
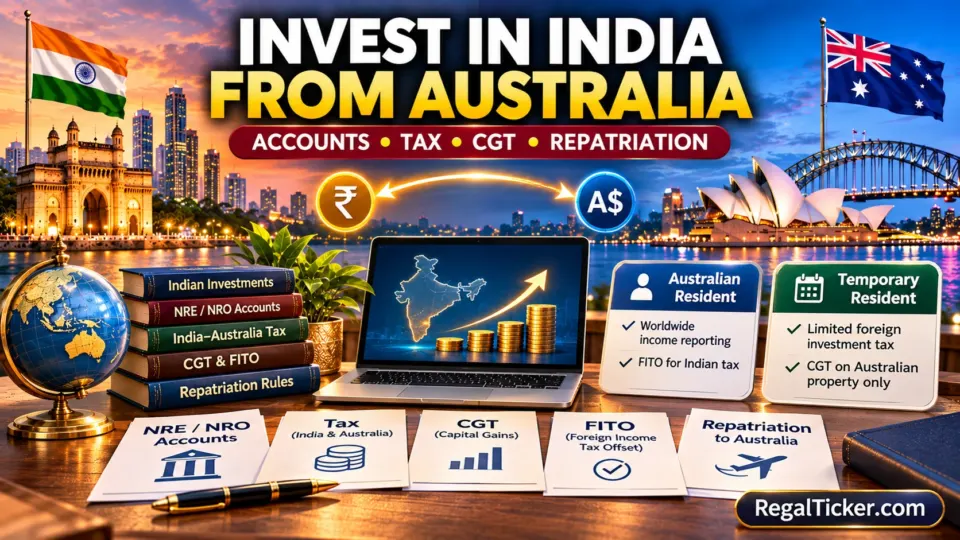
A person can be an Australian resident for tax purposes and still qualify as a temporary resident under a separate set of rules. That distinction can completely change how Indian dividends, interest, rent and capital gains are treated.
An ordinary Australian tax resident generally reports worldwide income. A qualifying temporary resident can be exempt from Australian tax on most foreign investment income and on capital gains from assets that are not taxable Australian property.
That means two Indian investors living in the same Australian city can have very different tax outcomes from the same Indian portfolio.
India still controls the NRI banking, FEMA, investment and repatriation side. Australia separately controls residency, foreign-income reporting, capital-gains treatment, foreign tax offsets and Australian-dollar conversion.
So the right first step is not “Which Indian stock should I buy?”
It is:
What is my Australian tax status, and when did that status begin?
⚡ Quick answer
Can an NRI Living in Australia Invest in India?
Yes. Eligible NRIs and OCIs living in Australia can generally invest in Indian shares, mutual funds, ETFs, deposits, bonds, NPS and other permitted assets through the applicable NRE, NRO and other FEMA-compliant routes. For Australian tax, the result depends heavily on status. An Australian tax resident who is not a temporary resident generally reports worldwide Indian income and gains. A qualifying temporary resident generally does not declare most foreign investment income and is generally subject to Australian CGT only on taxable Australian property. When a person becomes an Australian resident other than a temporary resident—or later ceases temporary-resident status while remaining Australian resident—certain foreign CGT assets can receive a market-value starting cost at that time.
Key takeaways
Australian tax residency and Australian temporary-resident status are separate concepts.
An individual can be an Australian resident for tax purposes and still qualify as a temporary resident.
Ordinary Australian tax residents generally report worldwide income, including Indian investment income and overseas capital gains.
Qualifying temporary residents generally do not report most foreign investment income and are generally subject to CGT only on taxable Australian property.
A temporary visa by itself does not settle the tax answer; the statutory temporary-resident conditions must be met.
When an individual becomes an Australian resident other than a temporary resident, certain foreign CGT assets are generally treated as acquired at market value at that time.
If a temporary resident later ceases to be temporary while remaining Australian resident, relevant non-Australian CGT assets can generally receive a market-value cost reset at that later date.
NRE/NRO/FCNR account labels determine the Indian banking route, not the Australian tax treatment.
Indian tax paid on income also assessable in Australia can potentially support a Foreign Income Tax Offset (FITO).
FITO is generally limited to qualifying foreign tax and can be restricted where India taxed above an applicable treaty ceiling.
India–Australia treaty rates generally cap Indian tax on qualifying dividends and interest at 15% of gross income for a beneficially entitled Australian resident.
Foreign income, deductions and foreign tax reported in Australia must be converted into Australian dollars.
Repatriation to Australia is a banking step; the tax event usually occurs when the income is earned or the asset is sold.
Keep arrival-date valuations even if you initially qualify as a temporary resident; the later end of temporary-resident status can make market value relevant.
Build the Australia portfolio only after the residency and repatriation framework is clear.
1. Start With Australian Tax Residency — Then Check Temporary-Resident Status
Australian tax residency does not depend only on citizenship, permanent residence or the label on a visa.
ATO guidance applies residency tests based on the person’s actual circumstances.
That creates three broad possibilities for an Indian investor:
- Australian resident for tax purposes and not a temporary resident.
- Australian resident for tax purposes who also qualifies as a temporary resident.
- Foreign resident for Australian tax purposes.
The second category is the one many cross-border articles miss.
ATO guidance says temporary-resident status generally requires the person to hold a temporary visa and neither the person nor their spouse to be an Australian resident within the meaning used by the Social Security Act framework.
That can produce a surprising result:
Australian tax resident does not always mean worldwide Indian investment income is taxable in Australia.
Before touching the portfolio, document the status used for the Australian return.
2. Ordinary Australian Residents Generally Report Worldwide Indian Income
For an Australian resident who is not a temporary resident, the broad rule is straightforward.
ATO guidance says Australian residents generally declare income earned anywhere in the world.
For an India-linked investor, that can include:
- NRE/NRO/FCNR interest;
- Indian dividends;
- mutual-fund distributions;
- rental income;
- pension or annuity income;
- business/investment income; and
- capital gains on overseas assets.
The money does not have to be remitted to Australia first.
If Indian interest remains in an Indian account, that does not by itself keep it outside the Australian return.
The same principle applies to rent, dividends and investment gains.
This is why RegalTicker’s NRE vs NRO vs PIS guide should be read as an Indian banking guide—not as an Australian tax classification.
3. Temporary Residents Can Have a Very Different Result
This is the defining Australia-specific feature of the cluster.
ATO guidance says a qualifying temporary resident generally declares Australian income and certain employment/service income, but most other foreign income does not need to be declared.
Temporary residents are also generally subject to Australian CGT only on taxable Australian property.
For an Indian investment portfolio, that can be significant.
Indian shares, Indian mutual funds and many other ordinary foreign investment assets are generally not taxable Australian property.
So a temporary resident can have a materially lighter Australian tax burden on a foreign investment portfolio than an ordinary Australian resident.
But do not reduce the rule to:
“temporary visa = no Australian tax on India.”
The person must actually satisfy the temporary-resident rules, and employment/service income can follow separate rules.
Investor note
Recheck the Status Every Year
Temporary-resident treatment can disappear when personal or immigration circumstances change. A portfolio that was outside Australian tax one year can become relevant later without any sale taking place.
4. Arrival Value Can Become the Australian CGT Starting Point
Australia has an important market-value rule for people entering the Australian tax system.
When a person becomes an Australian resident for tax purposes and is not also a temporary resident, the ATO generally treats certain CGT assets as acquired at market value at that time.
For an investor arriving with Indian shares, mutual funds, investment property, ETFs or other foreign CGT assets, that can establish a new Australian cost base.
💡 Real example
Simple example
An investor bought Indian shares years ago for the equivalent of AUD20,000.
When the person becomes an Australian resident who is not a temporary resident, the shares are worth AUD48,000.
Australia can generally treat the relevant shares as acquired at around AUD48,000 at that point.
India can still use the historical Indian acquisition record for its own gain calculation.
That means the same future sale can produce two different gains.
Preserve the market value and AUD conversion on the residency date.
5. Temporary Residents Can Get the Market-Value Reset Later
Someone who first qualifies as an Australian temporary resident can have a different timing point.
ATO guidance says if the person later ceases to be a temporary resident but remains an Australian resident, relevant CGT assets that are not taxable Australian property are generally treated as acquired at market value when temporary-resident status ends.
This is one of the strongest planning points for India-to-Australia investors.
💡 Real example
An Indian professional moves to Australia in 2026 on a temporary visa and qualifies as an Australian temporary resident.
Indian shares continue to appreciate while that status applies.
In 2029 the person ceases to qualify as a temporary resident but remains an Australian tax resident.
For relevant foreign CGT assets, the Australian market-value starting point can arise in 2029 rather than 2026.
That date should be documented just as carefully as the original arrival date.
6. Fix the Indian NRI Banking Structure
Australia’s tax rules do not replace India’s FEMA rules.
Once the person becomes non-resident under the applicable Indian foreign-exchange framework, resident Indian accounts should be updated appropriately.
The main banking routes remain:
- NRE for eligible foreign earnings and repatriable funds;
- NRO for Indian-source receipts and other permitted rupee balances; and
- FCNR(B) for qualifying foreign-currency deposits.
RBI guidance confirms that NRE balances are repatriable, while NRO balances are generally non-repatriable except for current income and the applicable USD1 million annual facility for eligible NRIs/PIOs.
For an Australian investor, the useful rule is:
bank-account label controls the India money route; Australian status controls the Australian tax result.
7. What Can an Australia-Based NRI Invest In?
Indian rules give eligible NRIs and OCIs broad access to Indian investments through repatriable and non-repatriable routes.
Listed Indian shares
NRIs/OCIs can invest in listed Indian equity through the permitted account and investment framework.
Mutual funds
Indian mutual funds can be available to Australia-based NRIs, subject to fund-house, KYC and platform rules.
Use RegalTicker’s NRI Mutual Fund Investing in India guide for the Indian execution side.
Deposits
NRE, NRO and FCNR(B) deposits remain common NRI products.
Bonds, REITs, InvITs and other instruments
Other permitted Indian securities and investment vehicles can also be available under the applicable rules.
The broad product map is covered in RegalTicker’s NRI Investment Options in India.
The Australia-specific question is not merely whether the asset is permitted in India.
It is whether the Australian tax status makes the income or gain assessable.
8. Indian Tax and Australian Tax Can Apply to the Same Income
For an ordinary Australian resident, India can still tax Indian-source income under Indian law and the India–Australia tax treaty.
The treaty generally allows India to tax qualifying dividends and interest but caps the source-country tax at 15% of the gross amount when the treaty conditions and beneficial-entitlement requirements are satisfied.
India can also tax gains and rental income under the applicable domestic and treaty provisions.
Australia then applies its own rules to the income when it is assessable in Australia.
That is where the Foreign Income Tax Offset becomes relevant.
9. Foreign Income Tax Offset: Australia’s Double-Tax Relief Mechanism
ATO’s FITO rules are designed to relieve double taxation where foreign tax was paid on an amount that is also included in Australian assessable income.
The practical sequence is:
- work out the Indian income under Indian rules;
- determine the Indian tax correctly payable;
- work out the Australian amount under Australian rules;
- convert the relevant amounts to AUD; and
- claim the eligible FITO subject to the Australian offset limit.
One important ATO point is easy to miss:
If a treaty limits India to a lower source-country tax rate but India initially withholds more, the excess generally does not automatically become a larger Australian FITO.
The taxpayer may need to recover the excess from India.
That means TDS deducted and foreign tax eligible for FITO are not always the same number.
10. Convert the Australian Tax Record Into AUD
ATO requires foreign income, deductions and foreign tax to be converted into Australian dollars.
Depending on the item, an appropriate transaction-date or average exchange rate can apply under the ATO conversion rules.
For an Indian portfolio, keep a record showing:
| Item | Foreign amount | Date / period | AUD rate | AUD amount |
|---|---|---|---|---|
| Bank interest | INR | Credit/accrual period | Recorded rate | AUD |
| Dividend | INR | Payment date | Recorded rate | AUD |
| Fund distribution | INR | Distribution date | Recorded rate | AUD |
| Asset purchase | INR | Acquisition date | Recorded rate | AUD |
| Asset sale | INR | Disposal date | Recorded rate | AUD |
| India tax | INR | Tax payment/withholding | Recorded rate | AUD |
The Indian broker’s rupee gain is evidence.
It is not automatically the Australian gain.
11. Repatriation Is Separate From Australian Tax
A common misunderstanding is:
“I will pay Australian tax when I finally bring the money over.”
For an ordinary Australian resident, that is generally the wrong timing concept.
The Australian tax issue can arise when interest is earned, a dividend is received, rent is derived or a CGT event occurs.
The later transfer to Australia is a separate banking event.
On the Indian side, NRE and FCNR funds are generally repatriable, while NRO current income and eligible capital balances use their own remittance routes.
RegalTicker’s NRI Repatriation from India guide explains those Indian rules.
The useful record trail is:
investment → income/gain → India tax → Australian tax/FITO → remittance
12. A Better Setup for Someone Moving From India to Australia
Consider Neha, who moves from Bengaluru to Melbourne.
She owns Indian shares, two mutual funds, an NRE deposit, an old NRO account and a rented apartment.
Before she decides how Australia taxes any of them, she should answer:
Australian status
- When did Australian tax residency begin?
- Does she also qualify as a temporary resident?
- If yes, when might that temporary-resident status end?
India structure
- Have resident accounts been redesignated?
- Which funds are repatriable?
- Are KYC/FATCA/CRS details current?
Valuation
If she is not a temporary resident:
- record market value of relevant foreign CGT assets when Australian residency begins.
If she is a temporary resident:
- record current values anyway;
- then obtain a fresh market-value file if temporary-resident status later ends while she remains Australian resident.
Tax file
- Indian interest/dividend/rent statements;
- Indian TDS/tax;
- AUD conversion;
- FITO support; and
- later sale records.
This setup is much easier than reconstructing three years of history after the first major sale.
13. Australia–India Investment Record Checklist
Keep one permanent cross-border folder.
| Record | Why it matters |
|---|---|
| Australian tax residency date | Determines Australian resident period |
| Temporary-resident analysis | Can change foreign-income and CGT treatment |
| Date temporary status ends | Can trigger market-value acquisition rule |
| Market values at relevant status date | Australian CGT cost |
| INR/AUD exchange-rate evidence | Australian reporting |
| NRE/NRO/FCNR statements | India banking and repatriation |
| Demat/broker statements | Indian share history |
| Mutual-fund folios | Purchases, distributions and redemptions |
| Property records | Rent and future CGT |
| Indian TDS/tax returns | FITO support |
| Treaty residency documents | India treaty claims |
| Remittance records | Source-of-funds trail |
Long-term cross-border investing is largely a recordkeeping exercise disguised as an investing exercise.
RegalTicker’s Demerger Cost Basis Calculator is a useful reminder that future tax outcomes often depend on cost records created years earlier.
Frequently asked questions
Can an NRI living in Australia invest in Indian stocks?
Yes, eligible NRIs/OCIs can generally invest through permitted Indian banking, Demat and investment routes. Australian tax treatment depends on the investor’s Australian residency and temporary-resident status.
Does Australia tax Indian investment income?
An Australian resident who is not a temporary resident generally reports worldwide income, including Indian investment income. Qualifying temporary residents can have exemptions for most foreign investment income.
Can I be an Australian tax resident and still be a temporary resident?
Yes. ATO guidance treats tax residency and temporary-resident status as separate concepts.
Does a temporary visa automatically make me a temporary resident for tax?
No. The statutory temporary-resident conditions must be satisfied, including the visa and Social Security Act-related requirements.
Does a temporary resident pay Australian CGT on Indian shares?
Temporary residents are generally subject to CGT only on taxable Australian property. Ordinary Indian shares are generally not taxable Australian property, subject to the detailed rules.
What happens to my Indian shares when I become an ordinary Australian resident?
For relevant CGT assets, Australia generally treats the investor as acquiring them at market value when Australian residency begins if the person is not also a temporary resident.
What if I first qualify as a temporary resident?
If temporary-resident status later ends while you remain Australian resident, relevant non-Australian CGT assets can generally receive a market-value starting cost at that later date.
Is NRE interest tax-free in Australia?
The Indian NRE exemption does not automatically control Australian tax. An ordinary Australian resident generally reports foreign interest, while a qualifying temporary resident can have different treatment.
Can Indian tax be claimed in Australia?
Qualifying foreign income tax paid on income also assessable in Australia can potentially support a Foreign Income Tax Offset, subject to the Australian rules and offset limit.
What is the India–Australia treaty rate on interest and dividends?
The treaty generally caps Indian source-country tax on qualifying interest and dividends at 15% of the gross amount when the beneficial-owner and treaty conditions are satisfied.
Do I report Indian investments in Australian dollars?
Yes. ATO rules require foreign income, deductions and foreign tax to be translated into AUD before reporting.
Is transferring Indian money to Australia a new tax event?
The transfer itself is generally separate from the income or CGT event. Tax usually follows the underlying interest, rent, dividend or disposal rather than the later remittance.
Can I keep investing in Indian mutual funds after moving to Australia?
Indian rules generally permit NRI mutual-fund investing, subject to the fund house, KYC, funding and platform rules. Australian tax treatment then depends on the investor’s status.
Verify through official sources
Official references
- Australian Taxation Office — Australian Resident Foreign and Worldwide Income — Worldwide-income rule for Australian residents.
- Australian Taxation Office — Residency for Tax Purposes — Australian tax residency, temporary-resident treatment and foreign-income consequences.
- Australian Taxation Office — How Changing Residency Affects CGT — Market-value acquisition on becoming resident and when temporary-resident status ends.
- Australian Taxation Office — Foreign Income Tax Offset — FITO conditions, foreign-tax definition and treaty-rate limitation.
- Australian Taxation Office — Foreign Exchange Rates — Conversion of foreign income, deductions and tax into Australian dollars.
- Income Tax Department, India — India–Australia Synthesised Tax Treaty — Current treaty text including dividend and interest source-country limits.
- Income Tax Department, India — DTAA Rates — Current India treaty-rate comparison for Australian residents.
- Reserve Bank of India — Accounts in India by Non-Residents — NRE/NRO/FCNR account operation, taxability labels and repatriability.
- Reserve Bank of India — Foreign Investment Master Direction — NRI/OCI repatriable and non-repatriable investment framework.
Final takeaway
In Australia, Your Tax Status Comes Before Your Investment List
For an India-linked investor in Australia, the clean sequence is:
work out Australian tax residency → test temporary-resident status → document the relevant market-value date → fix NRE/NRO banking → choose Indian investments → calculate India tax → calculate Australian tax where applicable → claim FITO → repatriate through the correct route.
The biggest mistake is assuming every Australian resident is taxed the same way on Indian investments.
Australia’s temporary-resident rules can change the answer before the portfolio itself changes at all.
Educational disclaimer: This guide is for investor education and general Australia–India tax awareness. It is not individual Australian or Indian tax, immigration, FEMA, legal or investment advice. Australian tax residency, temporary-resident status, CGT cost base, FITO, treaty relief, Indian NRI status and repatriation depend on the investor’s facts and the rules for the relevant year.