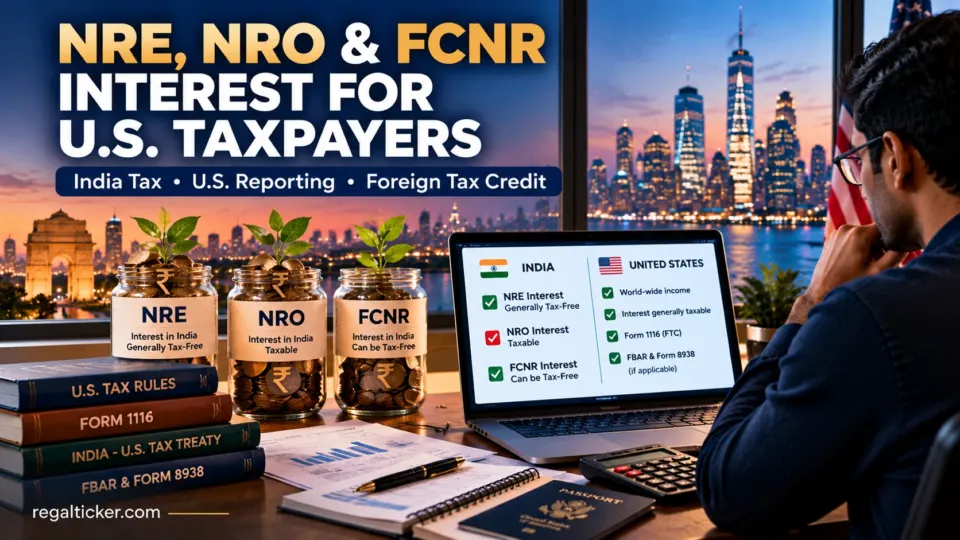
The Indian account label does not decide the U.S. tax result
An NRE account can be tax-exempt in India and still produce taxable interest on a U.S. return. An NRO account can be taxed in India and then require a separate U.S. foreign-tax-credit calculation. An FCNR deposit can preserve foreign-currency exposure and receive favourable Indian tax treatment, yet a U.S. taxpayer still has to ask when the interest was earned, how it is translated into dollars and whether any separate foreign-account reporting applies.
That mismatch is the real issue. The words NRE, NRO and FCNR describe Indian banking arrangements. They do not override the U.S. rule that citizens and resident aliens generally report worldwide income.
If you need the broader country framework first, begin with RegalTicker’s USA investing guide. For the Indian account mechanics—funding, repatriation and the role of PIS terminology—use the NRE vs NRO vs PIS guide.
⚡ Quick answer
Are NRE, NRO and FCNR interest taxable in the United States?
For a U.S. citizen or U.S. resident alien, interest from an Indian bank account is generally part of worldwide income and must be considered for U.S. federal income-tax reporting even when India exempts the interest. Qualifying NRE and FCNR interest can receive Indian tax exemption under the applicable conditions, while NRO interest is generally taxable in India. If Indian income tax is actually paid or withheld on NRO interest, a U.S. foreign tax credit may be available subject to the Form 1116 rules, source rules, treaty limits and the taxpayer’s facts.
Key takeaways
“Tax-free in India” does not mean “tax-free in the United States.”
The NRE exemption in India remains tied to the required FEMA/RBI status and account conditions.
Current Indian guidance continues to treat qualifying FCNR interest favourably while NRO interest is taxable.
U.S. citizens and resident aliens generally include foreign bank interest in worldwide income.
Foreign bank interest is investment income, not foreign earned income for the foreign earned income exclusion.
Indian tax withheld from NRO interest is not automatically a dollar-for-dollar U.S. credit.
Interest is generally passive-category income for the U.S. foreign tax credit.
Currency conversion, bank certificates and tax-withholding records should be preserved every year.
1. Why U.S. taxpayers need a separate NRE, NRO and FCNR review
The Indian account comparison is only half of the job for a person living in America.
An NRE account answers questions about eligible overseas funds, permitted credits and repatriation. An NRO account is commonly used for Indian receipts and rupee balances that do not belong in the NRE framework. An FCNR(B) deposit lets an eligible non-resident hold a term deposit in a permitted foreign currency.
Those are Indian banking questions. The U.S. tax question starts elsewhere: Who is the taxpayer under U.S. law, and what income must that person report?
That distinction matters because the United States generally taxes citizens and resident aliens on worldwide income. A bank statement showing “NRE interest — exempt” is therefore not a complete U.S. tax analysis. It proves something about Indian treatment, not about U.S. treatment.
The same separation helps with records. Keep three columns in your annual file:
| Question | What you are trying to establish |
|---|---|
| Indian account status | Was the account maintained under the correct NRE, NRO or FCNR framework? |
| Indian income-tax treatment | Was the interest exempt, taxable, or subject to withholding in India? |
| U.S. treatment | What amount must be reported in U.S. dollars, and does any foreign tax qualify for credit? |
This simple separation prevents one of the most common cross-border mistakes: assuming that a bank’s Indian tax label answers the U.S. question.
2. Start with U.S. tax residency, not the word “NRI”
“NRI” is an Indian-law and banking concept. It is not a U.S. federal income-tax status.
A U.S. citizen remains within the U.S. worldwide-income system even while living abroad. A non-citizen can become a U.S. resident alien through rules such as the green-card test or substantial-presence test. A person who moves during the year can have a more complicated residency-starting-date or dual-status problem.
That means the first question is not:
> Is my account NRE or NRO?
It is:
> For which part of this year am I treated as a U.S. taxpayer on worldwide income?
Someone who moves from India to the United States in the middle of the year should not casually apply a full-year rule without checking the actual U.S. residency starting date. Likewise, a U.S. citizen cannot avoid U.S. reporting merely because the account is maintained in India.
On the Indian side, FEMA residence and Indian income-tax residence are separate tests. RegalTicker’s FEMA vs Income Tax Residency guide explains why the labels should not be collapsed into one status.
Investor note
Use four labels in your working papers
For cross-border bank interest, write down four separate labels: U.S. tax status, FEMA status, Indian income-tax status and bank-account type. If one of those changes during the year, record the date and supporting document rather than relying on memory at filing time.
3. How India treats NRE interest
The Income Tax Department has confirmed that the NRE-interest exemption was retained under the Income-tax Act, 2025.
The important detail is the condition behind the exemption. It continues to depend on the individual being a person resident outside India under FEMA, or otherwise being permitted by the RBI to maintain the account. In other words, the tax result is not permanently attached to the letters “NRE.”
This becomes especially important when somebody returns to India.
An account can continue to exist operationally for a short period while records are being updated, but that does not mean the old tax assumptions should be carried forward indefinitely. Once FEMA status changes, the bank/account redesignation and the tax treatment need to be reviewed together.
For that transition, use RegalTicker’s returning-to-India investment and tax checklist rather than treating a change of country as only a mailing-address update.
Example: India exempts the interest, the U.S. still asks for it
Assume a U.S. resident alien earns ₹180,000 of qualifying NRE interest during a year and the account continues to satisfy the Indian exemption conditions.
India may impose no income tax on that interest.
The U.S. analysis does not stop there. The taxpayer still needs to determine the reportable U.S.-dollar amount because the United States generally taxes residents on worldwide income.
There is also no Indian tax on this example to generate an Indian foreign tax credit.
That is the core point:
An Indian exemption can remove Indian tax without removing U.S. income.
4. How India treats FCNR interest
FCNR(B) is a foreign-currency term-deposit structure available under the RBI’s non-resident deposit framework. Unlike an NRE rupee deposit, the principal is maintained in an eligible foreign currency.
Current Income Tax Department guidance continues to identify qualifying FCNR interest as tax-exempt in India under the applicable non-resident conditions.
For a U.S. taxpayer, however, the basic worldwide-income issue remains. The fact that the deposit is in dollars, pounds or another permitted currency does not create a separate U.S. exemption.
A dollar-denominated FCNR deposit can make the U.S. record simpler because the interest itself may already be stated in U.S. dollars. A euro- or sterling-denominated FCNR deposit still requires U.S.-dollar reporting.
The account can also raise a separate currency question beyond the interest itself. This guide focuses on the bank-interest income and does not attempt to determine whether a particular foreign-currency transaction creates a separate U.S. currency gain or loss. That depends on the transaction and should be reviewed when material.
NRE and FCNR are similar in one important way
For many U.S. taxpayers, the practical tax pattern is:
| Account | India-side interest treatment | U.S. starting point |
|---|---|---|
| Qualifying NRE | Exempt in India when conditions are satisfied | Include the interest in worldwide-income analysis |
| Qualifying FCNR | Exempt in India when conditions are satisfied | Include the interest in worldwide-income analysis |
The U.S. taxpayer should therefore preserve the gross interest certificate, not only a bank statement showing that Indian tax was zero.
5. Why NRO interest is different
NRO interest is the account type most likely to create a two-country tax calculation.
The Income Tax Department’s non-resident guidance treats NRO interest as taxable in India. Banks also operate under the non-resident withholding framework, although the amount deducted at source should not automatically be assumed to equal the final Indian tax liability.
That creates a different record trail:
- determine the gross NRO interest;
- identify Indian tax actually withheld or ultimately payable;
- determine whether treaty relief changes the Indian rate;
- report the relevant interest in the United States;
- determine whether the Indian income tax qualifies for a U.S. foreign tax credit; and
- apply the U.S. credit limitation rather than simply subtracting the Indian tax from the U.S. bill.
The distinction between gross and net matters.
If the bank credits ₹70,000 after withholding tax from ₹100,000 of gross interest, the U.S. analysis does not begin with ₹70,000 simply because that is what arrived in the account. The gross income and the foreign tax are separate items.
The same principle matters when reconciling Form 26AS, AIS, a bank interest certificate and the actual account statement.
6. How the United States reports Indian bank interest
IRS guidance for U.S. residents says interest must be reported whether it is earned inside or outside the United States. Publication 54 also makes an important distinction: interest from a foreign bank account is investment income, not earned income from personal services.
That means the foreign earned income exclusion is not a shortcut for NRE, NRO or FCNR interest.
A person can work in the United States, receive salary there, keep an NRE fixed deposit in India and still have the Indian interest enter the U.S. return.
The practical annual workflow should begin with gross interest by account:
| Account | Currency | Gross interest | Indian tax | U.S.-dollar amount |
|---|---|---|---|---|
| NRE savings/term deposit | INR | Record from bank certificate | Usually nil if exemption applies | Convert under a consistent U.S. method |
| NRO savings/term deposit | INR | Record gross amount | Record withholding/final tax separately | Convert gross interest and tax separately |
| FCNR deposit | USD/GBP/EUR/etc. | Record from maturity/interest certificate | Usually nil if exemption applies | Convert if not already USD |
Do not use a remittance date as the income date merely because that is when money moved to America. Earning interest and transferring cash are different events.
If you later move the money out of India, RegalTicker’s NRI repatriation guide covers the Indian transfer route and documentary trail.
7. Foreign tax credit and Form 1116 for NRO interest
The U.S. foreign tax credit exists to reduce double taxation where qualifying foreign income tax is paid on foreign-source income that is also subject to U.S. tax. But the credit has conditions and limits.
IRS Publication 514 places interest within the passive category in the ordinary case.
For NRO interest, that means Indian income tax may potentially enter a passive-category Form 1116 calculation. Several things still need to be checked:
- Was the tax legally imposed on the taxpayer?
- Was it actually paid or accrued under the taxpayer’s chosen method?
- Does it qualify as an income tax under U.S. rules?
- Is the income treated as foreign-source for U.S. FTC purposes?
- Does a treaty rule affect the amount that should have been paid to India?
- Does the Form 1116 limitation allow the full amount in the current year?
A bank withholding amount is therefore evidence, not the final U.S. answer.
No Indian tax means no India tax credit
If qualifying NRE or FCNR interest is exempt in India, the taxpayer may still owe U.S. tax but normally has no Indian income tax on that interest to credit.
This is why “tax-free in India” can actually produce a larger visible U.S. tax cost than a reader initially expects.
It does not mean the Indian exemption is bad. It means the U.S. system is applying its own rules independently.
8. The India–U.S. treaty and interest
Article 11 of the India–U.S. income-tax treaty allows interest arising in one country and paid to a resident of the other country to be taxed in the residence country. It also allows source-country taxation, subject to treaty limits when the beneficial-owner conditions are met.
The treaty sets a 10% ceiling for a specific category of interest on loans granted by a bank or similar financial institution and a 15% ceiling for other interest.
For an ordinary individual holding a bank deposit, do not assume that the special 10% bank-loan category applies merely because a bank is involved. The lower category is framed around the lender being a bank or similar institution. Ordinary deposit interest generally needs to be tested under the “other interest” rule and the actual treaty facts.
India’s Income Tax Department also publishes a DTAA-versus-domestic-law rate table showing the U.S. treaty’s 10%/15% structure for interest.
Treaty eligibility is not merely a rate lookup. The taxpayer may need residence evidence and the documentation required for an Indian treaty claim. RegalTicker’s DTAA, TRC and Form 41 guide explains that documentation layer.
Investor note
Treaty rate and foreign tax credit are two different questions
First ask what India was entitled to tax under domestic law and the treaty. Then ask what U.S. foreign-tax-credit rules allow. Paying an unnecessarily high amount in India does not guarantee that the entire excess becomes a usable U.S. credit.
9. Convert the interest and foreign tax into U.S. dollars carefully
A U.S. federal return is prepared in U.S. dollars.
IRS currency guidance says foreign-currency income generally must be translated using the exchange rate that applies when the amount is received, paid or accrued, depending on the item and method. The IRS does not publish one compulsory exchange rate for every taxpayer; it generally accepts a posted rate used consistently.
For income received evenly through the year, an annual average rate can be appropriate in some circumstances. A single material transaction may call for the rate applicable to that date.
Foreign tax conversion can be different. Form 1116 instructions generally use the rate when the tax was paid or withheld for taxes claimed on the paid basis, while accrued taxes can have separate average-rate rules subject to conditions.
That is why a clean workbook should keep separate fields for:
- interest amount in the account currency;
- date credited or period to which it relates;
- exchange rate source;
- U.S.-dollar income amount;
- Indian tax withheld;
- withholding/payment date;
- exchange rate used for the foreign tax; and
- U.S.-dollar foreign-tax amount.
Do not force the same exchange rate onto every column merely to make the spreadsheet neat.
10. Joint accounts, deposits and renewals need their own records
A joint Indian bank account can create two different questions:
Who owns the income? and Who has reportable authority or a financial interest in the account?
Those questions should not be answered from the first name on the statement alone.
For income tax, preserve the funding trail, ownership arrangement and actual entitlement to the interest. For foreign-account reporting, separate rules can apply based on financial interest or signature authority.
Similarly, a fixed deposit renewal is not a reason to lose the original trail. Keep:
- original deposit advice;
- renewal instruction;
- maturity amount;
- interest certificate;
- tax deduction certificate where relevant;
- account designation;
- residency/KYC updates; and
- source of the original funds.
A five-year archive is far easier to understand when each renewal is linked to the previous deposit rather than appearing as a fresh unexplained balance.
11. Moving to the United States with existing Indian deposits
A common problem is that the account was opened before the person became a U.S. taxpayer.
The U.S. tax issue does not necessarily begin when the money is remitted to America. It begins when the person enters the relevant U.S. tax regime and has reportable income under that regime.
Someone who relocates in July with an existing NRE fixed deposit should therefore preserve:
- the U.S. residency starting date;
- deposit opening date;
- interest accrual/credit details;
- Indian tax status for the relevant period;
- FEMA status;
- bank redesignation records if any; and
- the method used to determine the U.S.-reportable portion.
Do not guess a pro-rata answer if the deposit’s interest-crediting terms and the taxpayer’s U.S. status create a more specific result.
The same principle works in reverse when returning to India. The banking account, FEMA status and tax exemptions need to be reviewed at the time the residency facts change.
12. Build one annual cross-border interest file
The strongest practical habit is to create the file before tax-season pressure begins.
For each NRE, NRO and FCNR account, save:
- year-end and monthly statements;
- gross annual interest certificate;
- deposit opening and maturity advice;
- Indian withholding/tax certificates;
- AIS/Form 26AS reconciliation where relevant;
- proof of FEMA/NRI status where it affects an exemption;
- treaty residence documentation if a treaty rate was claimed;
- currency-conversion working;
- U.S. tax workpaper showing where the interest was reported; and
- any foreign-account reporting workpaper prepared for the same account.
This makes later amendments, bank corrections and residency transitions much easier.
The broader NRI stock-market guide can help organise the Indian investment side of the file. If a shareholding in that wider portfolio is affected by a demerger, the Demerger Cost Basis Calculator can preserve the allocation working separately from the bank-interest records.
13. Mistakes that create avoidable problems
The most expensive mistakes are often conceptual rather than mathematical.
Mistake 1: “NRE is tax-free, so I report nothing in the U.S.”
That confuses an Indian exemption with U.S. worldwide-income taxation.
Mistake 2: Reporting only the NRO amount that reached the account
If Indian tax was withheld, the net credit is not necessarily the gross income figure.
Mistake 3: Claiming every rupee withheld as a U.S. foreign tax credit
Form 1116 limitations, source rules, treaty limits and creditability rules can reduce the usable amount.
Mistake 4: Using one year-end exchange rate for everything
Income and foreign taxes can require different timing and conversion treatment.
Mistake 5: Keeping an NRE account after status changes without reviewing the exemption
The Indian exemption depends on the underlying FEMA/RBI conditions, not the account nickname alone.
Mistake 6: Treating remittance as the taxable event
Moving cash to the United States is not the same event as earning the bank interest.
Mistake 7: Mixing tax reporting with account reporting
Income-tax reporting, FBAR and Form 8938 are different systems. One filing does not automatically replace the others.
Final takeaway
Reconcile the account, the income and the tax separately
For a U.S. taxpayer, NRE, NRO and FCNR are not three versions of the same tax answer. Qualifying NRE and FCNR interest can be exempt in India while remaining part of U.S. worldwide income. NRO interest can create both Indian tax and U.S. tax, with treaty and foreign-tax-credit rules determining how much double taxation is actually relieved.
The cleanest workflow is to identify the account, verify the Indian treatment, record gross interest and Indian tax separately, translate the relevant amounts into dollars using a consistent method, and then complete the U.S. income and foreign-tax-credit analysis. That process is far safer than starting from the net balance visible in a banking app.
Frequently asked questions
Is NRE account interest taxable in the United States?
For a U.S. citizen or resident alien, NRE interest generally enters the U.S. worldwide-income analysis even when it is exempt in India. The exact U.S. filing result depends on the taxpayer’s status and facts.
Is FCNR interest taxable in the United States?
A qualifying FCNR deposit can receive favourable Indian tax treatment, but a U.S. taxpayer generally still has to consider the interest for U.S. federal income tax. If the deposit currency is not the U.S. dollar, currency translation is also required.
Is NRO account interest taxable in India?
Yes. Current Income Tax Department guidance treats NRO interest as taxable in India. Withholding, final tax and treaty relief should be reviewed separately rather than assuming the bank deduction is the final result.
Can I claim Indian tax on NRO interest on Form 1116?
Potentially. Interest is generally passive-category income for foreign-tax-credit purposes, but the tax must qualify and the Form 1116 limitation, source rules and treaty treatment still apply.
Does the India–U.S. treaty make NRE interest tax-free in America?
No. The Indian exemption does not itself create a U.S. exemption. The treaty allocates taxing rights and provides double-taxation mechanisms, but a U.S. citizen or resident alien remains subject to the U.S. worldwide-income framework unless a specific U.S. rule provides otherwise.
Should I report the gross NRO interest or only the amount credited after TDS?
The gross interest and the Indian tax withheld should be analysed separately. Using only the net bank credit can understate the income and obscure the foreign-tax-credit calculation.
Which exchange rate should I use for Indian interest on a U.S. return?
IRS guidance generally requires foreign-currency amounts to be translated into U.S. dollars using a rate appropriate to when the item is received, paid or accrued. Annual averages can be appropriate in some circumstances, while foreign taxes can have separate Form 1116 conversion rules.
Does reporting NRE or NRO interest on my U.S. tax return satisfy FBAR or Form 8938?
No. Income-tax reporting and foreign-account reporting are separate systems. A taxpayer can have an account-reporting obligation even when an account produces little or no taxable income.
Verify through official sources
Official references
- IRS — Taxation of U.S. Residents — U.S. resident aliens generally report worldwide income, including foreign interest.
- IRS — Publication 54 — U.S. citizens and resident aliens abroad; foreign bank interest is investment income rather than foreign earned income.
- IRS — Publication 514 — Foreign tax credit requirements, limitations and passive-category treatment of interest.
- IRS — Instructions for Form 1116 — Foreign tax credit procedure and foreign-currency conversion rules for taxes.
- IRS — Foreign Currency and Currency Exchange Rates — General U.S.-dollar translation rules and consistency guidance.
- IRS — India Income Tax Treaty — Article 11 interest limits and treaty framework for double taxation.
- IRS — India Treaty Technical Explanation — Explanation of treaty interest sourcing and operation.
- Income Tax Department — Non-Resident FAQs — Confirms retention of the NRE-interest exemption under the Income-tax Act, 2025 and its FEMA-status condition.
- Income Tax Department — Filing of ITR for Non-residents — Current department guidance identifying NRE/FCNR interest as exempt and NRO interest as taxable in India.
- Income Tax Department — DTAA vs Income-tax Act Rates — Official comparison of treaty and domestic rates, including the United States interest-rate structure.
- RBI — Accounts in India by Non-residents — RBI summary of NRE, NRO and FCNR account features, currencies, permitted credits and deposit structure.
- RBI — Foreign Exchange Management Deposit Regulations — RBI regulatory definitions and operating framework for NRE, NRO and FCNR accounts.
Educational disclaimer: This guide provides general investor education and was reviewed on October 23, 2026. It is not personalised U.S. or Indian tax, legal or investment advice. U.S. residency starting dates, treaty eligibility, Indian withholding, foreign tax credits, currency treatment and account-reporting obligations depend on the taxpayer’s facts and the rules in force for the relevant year.