The second rulebook starts in the United States
The Indian side of an NRI investment is often the easier half of the problem. You can learn what an NRE account does, open the right Demat account, complete KYC and buy an Indian share. The harder question for somebody living in the United States is what happens after that investment enters the U.S. tax system.
That extra layer changes the order in which it makes sense to plan. A U.S.-based NRI should not begin with “Which Indian fund should I buy?” The better first questions are whether the investor is a U.S. taxpayer, what kind of Indian asset is being bought, where the cash and securities will be held, and which U.S. reporting forms may be triggered. A direct Indian share, an Indian mutual fund and an NRE fixed deposit can sit in the same broad “India portfolio” while producing very different U.S. compliance work.
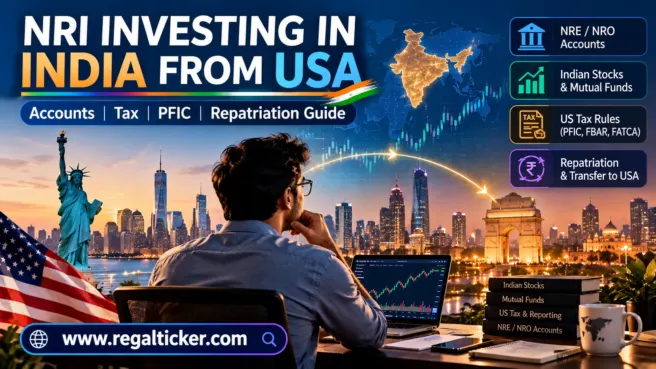
This guide is designed around that reality. It does not repeat every step of opening an NRI account or every Indian capital-gains rule. RegalTicker already has detailed guides for those jobs. Instead, the focus here is the junction between the two systems: Indian banking and investment rules on one side, and U.S. worldwide taxation, foreign-account reporting and PFIC rules on the other.
The most useful time to understand that junction is before the first transfer, not when a tax preparer discovers the account a year later.
⚡ Quick answer
What changes once U.S. tax rules enter the picture?
A U.S.-based NRI can invest in India, but a compliant India-side account setup does not finish the job. U.S. citizens and resident aliens are generally taxed on worldwide income; foreign accounts can trigger FBAR and Form 8938 reporting; foreign pooled investments can raise PFIC and Form 8621 questions; and Indian tax already paid may need to be coordinated through U.S. foreign-tax-credit rules. The practical sequence is to establish your tax status, classify the asset, choose the correct Indian account route, keep a clean record trail and understand the U.S. reporting consequences before committing serious money.
Key takeaways
NRI status in India and U.S. tax residency are separate tests; satisfying one does not settle the other.
A direct Indian share and an Indian mutual fund can create very different U.S. compliance work, especially when PFIC rules may apply.
FBAR uses an aggregate foreign-account threshold, while Form 8938 is a separate reporting regime with different rules and thresholds.
Indian tax paid can matter for U.S. foreign-tax-credit relief, but the two tax systems do not always match perfectly in timing or calculation.
Repatriation planning, tax reporting and recordkeeping should be designed before the investment grows, not reconstructed after a sale.
Investor note
Check the product before the purchase
For a U.S. taxpayer, the Indian product that looks simplest operationally can be the most awkward to report. Before buying a foreign pooled vehicle, ask specifically whether PFIC rules could apply and what records or elections would be needed. That check belongs before the first purchase, not at tax-filing time.
The first question is not what to buy — it is how the U.S. sees you
“NRI” is an Indian-law label. It does not tell you, by itself, how the United States taxes you.
For U.S. federal income-tax purposes, U.S. citizens and resident aliens are generally taxed on worldwide income. A non-citizen can become a U.S. resident alien under rules such as the green-card test or substantial-presence test. Once you fall within the U.S. worldwide-income system, an Indian dividend, interest payment or capital gain does not become invisible simply because the account, broker and company are all in India.
This is where people sometimes mix three separate ideas:
- your status under India’s foreign-exchange rules;
- your residential status under Indian income-tax law; and
- your status for U.S. federal tax purposes.
They can overlap, but they are not the same test. Our FEMA versus Indian income-tax residency guide explains the Indian distinction. For somebody now living in the U.S., a fourth layer is then added: whether U.S. tax law treats that person as a U.S. taxpayer for the year.
A practical example makes the point. An Indian citizen moves to Texas, updates the Indian bank relationship to NRI status and invests through a properly configured NRE-linked securities route. That may solve the India-side account problem. If the investor is also a U.S. tax resident, however, U.S. reporting does not disappear. The same Indian accounts and investments may need to be considered for the U.S. return and foreign-account disclosures.
This is why “my bank allowed the transaction” is not a tax conclusion.
Build the Indian account structure before sending serious money
The account architecture still matters. A U.S.-based NRI normally deals with some combination of an NRE account, an NRO account, a Demat account and a trading account. These are different pieces of the plumbing, not interchangeable labels.
An NRE account is generally the natural home for eligible foreign earnings remitted to India when repatriability is important. An NRO account is commonly used for Indian-source receipts and other rupee transactions. RBI guidance distinguishes the repatriability of the two: NRE balances are repatriable, while NRO balances are subject to restrictions, with eligible NRO remittances generally available up to USD 1 million per financial year subject to the applicable conditions and taxes.
For a deeper India-side setup, use the NRE vs NRO vs PIS comparison and the NRI Demat account guide. The point for a U.S. resident is not to memorize every route. It is to make sure the investment account, funding source and intended repatriation route agree with one another.
A clean setup also produces a cleaner record trail. If dollars are remitted into an eligible NRE route, converted to rupees, used to buy securities and later returned through the permitted channel, the investor has a chain of bank statements and contract notes that can be reconciled. Mixing old resident accounts, family transfers, Indian income, investment proceeds and overseas remittances in one place makes both countries harder to deal with.
The most useful habit is simple: decide which pool of money you are investing before you decide which product to buy.
Direct Indian shares and Indian mutual funds are not the same U.S. tax problem
From an Indian investing perspective, a listed share and an equity mutual fund can look like two ways to obtain equity exposure. From the U.S. tax perspective, that similarity can be misleading.
A direct holding in an Indian operating company is foreign stock. It can create foreign-asset reporting and tax questions, but it is not automatically a passive foreign investment company merely because the company is incorporated in India. PFIC status is determined under specific U.S. tests.
An Indian mutual fund deserves a more cautious review. The IRS defines a PFIC by reference to a foreign corporation’s income and assets: broadly, the foreign corporation can be a PFIC if at least 75% of its gross income is passive income or at least 50% of its assets produce, or are held to produce, passive income. Because foreign pooled investment vehicles can fall into that regime depending on their legal structure and facts, a U.S. taxpayer should check the PFIC position before buying—not after building a large holding.
That is deliberately different from saying “every Indian mutual fund is a PFIC.” The legal classification and the investor’s facts matter. But the possibility is serious enough that treating an Indian mutual-fund purchase as routine can be a costly assumption.
There is another layer as well. Some Indian fund houses or platforms may place operational restrictions on investors resident in the United States because of their own compliance policies. That is a distribution/onboarding issue. PFIC is a U.S. tax classification issue. They are related only in the sense that both can make the investment inconvenient; they should not be confused.
Our NRI mutual fund investing guide covers the India-side KYC, account and platform questions. A U.S.-based investor should add a U.S. tax review before treating that guide as the final decision.
Why PFIC can turn a simple fund purchase into a compliance project
PFIC is one of the reasons a U.S.-based investor should choose the investment vehicle before chasing returns.
Form 8621 is the central U.S. form associated with PFIC ownership. The rules cover several situations, including certain distributions, dispositions, elections and annual reporting. Depending on the facts, tax treatment can involve the default excess-distribution regime or elections such as qualified electing fund or mark-to-market treatment where the legal requirements are met.
The practical problem is not merely the existence of one more form. It is that the information needed to make an election or compute the tax may not line up neatly with the statements an Indian product normally provides to an Indian retail investor. A product can therefore be easy to buy and awkward to report.
Imagine an investor in New Jersey who wants a ₹10 lakh diversified India allocation. A domestic Indian mutual fund may look operationally familiar, especially if the investor used mutual funds before moving abroad. A portfolio of direct Indian shares may look less convenient. Yet the U.S. compliance burden can reverse that intuition. The “simpler” Indian product may require more specialized U.S. tax work.
That does not mean direct shares are always superior, and it certainly is not a recommendation to build a concentrated portfolio merely to avoid paperwork. It means product selection should include the after-tax and after-compliance cost, not just expense ratios and past returns.
Before purchasing a foreign pooled vehicle, ask the U.S. tax adviser a very specific question: “Could this holding be a PFIC for me, and if so, what reporting and election choices would I have?” That single question is more useful than discovering Form 8621 during tax season.
FBAR: the $10,000 threshold adds foreign accounts together
FBAR catches investors because the threshold sounds larger than it is.
A U.S. person generally has an FBAR filing requirement when the aggregate value of foreign financial accounts exceeds $10,000 at any time during the calendar year. “Aggregate” is the important word. The test is not $10,000 per account.
Suppose a U.S.-based NRI has:
| Foreign account | Highest value during the year |
|---|---|
| NRE savings account | $6,500 |
| NRO account | $2,200 |
| Indian brokerage account | $4,800 |
| Aggregate for this illustration | $13,500 |
No single account exceeds $10,000, but the combined maximum values in this simplified illustration exceed the threshold. The filing analysis therefore does not end by looking at each account in isolation.
FinCEN and IRS guidance can encompass foreign bank, brokerage, securities and certain other financial accounts. The exact reportable-account analysis depends on the account and ownership or authority involved, so investors should not assume that “only bank accounts count.”
FBAR is also not an income-tax calculation. An account can be reportable even if it earned little or no income. That distinction matters for NRE accounts in particular. An investor may hear that qualifying NRE interest is exempt in India and incorrectly jump to “there is nothing to report in the U.S.” Indian tax exemption does not itself switch off U.S. worldwide-income or foreign-account rules.
For recordkeeping, retain statements that allow the maximum balance to be reconstructed. FinCEN’s rules require foreign-currency values to be translated into U.S. dollars using the prescribed year-end exchange-rate approach for FBAR reporting. Waiting until April to ask an Indian bank for old maximum-balance data is an avoidable headache.
Form 8938 is separate from FBAR
Form 8938 is often spoken about in the same breath as FBAR, but it is a different disclosure regime with different thresholds, definitions and filing mechanics.
For specified individuals living in the United States, the IRS currently summarizes the Form 8938 thresholds as follows:
| Filing status | Value on last day of tax year | Value at any time during tax year |
|---|---|---|
| Unmarried | More than $50,000 | More than $75,000 |
| Married filing separately | More than $50,000 | More than $75,000 |
| Married filing jointly | More than $100,000 | More than $150,000 |
These figures are for taxpayers living in the United States. Different thresholds can apply to qualifying taxpayers living abroad.
The larger lesson is more important than memorizing the numbers: filing one form does not automatically satisfy the other. A portfolio can require FBAR, Form 8938, both, or neither depending on the facts. The assets covered by the two regimes also do not match perfectly.
For a U.S.-based NRI who is building an Indian portfolio over many years, this is why keeping one annual foreign-assets worksheet is useful. List each account or holding, ownership, year-end value, maximum value where relevant, income received and supporting exchange-rate evidence. That worksheet will not replace the tax forms, but it reduces the chance that one account is forgotten when the portfolio becomes more complicated.
India can tax the investment, and the United States can still want it on the return
The U.S.–India income-tax treaty is useful, but it should not be imagined as a blanket exemption from one country’s tax.
Article 13 of the treaty is unusually direct on capital gains: apart from the shipping and air-transport exception, each country may tax capital gains under its domestic law. In other words, a U.S. resident selling Indian shares can still have an Indian tax consequence, while U.S. worldwide-tax rules may also require the gain to be reported in the United States.
On the Indian side, the current regime for qualifying listed equity transactions includes a 20% Section 111A rate for qualifying short-term gains on transfers on or after July 23, 2024, and a 12.5% Section 112A rate for qualifying long-term gains above the applicable aggregate ₹1.25 lakh threshold, subject to the statutory conditions. NRI withholding and final-tax mechanics can add another layer, so the amount deducted by a broker or intermediary should not automatically be assumed to be the final liability.
Rather than duplicate the full Indian tax treatment here, use the NRI capital-gains tax and TDS guide when you are planning a sale.
The U.S. side then has to be computed under U.S. rules. Cost basis, holding period, currency conversion and the character of income are U.S. tax questions even if the Indian broker has already supplied a rupee-denominated tax statement. The same transaction can therefore have two calculations built from the same economic event.
State tax adds another wrinkle. U.S. state rules are not identical to the federal system, and treaty or foreign-tax-credit treatment at state level can differ. A resident of California, for example, should not assume the federal answer automatically settles the state return.
The foreign tax credit is relief from double tax, not a promise of perfect matching
The treaty’s double-tax relief provisions are valuable precisely because the two systems can both reach the same income.
Article 25 provides, subject to U.S. law and its limitations, for a credit against U.S. income tax for qualifying Indian income tax paid by or on behalf of a U.S. resident or citizen. In practical U.S. filing, Form 1116 is commonly part of the foreign-tax-credit calculation for individuals when a credit is available.
The word “limitations” matters. A foreign tax credit is not a guarantee that every rupee paid in India reduces U.S. tax dollar for dollar in the same year. Source rules, income categories, timing, credit limitations and the nature of the foreign levy can affect the usable amount.
Timing can be especially irritating. India may deduct tax when a transaction occurs or when income is paid, while the U.S. return is prepared on a calendar-year basis. If an Indian refund is later claimed, or if tax was withheld in excess of the final Indian liability, the U.S. credit calculation may need to reflect what was actually creditable rather than treating every withholding amount as permanently paid tax.
This is one reason clean Indian tax records matter. Keep the contract note, broker tax statement, Form 26AS/AIS information where relevant, Indian return and proof of tax payment or refund. The goal is to be able to connect the Indian tax number used in the U.S. credit calculation to a real underlying transaction.
Repatriation is a banking trail, not a tax switch
Moving investment proceeds back to the United States is a separate job from calculating tax.
RBI rules allow different treatment depending on the account and investment route. NRE funds are generally repatriable. NRO balances are more restricted, although eligible NRO remittances can generally be made within the USD 1 million per financial-year facility subject to applicable conditions and taxes. For certain repatriation-basis investments, RBI rules also provide for eligible sale proceeds, net of taxes, to be remitted abroad or credited to the appropriate NRE/PIS route.
The important phrase is “net of taxes.” Repatriation is not a method for turning taxable income into non-taxable income. Nor does leaving the money in India necessarily remove it from U.S. reporting.
For a long-term investor, the best record trail follows the money from beginning to end:
U.S. bank → remittance → Indian NRE/NRO account → broker or fund platform → purchase → sale/distribution → tax deduction/payment → Indian bank → remittance back to the U.S.
If the bank later asks for documentation, or the investor needs to establish source and basis for U.S. reporting, that chain is far easier to defend than a folder full of unrelated screenshots.
The same principle matters after corporate actions. A demerger, bonus, split or other reorganization can alter the basis records needed when shares are eventually sold. RegalTicker’s Demerger Cost Basis Calculator can help preserve the India-side allocation after a demerger; U.S. tax treatment still needs to be checked separately rather than assuming the Indian allocation automatically controls the U.S. basis.
A practical sequence for investing from the United States
A good cross-border process is less about adding bureaucracy and more about doing things in the order that prevents expensive reversals.
Start with tax status. Confirm whether you are a U.S. citizen, green-card holder or otherwise a U.S. resident for federal tax purposes for the relevant year. Separately confirm your Indian FEMA and income-tax status.
Choose the asset before the platform. If the plan includes Indian mutual funds, ETFs, companies, deposits or other vehicles, identify the U.S. classification questions first. Do not choose a platform merely because onboarding is easy.
Design the Indian money route. Decide whether the investment is intended to be repatriable and whether the funding belongs in NRE or NRO. Then select a compatible bank/broker arrangement. The general NRI stock-market guide provides the broader India-side roadmap.
Ask the PFIC question before buying a pooled product. If a foreign fund or similar vehicle might fall within PFIC rules, understand the reporting consequences while the position is still zero—not after it has appreciated for several years.
Create the U.S. reporting file immediately. Record foreign account numbers, institutions, ownership, year-end balances, maximum balances, acquisition dates and costs. Add new accounts to the file when they are opened, not at year-end.
Track Indian tax separately from U.S. tax. Keep enough evidence to support the Indian return and enough data to translate the same investment activity into U.S. tax terms.
Plan the exit before a large sale. A sale can trigger Indian tax/TDS, U.S. gain reporting, foreign-tax-credit work and remittance documentation in the same year. The time to model that is before pressing sell on a major position.
The records worth keeping from day one
Cross-border investing becomes much easier when the investor keeps records as if an accountant will ask for them five years later—because that is often what happens.
For each Indian bank or brokerage relationship, retain opening documents, account type, statements and evidence of residential-status updates. For each investment, keep purchase contract notes, dates, quantity, rupee cost, fees and corporate-action records. For sales, keep the sale contract note, tax deducted, final Indian tax calculation and the bank trail for any remittance.
For U.S. work, it is sensible to preserve the exchange rate used in each calculation rather than leaving a bare converted dollar number in a spreadsheet. FBAR maximum values have their own conversion convention. Income-tax calculations can require different date-specific or prescribed exchange-rate treatment depending on the item. A documented source is much easier to review than a remembered Google conversion.
Corporate actions deserve special attention. If a company splits shares, issues bonus shares, demerges a business, merges into another company or distributes securities, save the company announcement and broker entries. Years later, the investor may need to explain why the number of shares changed or how basis moved between securities.
Also keep copies of U.S. forms actually filed—especially FBAR confirmation, Form 8938 and any Form 8621—alongside the Indian investment file. The next adviser should be able to see the reporting history without reconstructing it from zero.
Mistakes that become expensive only after the portfolio grows
The most painful cross-border mistakes are often quiet for a long time.
One is buying a foreign pooled investment without checking PFIC exposure. Nothing looks wrong in the Indian account. The investment may perform well. The complication appears only when the U.S. return is prepared or the position is sold.
Another is treating the FBAR threshold as a per-account threshold. Three modest Indian accounts can cross the aggregate $10,000 test even when none does individually.
A third is assuming that tax-free treatment in India means tax-free treatment in the United States. The U.S. worldwide-income principle can still apply. The reverse error also occurs: somebody pays Indian tax at source and assumes there can be no additional U.S. filing because “tax has already been paid.” Payment in one country and reporting in another are separate questions.
Investors also confuse account compliance with investment compliance. Updating an Indian savings account to NRO status is important, but it does not answer whether a mutual fund is a PFIC. Filing an FBAR does not replace Form 8938. Filing Form 8938 does not replace the income-tax return. Claiming a foreign tax credit does not automatically resolve state tax.
Finally, many people keep only the latest portfolio statement. That is enough to know what they own today, but not enough to prove what they paid, what happened during a demerger, which account funded the purchase or how much foreign tax was actually borne.
The larger the portfolio becomes, the more valuable boring paperwork becomes.
Investor note
Treat the record trail as part of the portfolio
Cross-border paperwork becomes more valuable as the position grows. Keep bank statements, contract notes, tax-withholding evidence, exchange-rate support and corporate-action records together. A future sale, demerger or adviser change is much easier when the history can be reconstructed without guesswork.
Frequently asked questions
Can an NRI living in the USA invest in Indian shares?
Yes, subject to the applicable Indian foreign-exchange, securities, KYC, banking and intermediary rules. The investor also needs to consider U.S. federal tax and reporting obligations if treated as a U.S. taxpayer. The NRI Demat guide covers the India-side account setup in detail.
Do I pay U.S. tax on Indian investment income?
U.S. citizens and resident aliens are generally subject to U.S. federal tax on worldwide income. The U.S. treatment of Indian dividends, interest and gains depends on the asset and facts. Indian tax already paid may potentially be relevant to the foreign tax credit, subject to U.S. rules and limitations.
Are Indian mutual funds PFICs for U.S. taxpayers?
Do not use a blanket assumption either way. PFIC status is determined under U.S. statutory income and asset tests and depends on the legal form and facts of the foreign entity. Because foreign pooled investment vehicles can raise PFIC issues, a U.S. taxpayer should review the specific product before purchase. Form 8621 reporting can be material when PFIC rules apply.
Does an NRE account have to be reported in the United States?
Potentially. U.S. foreign-account reporting is separate from India’s tax treatment of the account. An NRE account can be relevant to FBAR and/or Form 8938 depending on the investor’s U.S. status, ownership and applicable thresholds. The fact that qualifying NRE interest may receive favorable Indian tax treatment does not by itself remove U.S. reporting obligations.
Is FBAR required only if one Indian account exceeds $10,000?
No. The general FBAR threshold is based on the aggregate value of foreign financial accounts exceeding $10,000 at any time during the calendar year. Multiple smaller accounts can therefore trigger the filing requirement together.
If India taxes my share sale, will the U.S. tax it again?
The transaction can be relevant in both countries. The U.S.–India treaty allows both countries to tax capital gains under their domestic law, and its double-tax-relief article provides a foreign-tax-credit framework subject to U.S. law and limitations. The final outcome depends on the detailed computations; it should not be assumed that the two tax bills will match perfectly.
Is Form 8938 the same as FBAR?
No. They are separate reporting regimes. They use different rules and thresholds, and a taxpayer can be required to file both.
The useful decision is the one made before the first transfer
Investing in India from the United States is not inherently a bad or unmanageable idea. The mistake is treating it as though the only rulebook is Indian.
For many U.S.-based NRIs, the investment thesis may be perfectly sensible: exposure to Indian businesses, assets held in rupees, family-linked wealth in India or a long-term plan to return. But the vehicle used to express that thesis can matter almost as much as the thesis itself. A direct share, a mutual fund, a deposit and a family-held account do not create the same compliance footprint.
So build the structure in this order: establish your status, choose the asset with U.S. classification in mind, set up the correct Indian account route, keep a clean transaction trail, and know which U.S. reporting thresholds you are approaching. Only then decide how much money belongs in the strategy.
That order is less exciting than choosing a stock or fund. It is also the part most likely to save time, tax-preparation cost and unpleasant surprises later.
This guide is educational and does not replace individualized Indian or U.S. tax, legal or investment advice. Cross-border rules can depend on citizenship, immigration status, state residence, account ownership, product structure and the specific tax year.
Verify through official sources
Official references
- TITLE: Official sources
- Internal Revenue Service — U.S. citizens and resident aliens abroad — Official IRS guidance on worldwide income and foreign account reporting for U.S. citizens and resident aliens.
- Internal Revenue Service — Instructions for Form 8621 — Official PFIC definitions, filing situations and election framework.
- Internal Revenue Service — About Form 8621 — Official overview of Form 8621 for PFIC shareholders.
- Financial Crimes Enforcement Network — Report Foreign Bank and Financial Accounts — Official FBAR filing threshold and U.S.-person requirement.
- Internal Revenue Service — International individual tax FAQs — Official IRS summary of foreign-account and Form 8938 reporting.
- Internal Revenue Service — Summary of FATCA reporting for U.S. taxpayers — Official Form 8938 thresholds for taxpayers living in and outside the United States.
- Internal Revenue Service — U.S.–India Income Tax Treaty — Official treaty text, including Article 13 on gains and Article 25 on relief from double taxation.
- Internal Revenue Service — Publication 514, Foreign Tax Credit for Individuals — Official guidance on foreign tax credits for individuals.
- Reserve Bank of India — Accounts in India by Non-residents — RBI guidance on NRE/NRO account features and repatriability.
- Reserve Bank of India — Foreign Exchange Management (Non-debt Instruments) Rules / Schedule III — RBI source on NRI/OCI investment funding and repatriation-basis sale proceeds.
- Income Tax Department, India — Tax on Sale of Shares in India — Official Indian capital-gains rates and conditions for shares and specified securities.
- Income Tax Department, India — Capital Gain — Current official capital-gains overview, updated May 2026.