The IPO is finally priced — now the valuation deserves more attention than the hype
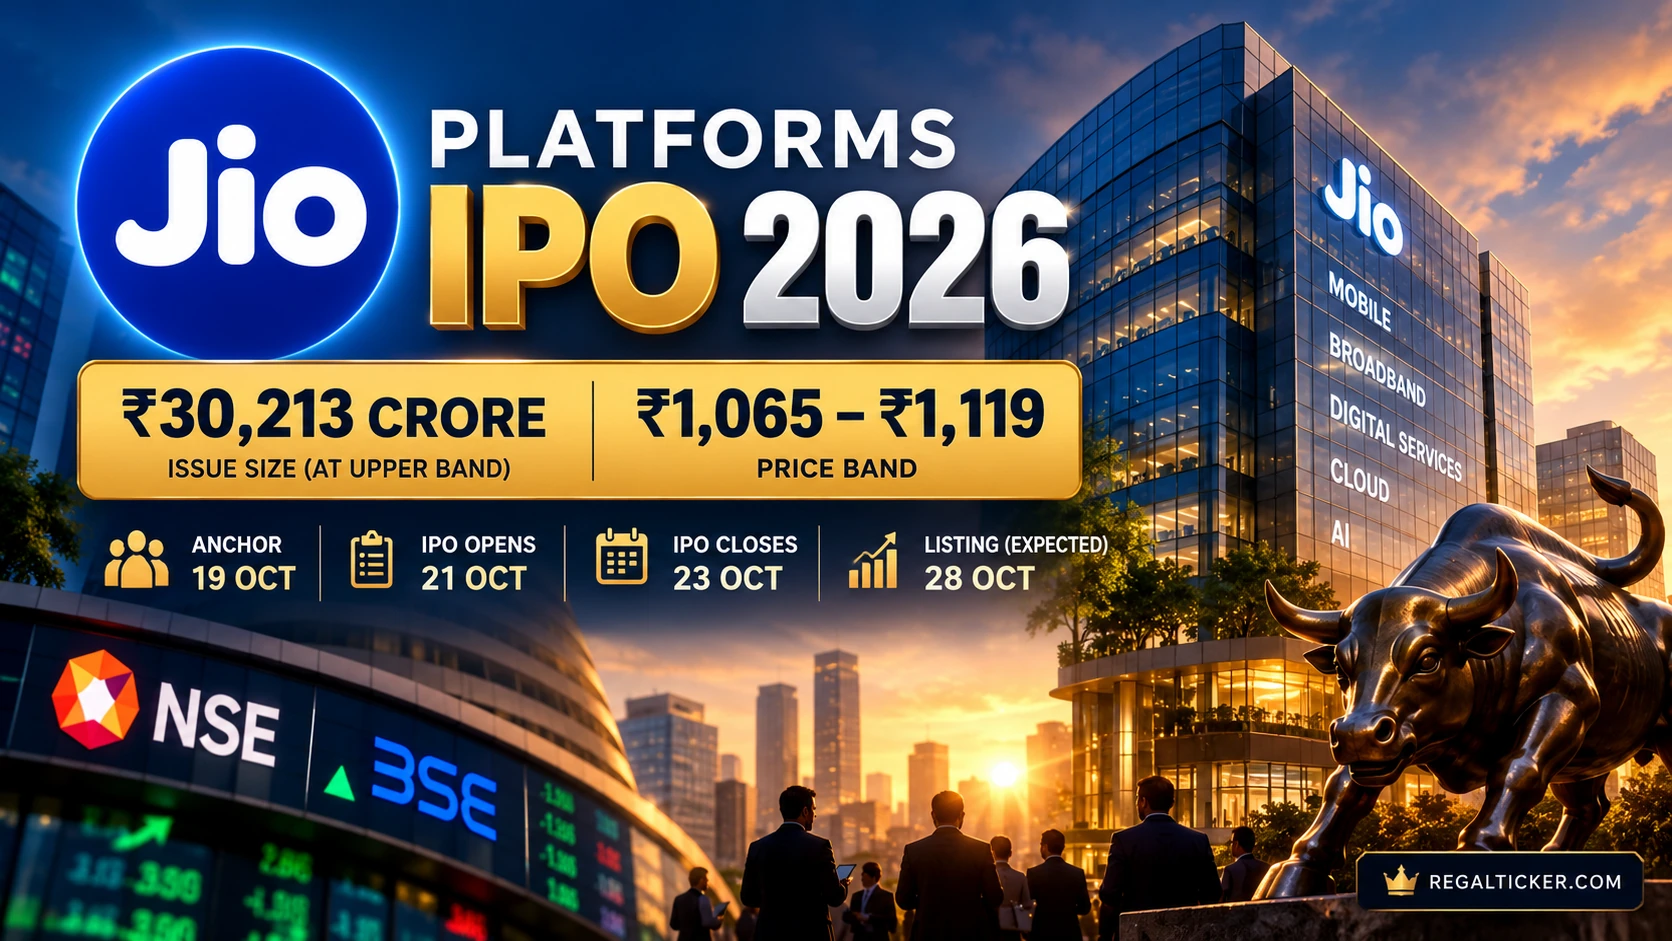
Jio Platforms has moved from years of listing speculation to a fully defined public issue. The Red Herring Prospectus was filed on 14 October 2026, SEBI published the RHP filing on 15 October, and Reliance Industries separately confirmed a ₹1,065–₹1,119 price band, a 12-share minimum bid lot and a ₹54-per-share employee discount. Public bidding is scheduled for 21–23 October 2026, with anchor bidding on 19 October.
At the cap price, 27 crore newly issued shares can raise about ₹30,213 crore, putting the proposed equity valuation near ₹10.3 lakh crore. That scale makes the offer important not only for IPO applicants but also for Reliance Industries shareholders, Bharti Airtel investors and anyone tracking how Indian markets value telecom, digital infrastructure, cloud and AI businesses.
The key question is no longer whether Jio will list. It is what investors should learn from the issue structure, use of proceeds, operating performance and risk disclosures before treating the brand, the grey-market premium or the headline issue size as evidence of value.
⚡ Quick answer
What is the latest Jio Platforms IPO update?
Jio Platforms’ IPO is scheduled to open on 21 October 2026 and close on 23 October 2026. The price band is ₹1,065–₹1,119 per share, the minimum bid lot is 12 shares, and the issue is a 100% fresh issue of up to 27 crore shares. At the upper band, the offer can raise about ₹30,213 crore and imply an equity valuation of roughly ₹10.3 lakh crore. Up to ₹2,500 crore of shares are reserved for eligible Reliance Industries public shareholders and up to ₹500 crore for eligible employees.
Key takeaways
Jio’s IPO is entirely a fresh issue; Reliance Industries, Meta, Google and other existing shareholders are not selling through an OFS.
The offer can raise ₹28,755 crore at the floor price and ₹30,213 crore at the cap price.
Up to ₹27,500 crore of net proceeds is intended for repayment or prepayment of specified borrowings at Reliance Jio Infocomm.
FY26 revenue from operations was ₹1,46,885 crore, EBITDA ₹76,255 crore and PAT ₹30,049 crore.
Jio entered Q1 FY27 with 533.3 million subscribers, roughly 285 million 5G users and ARPU of ₹215.6.
A simple post-issue FY26 earnings calculation puts the upper-band P/E near 34 times; that is a valuation input, not a verdict.
Unofficial GMP around 17 October was near ₹220 per share on some trackers, but GMP is unregulated and can change quickly.
The RHP highlights risks around customer churn, capital intensity, cybersecurity, data regulation, technology shifts and competition.
1. Jio Platforms IPO 2026: confirmed issue details
The most important IPO terms are now fixed rather than estimated. Reliance Industries’ 14 October exchange filing confirms the price band, employee discount and 12-share bid lot, while the RHP fixes the bidding window and issue structure.
| IPO detail | Confirmed / current information |
|---|---|
| Company | Jio Platforms Limited |
| Promoter | Reliance Industries Limited |
| Issue type | 100% fresh issue |
| New shares offered | Up to 27 crore equity shares |
| Face value | ₹10 per share |
| Price band | ₹1,065–₹1,119 |
| Issue size at floor | ₹28,755 crore |
| Issue size at cap | ₹30,213 crore |
| Minimum bid lot | 12 shares |
| Minimum amount at floor | ₹12,780 |
| Minimum amount at cap | ₹13,428 |
| Employee discount | ₹54 per share |
| Anchor investor bidding | 19 October 2026 |
| Public issue opens | 21 October 2026 |
| Public issue closes | 23 October 2026 |
| Expected allotment | 26 October 2026 |
| Expected listing | 28 October 2026 |
| Proposed exchanges | BSE and NSE |
🧮 Simple calculation
How the headline IPO size is calculated
At the cap price, 27 crore new shares × ₹1,119 = ₹30,213 crore. For one retail lot, 12 shares × ₹1,119 = ₹13,428. At the floor price, 27 crore shares × ₹1,065 = ₹28,755 crore.
Readers who want the mechanics behind these numbers can use RegalTicker’s IPO price band, lot size and issue size guide.
2. Why the issue structure matters: Jio is raising new capital
Jio’s offer is structurally different from an IPO dominated by an offer for sale. All 27 crore shares are newly issued shares, so the cash raised flows to the company rather than primarily to existing shareholders who are exiting.
That means Reliance Industries and strategic investors such as Meta and Google are not selling their existing holdings through this IPO. The distinction matters because a fresh issue expands the share count and dilutes existing percentage ownership, but it also adds capital to the business.
The post-issue effect should therefore be analysed in two steps: first, what the new money does to Jio’s balance sheet; second, whether the operating business can generate enough future earnings and cash flow to justify the enlarged equity base.
For a deeper explanation of this distinction, see RegalTicker’s fresh issue vs offer for sale guide.
3. Where the IPO money is going: debt reduction is the main object
Jio plans to use up to approximately ₹27,500 crore of net proceeds to repay or prepay specified borrowings associated with its material subsidiary Reliance Jio Infocomm. The balance can be used for general corporate purposes within the limits described in the offer document.
That is important because this is not an IPO built around one large acquisition or one new network project. A substantial part of the equity capital is being used to reduce financing obligations.
Lower borrowings can improve financial flexibility, reduce future interest burden and make the balance sheet more resilient. It does not, however, automatically create operating growth. After the debt reduction, the long-term case will still depend on customer monetisation, broadband expansion, digital services, cloud, enterprise demand, AI-related products and the returns earned on Jio’s large installed network.
Highlight
Key point
The IPO can improve Jio’s financing structure, but the value of the equity after listing will still depend on operating growth and returns on capital rather than debt reduction alone.
4. The ₹10.3 lakh crore valuation: what does the price band imply?
At ₹1,119 per share, Jio is being valued at roughly ₹10.3 lakh crore, or about $108 billion at the exchange rates used in contemporary market reporting. That would immediately place Jio among India’s largest listed companies if the offer completes and the stock begins trading near the issue valuation.
A simple trailing valuation check can be built from FY26 earnings and the enlarged post-issue share count.
🧮 Simple calculation
Simple post-issue FY26 P/E at the upper band
FY26 profit after tax: approximately ₹30,049 crore. Post-issue shares: about 920.9 crore shares. Approximate post-issue FY26 EPS: ₹30,049 crore ÷ 920.9 crore ≈ ₹32.63. Upper price band: ₹1,119. Simple trailing P/E: ₹1,119 ÷ ₹32.63 ≈ 34.3×.
This calculation is deliberately simple. It does not forecast FY27 or FY28 earnings, assign a premium for digital businesses, or adjust for different enterprise-value assumptions. Its purpose is to show what earnings level is embedded in the headline price.
Reuters reported that Nomura estimated Jio at roughly 10.5–10.9× FY28 EV/EBITDA, compared with about 9.2× for Bharti Airtel. The relevant investor question is therefore not whether Jio is a large or successful company, but whether its growth, margins and future digital monetisation justify the premium the market may place on it.
5. Jio’s financials: growth is strong, but returns on capital deserve attention
Jio enters the IPO with a large and profitable operating base.
| Metric | FY24 | FY25 | FY26 |
|---|---|---|---|
| Revenue from operations | ₹1,09,558 crore | ₹1,28,218 crore | ₹1,46,885 crore |
| EBITDA | ₹54,959 crore | ₹64,170 crore | ₹76,255 crore |
| EBITDA margin | 50.16% | 50.05% | 51.91% |
| Profit after tax | ₹21,423 crore | ₹26,109 crore | ₹30,049 crore |
| PAT margin | 19.55% | 20.36% | 20.46% |
| Net leverage | 0.88× | 0.71× | 0.36× |
| Return on average capital employed | 12.83% | 12.50% | 10.76% |
The growth trend is clear: FY26 revenue from operations increased about 14.6%, EBITDA about 18.8% and PAT about 15.1% year on year. EBITDA margin also expanded to 51.9%, while net leverage fell materially.
The counterpoint is return on average capital employed, which declined from 12.83% in FY24 to 10.76% in FY26. That does not erase the earnings growth, but it is an important signal for a capital-intensive network business. More capital, spectrum, technology and infrastructure must eventually translate into sufficiently attractive returns.
The latest completed quarter adds another layer. In Q1 FY27, Jio reported about ₹39,173 crore of revenue from operations, ₹20,865 crore of EBITDA and ₹7,764 crore of PAT. EBITDA margin reached about 53.3%, while higher depreciation and finance costs limited the pace of bottom-line growth.
Investor note
Important point
Strong revenue and EBITDA growth answer only part of the valuation question. A useful IPO review should also track cash generation, capex, leverage and return on capital instead of treating subscriber growth as a substitute for profitability.
6. Scale is Jio’s advantage; monetisation is the next test
Jio ended June 2026 with approximately 533.3 million subscribers, including around 285 million 5G users. Reliance says Jio carries roughly 60% of India’s data traffic, while Q1 FY27 ARPU was about ₹215.6.
That scale gives Jio a distribution advantage few digital businesses can replicate. It can place connectivity, home broadband, content, cloud, enterprise services and AI-enabled products in front of an enormous installed customer base.
The challenge is converting that reach into higher-quality revenue and returns without relying only on tariff increases. Management has highlighted home broadband, enterprise services, digital platforms, AI, cloud infrastructure and technology exports as future growth areas.
The market therefore has two different businesses to value simultaneously: a mature, highly scaled connectivity engine and a portfolio of newer digital opportunities whose future economics are still developing.
For readers comparing business quality with valuation, RegalTicker’s fundamental analysis guide provides a framework for separating growth, margins, balance-sheet strength, cash flow and return ratios.
7. RIL shareholder quota and employee reservation
The offer includes a meaningful reservation for two groups.
Up to ₹2,500 crore of shares are reserved for eligible public shareholders of Reliance Industries, and up to ₹500 crore is reserved for eligible Jio employees. Eligible employees receive the announced ₹54-per-share discount.
For the RIL shareholder reservation, the relevant eligibility date is 14 October 2026, the date of the RHP filing. The RHP defines the qualifying public-shareholder conditions and applies the applicable bid limits.
The practical lesson is simple: owning Reliance shares after the eligibility date does not retrospectively create shareholder-reservation eligibility. Investors should use the final offer document and their actual demat holding status rather than relying on social-media summaries.
Caution
Check this carefully
The shareholder reservation is an application category, not an assurance of allotment or a signal that the IPO is attractively valued.
8. Jio IPO GMP: useful sentiment data, but not an official price
Grey-market activity is one of the highest-interest searches around the IPO. On 17 October 2026, some unofficial trackers were showing Jio at a premium of roughly ₹220 per share, close to 20% above the ₹1,119 cap price.
That number should be handled carefully.
GMP is not an NSE quote, not a BSE quote and not part of the regulated price-discovery mechanism. It is an informal market indication that can change sharply as anchor demand, subscription data, global markets and broader risk sentiment evolve.
Risk
Understand the risk
Do not convert a current GMP into a promised listing price. A ₹220 grey-market premium today does not guarantee that the stock will list ₹220 above the issue price.
For this Market News article, GMP is treated as a dated sentiment snapshot rather than an investment conclusion.
9. The RHP risk section matters more than the brand name
Jio’s scale is exceptional, but the RHP also describes risks that can affect future earnings and valuation.
Tariff increases and customer churn
Higher tariffs can improve ARPU, but price increases can also raise churn among price-sensitive customers. Jio therefore has to balance monetisation with retention.
Capital intensity and technology execution
Networks, spectrum, data centres, software and new digital infrastructure require substantial investment. New technology initiatives can cost more than expected, take longer to scale, or generate lower returns than planned.
Data privacy and cybersecurity
Jio stores and processes large volumes of customer and operational data. The RHP highlights cybersecurity, privacy, compliance and evolving data-protection requirements as material risks. Additional regulation can increase compliance costs or restrict some data-driven monetisation models.
Competition can come from outside traditional telecom
Bharti Airtel and Vodafone Idea are established telecom competitors, but Jio also has to monitor fixed wireless access, satellite connectivity, global technology platforms and new network standards. The company itself identifies technology shifts and more competitive satellite broadband as potential business risks.
Scale increases concentration risk
Jio’s core telecom subsidiary remains central to consolidated revenue and cash generation. Disruption to connectivity operations, regulation, customer economics or network quality can therefore affect the wider platform.
The point of reading these risks is not to predict which one will occur. It is to understand what evidence should be monitored after listing.
10. Why the IPO matters for Reliance Industries and Bharti Airtel
Jio’s listing creates a public-market valuation for an asset that has historically been embedded inside Reliance Industries.
That can make the value of Reliance’s remaining Jio stake easier for the market to observe. Reuters reported that Reliance Industries rose 3.44% on 15 October after the pricing announcement, while Bharti Airtel gained 3.3% as investors reassessed telecom-sector valuation benchmarks.
Reliance is still expected to own roughly 64.5% of Jio after the issue, so the IPO is not a separation of control. The parent will retain a large economic interest even after public investors enter.
For Airtel, a separately listed Jio creates a direct market comparison across customer monetisation, ARPU, margins, capex, enterprise exposure and returns on capital. That comparison may become more useful than simple subscriber-count headlines.
11. What evidence matters between now and listing?
The IPO calendar now provides a sequence of observable events.
1
**19 October
Anchor bidding:** institutional allocation provides the first direct demand signal.
2
**21 October
Public bidding opens:** category-wise subscription starts replacing pre-issue speculation with measurable demand.
3
**23 October
Issue closes:** the final subscription mix becomes visible.
4
**26 October
Expected allotment:** investors can assess the basis of allotment and final issue-price outcome.
5
**28 October
Expected listing:** a regulated secondary-market price finally replaces the grey-market narrative.
6
After listing, the important evidence changes. Subscription multiples matter less, while ARPU, subscriber quality, broadband adoption, digital-services growth, capex, cash conversion and return on capital matter more.
Checklist before you act
- Separate official RHP facts from market rumours.
- Watch the final issue price rather than assuming the cap price.
- Compare subscription quality across investor categories, not just the total headline multiple.
- Revisit the valuation using updated earnings rather than GMP.
- Track whether Q2 and later results support the earnings assumptions embedded in the IPO price.
- Use RegalTicker’s risk management learning path to keep position sizing separate from excitement around a high-profile listing.
12. IPO is not demerger: an important Reliance investor distinction
The Jio Platforms IPO should not be confused with a demerger.
An IPO issues new shares to public investors in exchange for capital. A demerger separates an existing business or undertaking and can require an existing shareholder to allocate the original purchase cost between the resulting securities.
Investor note
Why the distinction matters for cost basis
Buying Jio shares through this IPO does not require an investor to split the historical purchase cost of Reliance Industries shares. That is a different problem from a demerger such as the earlier Jio Financial Services separation. When an investor does need to allocate original acquisition cost after a demerger, RegalTicker’s Demerger Cost Basis Calculator can help apply the relevant company-announced cost percentages instead of using post-event market prices.
Frequently asked questions
When does the Jio Platforms IPO open?
Public bidding is scheduled to open on 21 October 2026 and close on 23 October 2026. Anchor bidding is scheduled for 19 October.
What is the Jio IPO price band?
Reliance Industries has confirmed a price band of ₹1,065 to ₹1,119 per equity share.
What is the minimum lot size?
The minimum bid lot is 12 shares. At the upper band, one lot equals ₹13,428 before any applicable employee discount.
How large is the IPO?
Jio is offering up to 27 crore newly issued shares. At the ₹1,119 cap price, the issue size is about ₹30,213 crore.
Is the IPO a fresh issue or an OFS?
It is a 100% fresh issue. Existing shareholders are not selling shares through an offer-for-sale component.
What is the RIL shareholder quota?
Up to ₹2,500 crore of shares are reserved for eligible Reliance Industries public shareholders, subject to the RHP conditions. The relevant eligibility date is 14 October 2026.
What is the latest Jio IPO GMP?
Unofficial trackers on 17 October were indicating roughly ₹220 per share. GMP is unregulated, can change quickly and does not guarantee the listing price.
When is Jio expected to list?
The current expected listing date is 28 October 2026 on BSE and NSE.
Does buying Jio in the IPO change the cost basis of existing Reliance shares?
No. An IPO purchase is separate from a demerger cost-allocation exercise.
Verify through official sources
Official references
- Reliance Industries — Jio IPO price band, employee discount and bid lot — Official 14 October 2026 exchange filing confirming ₹1,065–₹1,119 price band, ₹54 employee discount and 12-share minimum bid lot.
- SEBI — Jio Platforms Limited Red Herring Prospectus — Official SEBI filing page for the RHP published 15 October 2026.
- Reliance Industries — FY26 financial and operational performance — Official FY26 Jio revenue, EBITDA, PAT, margin and subscriber information.
- Reliance Industries — Financial reporting and Q1 FY27 transcript — Official Q1 FY27 operating and financial context including subscribers, revenue, EBITDA and data traffic.
- Reuters — Jio seeks $108 billion valuation in record IPO — Current issue size, valuation, 533 million subscriber scale, data traffic and IPO structure context.
- Reuters — Reliance and Airtel rally as Jio IPO recasts valuations — Market reaction and telecom valuation comparison.
- IPO Central — Jio Platforms IPO GMP tracker — Unofficial dated GMP snapshot used only as a sentiment indicator.
- RegalTicker — Market News — RegalTicker’s source-led market and company news section.
Educational disclaimer: This Market News article is for investor education and general information only. It is not personalised investment advice, a recommendation to apply for the Jio Platforms IPO, or a prediction of listing gains. IPO details, unofficial GMP and market conditions can change. Readers should verify the latest RHP, exchange announcements, registrar information and their own eligibility before taking any action.
Final takeaway
The offer is defined; the real question is whether future returns justify the valuation
Jio Platforms enters the public market with exceptional scale, strong EBITDA margins, rising profit and lower leverage. Against those strengths are a valuation near ₹10.3 lakh crore at the upper band, declining return on average capital employed, substantial ongoing capital requirements and execution risks around digital monetisation, regulation and technology. The most useful approach is therefore to read the RHP, follow the subscription evidence and keep valuation separate from brand recognition or grey-market excitement.