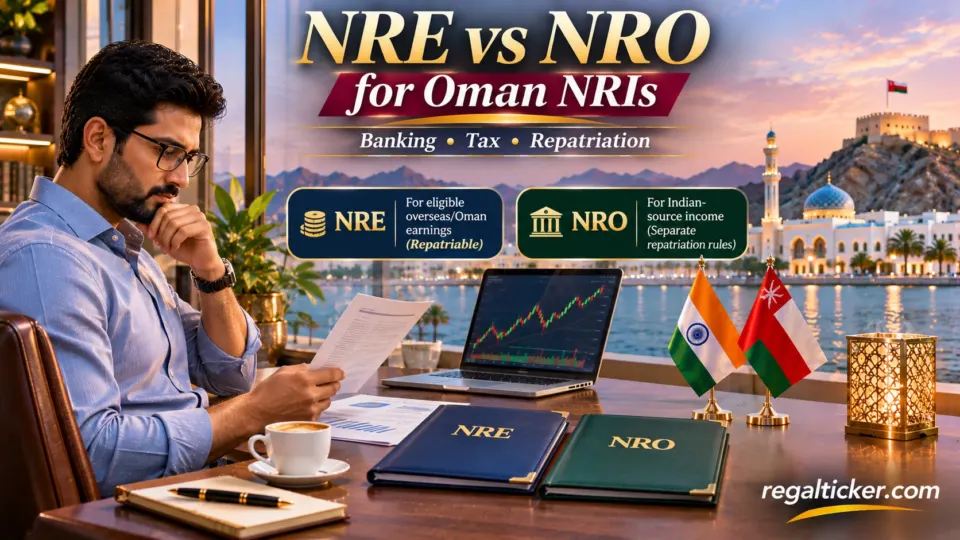
Use NRE for eligible overseas money, NRO for Indian money
For an Indian living in Oman, the easiest way to understand NRE and NRO is to follow the source of the money. Eligible salary and savings earned in Oman usually belong on the NRE side when repatriability matters. Indian-source income such as rent, pension, dividends and local interest usually belongs on the NRO side. Many Oman NRIs therefore need both accounts rather than choosing only one.
⚡ Quick answer
Which account should an Oman NRI use?
Use NRE for eligible foreign earnings and overseas savings that you may want to move back abroad freely. Use NRO for legitimate Indian-source rupee income and local payments. NRE balances are repatriable. NRO current income can be remitted abroad after compliance, while eligible NRO capital balances use the separate USD 1 million per Indian financial year facility.
Key takeaways
NRE and NRO are both rupee-denominated accounts.
NRE is mainly suited to eligible overseas earnings and repatriable money.
NRO is suited to Indian-source income and rupee receipts.
NRE balances are repatriable under RBI rules.
NRO current income can be remitted abroad separately.
Eligible NRO capital balances can be remitted up to USD 1 million per Indian financial year, subject to conditions.
Eligible NRO-to-NRE transfers also use that USD 1 million facility.
NRE interest remains exempt in India while the statutory and FEMA conditions are satisfied.
NRO interest is taxable in India.
Forms 145 and 146 replaced 15CA/15CB for relevant remittances from 1 April 2026.
Both NRE and NRO remain exposed to INR currency risk.
Oman’s new 5% personal income tax begins in 2028, not in 2026.
OMR remains fixed to USD at USD 2.6008 per OMR.
Investor note
The bank-account choice is really a money-source choice
Do not ask only “which account gives a better rate?” Ask where the money came from, whether it may need to return to Oman, and what tax trail it needs to keep.
1. What is an NRE account?
NRE stands for Non-Resident External Rupee Account.
It is designed for eligible funds coming from outside India.
For an Oman resident, a common flow is:
OMR salary or savings → international remittance → NRE account → Indian investment or deposit
RBI treats NRE balances as repatriable.
You can generally use the account for local payments, Indian investments and permitted outward remittances.
2. What is an NRO account?
NRO stands for Non-Resident Ordinary Rupee Account.
It is designed for legitimate rupee transactions in India.
Typical credits can include:
- rent;
- pension;
- dividends;
- Indian interest;
- local sale proceeds;
- transfers permitted under FEMA;
- other legitimate Indian dues.
NRO is therefore the natural account for money that arises in India.
3. Why many Oman NRIs need both
A simple structure can be:
NRE
For eligible Oman salary and overseas savings.
NRO
For Indian rent, pension, dividends, local interest and other Indian-source receipts.
Keeping the two money streams separate makes tax, audit trail and repatriation easier to understand later.
For the full Oman investing framework: https://regalticker.com/nri-investing-oman
4. NRE repatriation is the simpler route
RBI classifies NRE balances as repatriable.
That means eligible principal and permitted balances can generally move abroad without the separate USD 1 million capital-remittance ceiling that applies to eligible NRO capital balances.
Normal bank, KYC and compliance checks can still apply.
5. NRO current income is separately remittable
This is one of the most misunderstood NRO rules.
RBI allows NRO accounts to be debited for remittance of current income abroad.
Current income can include eligible:
- rent;
- dividends;
- pension;
- interest;
- other permitted recurring receipts.
This is separate from the USD 1 million facility for eligible capital balances.
6. The USD 1 million facility applies to eligible NRO capital
RBI permits NRIs and eligible persons of Indian origin to remit up to USD 1 million per Indian financial year from eligible NRO balances and specified assets, subject to conditions.
The financial year runs from April to March.
Eligible NRO-to-NRE transfers also use this same facility.
The authorised dealer bank can ask for source-of-funds and tax evidence before processing the transfer.
7. NRE interest remains exempt in India while eligible
The Income Tax Department confirms that the NRE-interest exemption continues under the Income Tax Act, 2025.
The exemption still depends on the applicable FEMA-linked eligibility conditions.
So the tax exemption follows the legal status of the account holder; it is not simply attached forever to any account labelled NRE.
8. NRO interest is taxable in India
NRO interest is taxable in India.
That means an Oman NRI should compare NRO deposit returns after:
- Indian tax;
- TDS;
- any available treaty relief;
- fees;
- currency conversion.
The gross interest rate alone is not the real return.
9. Forms 145 and 146 now apply to relevant remittances
For remittances made on or after 1 April 2026, the Income Tax Department uses:
- Form 145 instead of Form 15CA;
- Form 146 instead of Form 15CB.
Form 146 is the CA certificate used in the prescribed taxable-remittance cases, including the current threshold framework where applicable.
Banks can also ask for supporting tax and source documents depending on the remittance.
10. NRE and NRO do not remove currency risk
Both accounts are denominated in INR.
The Central Bank of Oman keeps the rial fixed at USD 2.6008 per OMR.
So the real path is:
OMR → INR → NRE/NRO or Indian investment → INR → OMR
If INR weakens, the value of the account can fall in OMR terms even if the rupee balance itself has not changed.
11. Which account should fund Indian investments?
The answer depends on the intended repatriation treatment.
Eligible overseas money invested on a repatriable basis should follow the correct repatriable route.
Non-repatriation investments use the applicable NRO-linked route.
For direct Indian equities: https://regalticker.com/how-to-invest-indian-stocks-oman
Do not move money between accounts merely to simplify an app screen if the transfer changes or obscures the original regulatory trail.
12. Oman tax is changing in 2028
Oman has enacted a personal income tax law under Royal Decree 56/2025.
The law starts at the beginning of 2028.
It provides a 5% tax on taxable income for natural persons whose annual total income exceeds OMR 42,000, subject to the law’s detailed categories, deductions and exemptions.
For a 2026 banking decision, the new tax has not yet begun.
But a long-term Oman NRI plan should not assume the local tax environment will remain unchanged forever.
13. What happens when you return permanently to India?
When your FEMA residential status changes back to resident, your non-resident banking structure must also be updated.
RBI rules provide for redesignation of NRO accounts to resident accounts when the account holder returns to India for a purpose indicating an intention to stay for an uncertain period.
NRE and other non-resident accounts also need to be handled under the applicable return-to-India rules.
Do not keep operating NRI accounts indefinitely after becoming resident again.
14. A practical Oman NRI banking setup
A clean structure can look like:
Oman salary and savings → NRE Indian rent / pension / dividends → NRO Repatriable Indian investing → eligible NRE-linked route Indian-source receipts and non-repatriation investments → NRO Eligible NRO current income → outward remittance after compliance Eligible NRO capital → USD 1 million annual facility where applicable
Keep the bank statements and original source records for both accounts.
Investor note
NRE and NRO are not competing products
They are different lanes. Trying to force every transaction through one account can make repatriation and tax documentation harder later.
Frequently asked questions
Can an Oman NRI open both NRE and NRO accounts?
Yes. Many NRIs need both because foreign earnings and Indian-source income follow different regulatory routes.
Should Oman salary go to NRE or NRO?
Eligible overseas salary or savings are generally better suited to NRE where repatriability matters.
Where should Indian rent go?
Indian-source rent is normally handled through NRO.
Is NRE money freely repatriable?
RBI classifies NRE balances as repatriable, subject to normal banking and compliance requirements.
Is all NRO money limited to USD 1 million per year?
No. Eligible current income is separately remittable. The USD 1 million facility applies to eligible capital balances and specified assets.
Can I transfer NRO money to NRE?
Eligible NRO-to-NRE transfers can use the USD 1 million annual facility.
Is NRE interest tax-free in India?
Yes, while the applicable statutory and FEMA-linked eligibility conditions are satisfied.
Is NRO interest taxable?
Yes. NRO interest is taxable in India.
Are Forms 15CA and 15CB still used for new remittances?
For remittances made on or after 1 April 2026, the corresponding forms are Form 145 and Form 146.
Does Oman personal income tax apply now?
No. The new Oman personal-income-tax law begins in 2028.
Does NRE protect against INR depreciation?
No. NRE is still an INR account, so OMR/INR currency movement can affect the real value for an Oman household.
Verify through official sources
Official references
- Reserve Bank of India — NRI Account FAQ — Current NRE/NRO permissible credits, debits, repatriability and tax summary.
- Reserve Bank of India — Deposits and Accounts Master Direction — Current NRO operating rules, current-income remittance and USD 1 million framework.
- Reserve Bank of India — Remittance of Assets Master Direction — Current USD 1 million annual remittance framework and tax-clearance requirement.
- Income Tax Department — Non Resident FAQ — Confirmation that the NRE-interest exemption continues under the Income Tax Act, 2025.
- Income Tax Department — Income Tax Forms FAQ — Current Form 145/146 remittance framework from 1 April 2026.
- Oman Tax Authority — Personal Income Tax Law — Official 5% PIT, OMR 42,000 threshold and 2028 commencement.
- Central Bank of Oman — Fixed Peg of the RO to the US Dollar — Official USD 2.6008 per OMR fixed-parity framework.
Final takeaway
Keep Oman money and Indian money in the right lanes
For an Oman-based NRI, NRE and NRO work best together. Use NRE for eligible overseas earnings where repatriability matters, NRO for Indian-source money, and keep the original source trail intact. That makes Indian investing, tax documentation and eventual repatriation much easier—and lets you measure the final result in OMR rather than only in rupees.
Educational disclaimer: This article is for investor education only and is not personal tax, FEMA, legal or banking advice. Account eligibility, tax treatment, repatriation and future Oman PIT treatment depend on individual facts and current rules. Confirm the latest position with your bank, RBI, Indian Income Tax Department, Oman Tax Authority and qualified advisers before acting.