India’s biggest foreign banking investment has become a debate about price, control and what IDBI should be worth
The proposed transfer of control in IDBI Bank to Canada’s Fairfax Financial Holdings has moved from a long-running privatisation process into a full public debate.
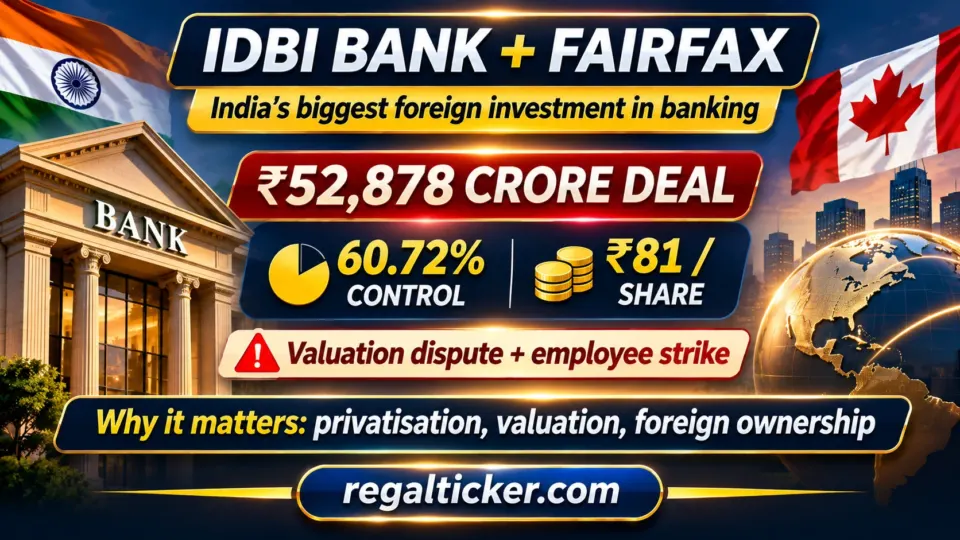
India has approved the sale of a 60.72% stake in IDBI Bank to Fairfax for ₹52,878 crore, or ₹81 per share. Reuters describes it as the largest foreign investment in India’s banking sector.
But the deal is facing opposition from employees and political groups. IDBI officers and employees continued a nationwide strike on 3 November, arguing that the valuation does not properly reflect the bank’s private-sector status, turnaround and future potential. The government has rejected allegations that the bank was undervalued and says the valuation process was reviewed through the prescribed disinvestment mechanism.
The dispute matters because IDBI is not the distressed lender it was several years ago.
Its gross bad-loan ratio has fallen from nearly one-third of loans during the banking crisis to around 2.3% by June 2026. Fairfax is also not buying IDBI simply as a standalone bank. It plans to turn the lender into a broader financial-services platform by bringing its stakes in IIFL Capital Services and Digit into the group, subject to regulatory approvals.
That changes the investment question.
This is no longer only about whether ₹81 per share is a fair privatisation price. It is also about whether a repaired bank can be re-rated under new ownership, how much value remains with the government and LIC after the sale, and whether the transaction becomes a template for more foreign capital entering Indian banking.
⚡ Quick answer
What exactly is the IDBI Bank–Fairfax deal?
Fairfax Financial Holdings is set to acquire 60.72% of IDBI Bank from the Government of India and Life Insurance Corporation of India for ₹52,878 crore, paying ₹81 per share. The government will sell 30.48% and LIC 30.24%. After the transaction, the two sellers are expected to retain about 34% combined. The deal transfers management control to Fairfax but remains subject to final agreements and regulatory approvals. Employees and political groups are challenging the valuation and privatisation process, while the government says the methodology was properly reviewed.
Key takeaways
Fairfax is buying 60.72% of IDBI Bank for ₹52,878 crore.
The offer price is ₹81 per share.
The government’s benchmark valuation was ₹75.99 per share.
IDBI shares closed at ₹90.44 on 14 October, when the buyer was announced.
The deal implies an equity value of roughly ₹87,000 crore for the whole bank.
The Government of India is selling 30.48%; LIC is selling 30.24%.
The government and LIC are expected to retain roughly 34% combined after the transaction.
Employee unions are striking and questioning the valuation methodology.
The government rejects allegations that the bank was sold below fair value.
IDBI’s gross NPA ratio improved to about 2.3% by June 2026 from nearly 32% in 2018.
Fairfax plans to use IDBI as the holding platform for IIFL Capital Services and Digit, subject to approvals.
Fairfax also owns 40% of CSB Bank and has two years to decide whether to merge or sell that stake.
The deal is a major test of India’s bank-privatisation strategy and willingness to allow foreign control in banking.
A change in ownership can improve valuation only if growth, return ratios, governance and execution improve.
1. The numbers behind the transaction
The headline deal value is ₹52,878 crore for a 60.72% controlling stake.
The stake being sold is split almost evenly between the two existing controlling shareholders:
- Government of India: 30.48%
- Life Insurance Corporation of India: 30.24%
Fairfax will pay ₹81 per share.
That price is above the government’s benchmark valuation of ₹75.99 per share, but it was below IDBI Bank’s market price when Fairfax was named the preferred strategic buyer.
IDBI shares closed at ₹90.44 on 14 October, up 9% that day.
So the market was already assigning more value to the listed shares than the transaction price.
At ₹52,878 crore for 60.72%, the deal implies an equity value of roughly ₹87,000 crore for 100% of IDBI Bank.
That figure is central to the current debate.
Employees argue that a bank classified as private for regulatory purposes should not be valued using comparisons that resemble lower-valued public-sector lenders.
The government says the valuation process was independently reviewed and denies that the bank was deliberately undervalued.
2. Why the strike is about more than jobs
The United Forum of IDBI Officers and Employees has opposed the privatisation and continued a nationwide strike for a second day on 3 November.
Its argument is not simply that ownership is changing.
The union says there is an inconsistency in how IDBI is treated.
For regulation and court rulings, IDBI Bank has been classified as a private-sector bank since LIC acquired control in 2019.
But union representatives argue that the valuation framework effectively compares it with lower-valued public-sector banks.
They want the privatisation plan withdrawn and majority public ownership restored.
That position is contested.
The finance ministry argues that IDBI had been weakened by years of corporate lending, required major recapitalisation and was revived only after a difficult clean-up.
From that perspective, the sale represents the final stage of a rescue-and-restructuring process rather than the disposal of an untouched public asset.
Both positions matter for investors because they explain why the dispute is unlikely to be resolved by looking at one share-price chart.
3. IDBI Bank is no longer the distressed bank Fairfax first studied
The strongest argument for a higher valuation is the improvement in IDBI’s balance sheet.
At the height of India’s banking bad-loan crisis, IDBI’s gross non-performing assets were close to one-third of its loan book.
By June 2026, Reuters reported the gross bad-loan ratio had fallen to around 2.3%.
That is a dramatic repair.
LIC’s rescue was a major part of that process.
In 2019, LIC became the controlling shareholder after injecting ₹21,624 crore and taking a 51% stake. Further capital support from LIC and the government followed as the bank worked through stressed assets.
The bank now has:
- more than 2,000 branches;
- total assets of roughly ₹4.44 trillion as of June 2026; and
- a much cleaner loan book than during the crisis period.
This matters because Fairfax is not buying a failing institution.
It is buying a repaired banking franchise with deposits, branches, customers and regulatory licences already in place.
That is one reason foreign buyers increasingly prefer to acquire existing Indian financial institutions rather than build from scratch.
4. Is ₹81 per share cheap or fair?
There is no single answer.
The government’s benchmark was ₹75.99, so Fairfax’s ₹81 offer is above that formal reference point.
But the market price was above ₹90 when the deal was announced.
Reuters Breakingviews estimated that Fairfax is paying around one times trailing book value.
For comparison, a high-quality private bank such as ICICI Bank traded at a substantially higher multiple at the time.
That does not automatically mean IDBI is being sold too cheaply.
A valuation discount can reflect:
- lower return ratios;
- weaker franchise quality;
- less efficient technology;
- ownership-transition risk;
- employee disruption;
- slower growth;
- customer perception; and
- uncertainty over how Fairfax restructures the group.
The key question is not whether IDBI deserves the same multiple as the best private banks today.
It is whether the gap can close under new ownership.
That is where future execution becomes more important than the privatisation headline.
Investor note
A low price-to-book multiple is not automatically a bargain
Banks earn higher valuation multiples when they consistently deliver strong return on equity, clean asset quality, deposit growth, technology execution and governance. Ownership change can help, but it does not guarantee a private-bank valuation.
5. Fairfax wants to build more than a bank
This is the most important strategic detail in the transaction.
Fairfax plans to turn IDBI Bank into a diversified financial-services group.
The Canadian investor already owns:
- a 30.2% stake in IIFL Capital Services, with a process underway that could raise it to 51%; and
- a 49% stake in Digit, which operates insurance businesses.
Fairfax has said it intends to transfer those stakes into IDBI Bank, subject to banking and insurance regulatory approvals.
If completed, IDBI could become the holding platform for:
- commercial banking;
- wealth management;
- investment banking;
- general insurance; and
- life insurance.
That creates obvious cross-selling opportunities.
A bank customer can become an insurance customer.
A corporate borrower can become an investment-banking client.
A wealthy depositor can be moved into wealth-management products.
That is a very different model from simply buying a bank and leaving the structure unchanged.
6. The CSB Bank question still has to be solved
Fairfax also owns about 40% of CSB Bank.
Indian banking rules do not generally allow one investor to control multiple banks indefinitely.
Fairfax has said the Reserve Bank of India has given it about two years to decide whether to merge or sell its CSB Bank stake.
A merger could give IDBI stronger exposure to southern India and a more granular branch franchise.
A sale would simplify Fairfax’s ownership structure.
Neither outcome should be assumed yet.
The regulatory decision matters because it could change the size, geography and deposit mix of the eventual IDBI platform.
Investors should treat the CSB question as an option, not as a confirmed merger.
7. What happens to LIC after the sale?
LIC is not exiting IDBI completely.
It is selling 30.24% but is expected to retain roughly 19% after the transaction.
The government is expected to retain about 15%.
Together, the two sellers would continue to own roughly 34% of the bank, although they would give up management control and withdraw from the board.
That structure matters.
It means the government and LIC are crystallising part of their investment while retaining exposure to any future improvement under Fairfax.
Reuters Breakingviews estimated that LIC’s investment generated an annualised price return of about 7.44% from the 2019 rescue to the transaction.
That return is not spectacular compared with the broader market.
But the comparison is incomplete because LIC’s intervention was not a normal portfolio investment. It was part of a rescue and recapitalisation exercise involving a systemically important lender.
For LIC shareholders, the key issue is what value the retained IDBI stake ultimately creates after management control changes.
8. Why foreign investors suddenly want Indian banks
The IDBI transaction is part of a wider trend.
Foreign financial institutions have become much more willing to buy meaningful stakes in Indian lenders.
Recent deals have involved:
- Sumitomo Mitsui Banking Corporation and Yes Bank;
- Emirates NBD and RBL Bank;
- MUFG and Shriram Finance; and
- other global institutions entering Indian financial services.
The attraction is straightforward.
India offers:
- strong credit demand;
- relatively clean bank balance sheets;
- improving asset quality;
- a large underpenetrated financial-services market;
- rising household formalisation; and
- long-term growth in mortgages, MSME credit and consumer finance.
For a foreign investor, buying an existing bank also solves the slowest part of expansion.
The acquirer gets branches, licences, deposits, customers, systems and employees immediately.
That is why the IDBI transaction matters beyond one bank.
It signals that Indian regulators and policymakers are increasingly open to foreign strategic capital in banking.
9. What the deal means for IDBI Bank shareholders
The first mistake would be to assume the ₹81 transaction price is automatically a floor or ceiling for the listed stock.
The public market is valuing a different proposition.
Shareholders are not only pricing the stake sale.
They are pricing:
- future growth under Fairfax;
- possible integration with IIFL Capital and Digit;
- deposit growth;
- return on equity;
- branch productivity;
- technology investment;
- customer retention;
- capital allocation; and
- regulatory conditions.
That is why IDBI shares can trade above or below the deal price.
The change in control is strategically important, but the stock will ultimately respond to earnings and return ratios.
The Fundamental Analysis guide is the better framework here than simply comparing the market price with ₹81.
10. The biggest risk is assuming privatisation automatically creates a private-bank multiple
Analysts have discussed the possibility that IDBI could gradually re-rate toward private-sector bank valuations.
That is plausible.
It is not automatic.
Private banks earn premium valuations because they tend to deliver:
- stronger return on assets;
- stronger return on equity;
- consistent deposit franchises;
- faster loan growth;
- better digital execution; and
- lower operating friction.
Fairfax has to prove that IDBI can do the same.
There are also integration risks.
Putting banking, insurance, wealth management and investment banking under one group can create cross-selling opportunities, but it can also create organisational complexity.
Employee resistance adds another execution variable.
The Risk Management guide is useful here because takeover stories often price in the best-case integration scenario before the difficult work begins.
11. What the deal means for India’s privatisation programme
IDBI is unusual.
It is regulated as a private bank but remains overwhelmingly owned by the government and LIC before the sale.
That makes it an imperfect test case for broader public-sector bank privatisation.
Still, the transaction is politically and economically important.
India announced an ambitious privatisation programme years ago, but progress has been slower than initially expected.
A successful IDBI sale would show that the government can:
- transfer control of a large financial institution;
- attract foreign strategic capital;
- retain a minority financial interest;
- exit board control; and
- use market-based ownership rather than permanent state management.
A failed or prolonged deal would send the opposite signal.
That is why the employee strike and political challenge matter beyond IDBI.
They test how difficult future financial-sector privatisations could become.
12. What investors should watch next
The first checkpoint is regulatory approval.
The deal still needs to complete the required banking and transaction approvals before Fairfax takes effective control.
Second, watch whether the employee dispute disrupts operations or remains largely symbolic.
Third, watch the final shareholder structure and governance arrangements for the government and LIC’s residual stakes.
Fourth, watch Fairfax’s plan for IIFL Capital and Digit.
If those assets are transferred into IDBI, the bank’s valuation framework will become more complex.
Fifth, watch the CSB Bank decision.
Sixth, watch the bank’s operating metrics after the ownership change:
- deposit growth;
- loan growth;
- net interest margin;
- cost-to-income ratio;
- return on assets;
- return on equity; and
- asset quality.
Finally, watch whether the transaction encourages more foreign acquisitions in Indian banking.
If it does, the real significance of the IDBI deal may be that it marks the beginning of a wider ownership shift in the sector.
Frequently asked questions
How much is Fairfax paying for IDBI Bank?
Fairfax is set to pay ₹52,878 crore for a 60.72% controlling stake.
What is Fairfax paying per IDBI Bank share?
The transaction price is ₹81 per share.
What was the government benchmark valuation?
The government’s benchmark price was ₹75.99 per share.
Why are IDBI employees protesting?
Employee unions argue that the valuation does not properly reflect IDBI’s private-sector regulatory status, turnaround and future potential. They want the privatisation plan withdrawn.
What does the government say?
The government rejects allegations that IDBI was deliberately undervalued and says the valuation methodology was reviewed through the prescribed disinvestment process.
How much of IDBI Bank are the government and LIC selling?
The government is selling 30.48% and LIC 30.24%, for a combined 60.72%.
Will LIC completely exit IDBI Bank?
No. LIC is expected to retain roughly 19%, while the government retains about 15%.
What does Fairfax plan to do with IDBI Bank?
Fairfax plans to make IDBI a broader financial-services platform and bring its stakes in IIFL Capital Services and Digit under the bank, subject to regulatory approvals.
What happens to CSB Bank?
Fairfax owns about 40% of CSB Bank and has said it has roughly two years to decide whether to merge or sell that stake.
Is the ₹81 deal price the fair value of IDBI shares?
Not necessarily. The listed market can value IDBI above or below the transaction price based on future earnings, growth, returns and the success of Fairfax’s strategy.
Verify through official sources
Official references
- Reuters — IDBI Bank deal faces employee and political opposition — Current reporting on the strike, valuation dispute, political criticism and government response.
- Reuters — Fairfax buys majority stake in IDBI Bank — Deal value, ₹81 per-share price, benchmark valuation, residual ownership and IDBI asset-quality context.
- Reuters — Fairfax plans to fold Indian financial holdings into IDBI Bank — Fairfax strategy for IIFL Capital, Digit and the future IDBI financial-services group.
- Reuters — IDBI shares after Fairfax announcement — Market-price reaction, valuation discussion and CSB Bank consolidation context.
- Reuters Breakingviews — India bank privatisation — Valuation multiple context, LIC return estimate and privatisation implications.
- IDBI Bank / DIPAM — Preliminary Information Memorandum — Official transaction background and original 30.48% government plus 30.24% LIC stake-sale structure.
Educational disclaimer: RegalTicker provides educational and informational content only. This article is not investment advice or a recommendation to buy, sell or hold IDBI Bank, LIC, Fairfax Financial, IIFL Capital, Digit, CSB Bank or any other security. The transaction remains subject to regulatory approvals, final agreements and implementation. Political claims, employee allegations and valuation arguments are disputed and may change as the process develops. Verify current exchange, regulator, company and government disclosures before making financial decisions.
Final takeaway
The real test begins after the ownership transfer
The IDBI Bank–Fairfax deal is important because it brings together three separate questions.
Was the bank valued fairly?
Can a foreign strategic owner unlock more value than the government and LIC did?
And can India complete a large financial-sector privatisation despite employee and political resistance?
The transaction price gives investors one reference point.
It does not answer the bigger question.
IDBI’s next valuation will depend on whether Fairfax can convert a repaired balance sheet into a stronger private-sector franchise with better growth, returns, technology and cross-selling.
If that happens, the ₹52,878 crore deal may eventually look like the beginning of IDBI’s re-rating.
If execution disappoints, ownership change alone will not be enough.