

The AI bottleneck is no longer only the GPU
The artificial-intelligence infrastructure boom has spent most of the past two years focused on accelerators from Nvidia, AMD and the large cloud platforms buying them. SK hynix’s latest results show why that picture is incomplete.
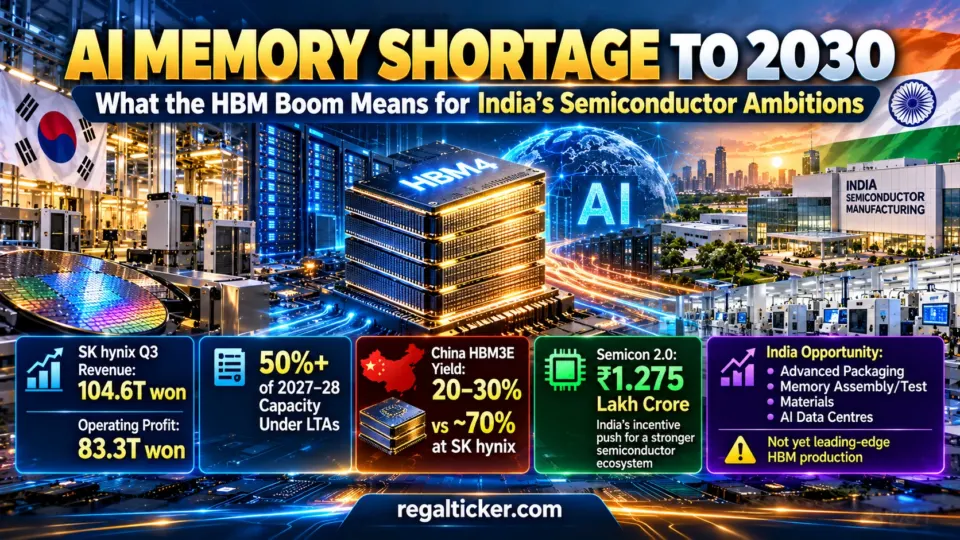
The South Korean memory leader reported record third-quarter revenue of 104.6 trillion won and operating profit of 83.3 trillion won. More important for the next stage of the AI cycle, the company says demand for advanced memory is still growing faster than supply and expects that imbalance to persist through 2030. HBM4 shipments have begun in earnest, SK hynix expects HBM4 to become its mainstream HBM product in the fourth quarter, and long-term customer agreements already cover more than half of total production capacity for 2027 and 2028.
That matters to India even though India is not yet a leading-edge HBM manufacturing base. The realistic opportunity sits one layer lower and one layer wider: advanced packaging, assembly and testing, semiconductor equipment and materials, power infrastructure, data centres and the broader electronics supply chain. That fits the argument in RegalTicker’s India semiconductor boom analysis: the strongest domestic opportunity may come from building the ecosystem around the chip, not from pretending India already has the same capabilities as South Korea, Taiwan or the United States.
⚡ Quick answer
What does the HBM shortage mean for Indian investors?
SK hynix expects memory demand to exceed supply through 2030 as AI servers consume more high-bandwidth memory and advanced DRAM. India does not currently have leading-edge HBM production, so there is no clean “Indian HBM stock” created by this news. The more credible read-through is to India’s advanced-packaging and assembly/test build-out, semiconductor equipment and materials, data-centre power and cooling, electronics manufacturing and the wider Semicon 2.0 ecosystem. The opportunity is structural, but actual beneficiaries still need contracts, customer qualification, utilisation and acceptable returns on capital.
Key takeaways
SK hynix reported Q3 2026 revenue of 104.6 trillion won and operating profit of 83.3 trillion won.
The company expects memory demand to exceed supply through 2030 because leading-edge capacity takes years to build and advanced-process yields are difficult to scale.
SK hynix says HBM4 should overtake HBM3E in both shipment volume and revenue during Q4 2026.
Long-term agreements with 14 major customers cover more than 50% of SK hynix’s total 2027–2028 production capacity.
Reuters reports China’s CXMT is preparing limited HBM3E production despite yields of only about 20%–30%, versus roughly 70% at SK hynix.
HBM is vertically stacked DRAM designed to move data far faster than conventional memory, making it critical for AI accelerators.
India is not yet producing leading-edge HBM, but Micron’s Sanand facility already assembles and tests advanced DRAM and NAND products for global customers.
Semicon 2.0 has a ₹1,27,500 crore outlay and explicitly prioritises advanced packaging, equipment, materials, fabs, design, R&D and talent.
The HBM boom can support Indian opportunities in packaging/test, precision manufacturing, specialty materials, power, cooling, networking and data centres.
Strong AI demand does not guarantee attractive returns for every semiconductor-linked stock; capex intensity, yields and valuation still matter.
1. What SK hynix’s record quarter is really telling investors
The headline earnings are extraordinary.
SK hynix reported third-quarter revenue of 104.6155 trillion won, up 32% from the previous quarter and 328% from a year earlier. Operating profit reached 83.3338 trillion won, implying an 80% operating margin in the preliminary quarter.
Those numbers are important, but the supply commentary matters more for investors thinking beyond one earnings release.
SK hynix says demand is being broadened by enterprise AI, national AI programmes and physical-AI applications such as autonomous systems and robotics. On the supply side, leading-edge processes are technically difficult and new fabs take years to plan, construct, equip and qualify.
That mismatch is why the company expects the current structure of demand exceeding supply to persist through 2030.
The implication is simple: AI infrastructure is no longer only a question of whether enough accelerators can be manufactured. It is also a question of whether enough advanced memory can sit beside those processors without becoming the new bottleneck.
2. What HBM actually does inside an AI system
HBM stands for High Bandwidth Memory.
Traditional DRAM usually sits beside the processor on a circuit board. HBM instead stacks multiple DRAM dies vertically and connects them through thousands of through-silicon vias. That architecture allows far more data to move between memory and the processor every second.
Micron describes its HBM4 12-high stack as providing more than 2.8 TB/s of bandwidth, more than twice the bandwidth of its previous HBM3E generation.
Large AI models constantly move enormous volumes of weights, activations and intermediate data between memory and compute engines. A powerful accelerator can spend valuable time waiting if memory cannot feed data fast enough.
So the AI system has two broad constraints: how much computation the accelerator can perform, and how quickly memory can supply and receive data.
HBM addresses the second constraint. That is why a shortage in HBM can limit the effective supply of AI systems even when GPU or ASIC production itself expands.
3. HBM4 is moving from “next generation” to mainstream
SK hynix says HBM4 shipments began in earnest during the third quarter and expects HBM4 to surpass HBM3E in both volume and revenue during Q4.
That transition matters because each new generation raises manufacturing complexity.
HBM requires thin stacked dies, sophisticated interconnects, tight thermal control and advanced packaging. A defect in one layer or in the stacking process can reduce usable output for the entire package.
This is why a nominal wafer-capacity increase does not automatically translate into the same increase in sellable HBM.
TrendForce has separately warned that HBM remains undersupplied as AI-server demand expands, while the industry is also competing for advanced DRAM capacity. It has raised its 2027 HBM pricing outlook because supply constraints, HBM4 mix and difficult yield ramps are keeping the market tight.
For investors, this changes the bottleneck question from “who has fabs?” to “who can repeatedly manufacture advanced products at high yield and acceptable cost?”
Investor note
Capacity is not the same as usable output
Semiconductor headlines often focus on announced fab capacity. For HBM, yield, stacking complexity, customer qualification and advanced packaging can matter just as much as theoretical wafer output. The value sits in reliable sellable production, not only installed equipment.
4. The long-term agreements make the shortage more credible
SK hynix has signed long-term agreements with 14 major customers, including global cloud-service providers.
The secured volume corresponds to more than 50% of total production capacity for 2027 and 2028.
That gives the company unusually strong demand visibility before the capacity is fully available. It also explains why SK hynix is preparing to increase investment significantly. When customers commit years in advance, a memory manufacturer can justify more capital spending with greater confidence.
But investors should still avoid treating long-term agreements as risk-free revenue. AI demand can shift, product generations can change, contract pricing can be adjusted and the economics of customer deployments still depend on whether AI workloads generate adequate returns.
This is where RegalTicker’s hyperscaler AI-capex analysis remains relevant. The HBM shortage shows physical demand is strong; the capex article asks whether the customers funding that demand can keep earning enough to sustain the spending cycle.
5. China is willing to accept poor HBM yields because the strategic need is so large
The second major signal came from China.
Reuters reports that ChangXin Memory Technologies, or CXMT, is preparing to begin limited HBM3E production despite current yields of only around 20%–30%. By comparison, Reuters cited roughly 70% yields at SK hynix.
That gap is economically brutal.
If only 20 or 30 out of every 100 potential units are usable, the cost of the good units becomes much higher. Low yields also consume scarce wafers, equipment time and materials without producing equivalent sellable output.
Yet China is pushing ahead because access to advanced AI memory has become strategically important. U.S. export restrictions constrain access to leading-edge foreign technology, while domestic AI-chip developers still need high-bandwidth memory to compete at scale.
The lesson for India is not that India should copy low-yield production at any cost. The lesson is that semiconductor capability has become a strategic asset. Nations are now willing to absorb significant inefficiency to reduce dependence on external suppliers.
6. Why this is another confirmation of the global AI infrastructure cycle
The HBM boom reinforces the demand side of the AI trade that RegalTicker has been tracking from several directions.
The Anthropic IPO analysis showed that enterprise AI demand is real but compute-intensive. The hyperscaler capex article showed how cloud companies are financing enormous infrastructure commitments while investors ask harder questions about returns.
HBM adds the hardware constraint.
The transmission chain now looks like this:
AI model demand → accelerators and ASICs → HBM and advanced DRAM → advanced packaging → servers and networking → power and cooling → data centres → enterprise AI services.
Weakness in any one layer can slow the whole system.
That does not mean the cycle runs forever. Memory has historically been cyclical because suppliers eventually add capacity and customers eventually digest inventory. What is unusual today is the combination of AI demand, technological complexity and long construction lead times.
The shortage can therefore remain real for several years without becoming permanent.
7. India is not an HBM producer yet—and that distinction matters
This is the point where thematic investing can become misleading.
India has a rapidly expanding semiconductor programme, but there is no evidence that India currently has high-volume leading-edge HBM production comparable with SK hynix, Samsung or Micron.
That should be stated plainly.
India’s near-term strengths are elsewhere: chip design, assembly/test and packaging, electronics manufacturing, emerging fabs, equipment and materials localisation, engineering talent, and a large domestic electronics and data-centre market.
The HBM shortage makes those capabilities more valuable because global chip companies want diversified supply chains. It does not instantly turn India into an HBM manufacturing hub.
That is why the existing India semiconductor boom article is useful background. The core thesis is ecosystem-building, not a race to copy the most advanced product immediately.
8. Micron’s Sanand facility is the clearest memory-chain bridge today
Micron opened its semiconductor assembly and test facility in Sanand, Gujarat, in February 2026.
The facility takes advanced DRAM and NAND wafers manufactured elsewhere in Micron’s global network and converts them into finished memory and storage products. The combined investment by Micron and government partners is approximately $2.75 billion.
That is meaningful memory-industry participation.
But it should not be misrepresented. Micron’s public description of the Sanand site does not establish that India is producing HBM4 there.
The value lies in capabilities that can compound: advanced packaging and testing know-how, semiconductor quality systems, skilled technicians and engineers, supplier development, equipment servicing, logistics and clean-room operations.
Those capabilities matter because advanced memory is becoming increasingly packaging-intensive.
If India becomes a trusted location for sophisticated assembly and test, it creates an industrial base from which higher-value products may become possible later.
9. Semicon 2.0 is better aligned with this opportunity than the first phase
India approved Semicon 2.0 with an outlay of ₹1,27,500 crore in July 2026.
The programme broadens the policy beyond simply attracting fabs. Its six pillars include design, machines and materials, new fabs, advanced packaging, research and talent.
That is important in an HBM world.
A competitive memory ecosystem needs more than a wafer fab. It needs advanced packaging capability, substrates and interconnects, precision manufacturing, materials and specialty chemicals, testing equipment, thermal management, reliable power, water infrastructure and highly trained process engineers.
In September, the government said roughly ₹1 lakh crore of investment commitments had already been received across the Semicon 2.0 ecosystem.
For investors, the opportunity is therefore broader than a handful of companies whose names contain “semiconductor.”
But the same old rule still applies: policy alignment is not revenue. A company becomes investable only when the theme shows up in customer wins, utilisation, margins, cash flow and returns on capital. RegalTicker’s fundamental-analysis framework is more useful here than a speculative beneficiary list.
10. The Indian stock-market transmission is indirect but potentially wide
There is no clean one-stock shortcut from an SK hynix shortage to the Indian equity market.
The more useful map is sectoral.
| Indian exposure | Why HBM/AI demand can matter | What must be verified |
|---|---|---|
| Semiconductor packaging / test | More global memory and chip output raises packaging demand | Customer qualification, product mix, utilisation |
| Electronics manufacturing | AI servers and electronics need complex assemblies and components | Actual AI/data-centre revenue |
| Precision engineering | Fabs and packaging plants need specialised equipment and parts | Order book and margins |
| Specialty materials | Chipmaking requires chemicals, gases, substrates and process materials | Semiconductor-grade capability and contracts |
| Power equipment | AI data centres and fabs are electricity-intensive | Project wins and delivery economics |
| Cooling / thermal systems | High-density AI servers produce large heat loads | Customer mix and scalable revenue |
| Networking / fibre | AI clusters move enormous data volumes | Capacity utilisation and pricing |
| Data-centre infrastructure | HBM demand is a symptom of wider AI-compute growth | Filled capacity, power availability, ROIC |
The mistake would be to call every company in those sectors an HBM beneficiary.
Instead, follow the evidence.
If management says semiconductor demand is material, check the order book. If a data-centre operator announces capacity, check utilisation and power availability. If an engineering company claims advanced-packaging exposure, verify the customer and revenue contribution.
The cash-flow statement guide is especially important because semiconductor and data-centre themes can absorb enormous capital before producing stable free cash flow.
11. What could break the HBM bull case
The HBM shortage is powerful evidence of current demand, but investors should not confuse a shortage with a permanent one-way market.
Several things can change the economics.
Capacity expansion: SK hynix, Samsung and Micron are all investing aggressively. New fabs and packaging capacity eventually add supply.
Yield improvement: China’s 20%–30% yield problem looks severe today, but even partial improvement can change effective output quickly.
Architecture changes: AI-chip designers can reduce HBM per accelerator, alter stack configurations or use system-level innovations to manage scarcity.
AI capex returns: If cloud and model companies fail to monetise infrastructure adequately, spending growth can slow.
Pricing: High memory prices help suppliers but raise the cost of AI systems. Buyers eventually adapt.
Technology transitions: HBM4, HBM4E and future products can shift competitive positions faster than conventional capacity additions.
Valuation: A company can benefit from a structural shortage and still be a poor investment if the market price already assumes years of perfect execution.
For Indian investors, these risks are amplified because most domestic exposures are second-order. The Risk Management path is therefore more relevant than trying to predict the exact top of the memory cycle.
12. What to watch next
The HBM thesis now has several measurable checkpoints.
First, watch whether SK hynix actually executes its HBM4 ramp at the pace implied by its fourth-quarter guidance.
Second, watch Samsung and Micron. A shortage remains more powerful when all three major suppliers report strong demand and constrained supply.
Third, watch CXMT’s yield progression. Moving from 20%–30% toward competitive yields would be a major strategic milestone for China and could eventually affect global supply.
Fourth, watch HBM pricing and customer specifications. TrendForce has already highlighted both pricing power and moves toward different stack configurations as buyers try to manage cost and availability.
Fifth, watch Indian project execution rather than announcements. Micron Sanand, approved fabs, advanced-packaging projects and the equipment/materials ecosystem need to move from investment commitments to stable commercial production.
Finally, watch AI demand itself. If Anthropic, hyperscalers and enterprise customers keep increasing compute usage, HBM remains one of the clearest physical bottlenecks in the AI economy.
Frequently asked questions
What is HBM?
HBM, or High Bandwidth Memory, is vertically stacked DRAM designed to move very large amounts of data between memory and processors. It is especially important for AI accelerators and high-performance computing.
Why is HBM in short supply?
AI-server demand is growing rapidly, while HBM requires leading-edge DRAM processes, difficult stacking and advanced packaging. New capacity takes years to build and yields can take time to improve.
How long does SK hynix expect the shortage to last?
SK hynix said on 28 October 2026 that the structure in which memory demand exceeds supply could persist through 2030.
What is HBM4?
HBM4 is the next major generation of high-bandwidth memory. SK hynix expects it to become its mainstream HBM product in Q4 2026, while Micron says its HBM4 can deliver more than 2.8 TB/s of bandwidth per 12-high stack.
Is India manufacturing HBM4?
There is no evidence in the sources used here that India currently has high-volume leading-edge HBM4 production. India’s present opportunity is stronger in assembly/test, advanced packaging, electronics, equipment, materials and related infrastructure.
What does Micron’s Sanand facility do?
Micron says the Sanand facility converts advanced DRAM and NAND wafers from its global manufacturing network into finished memory and storage products through semiconductor assembly and test.
Why does China’s CXMT matter?
Reuters reports CXMT plans limited HBM3E production despite yields around 20%–30%. That shows how strategically important AI memory has become even when economics are currently weak.
Which Indian sectors could benefit from the HBM boom?
Potential second-order beneficiaries include semiconductor packaging/test, electronics manufacturing, precision engineering, materials, power equipment, cooling, networking and data-centre infrastructure. Actual beneficiaries must be verified through contracts, revenue and project execution.
Verify through official sources
Official references
- SK hynix — Q3 2026 financial results — Primary source for Q3 revenue, operating profit, HBM4 ramp, 2030 supply outlook and long-term customer agreements.
- Reuters — SK hynix record profit and memory shortage — Current reporting on AI-memory demand, supply tightness and customer commitments.
- Reuters — CXMT HBM3E production despite low yields — Current reporting on China’s HBM3E yield gap, samples and planned limited production.
- TrendForce — HBM supply constraints and 2027 pricing — Independent industry view on HBM supply constraints, HBM4 mix and pricing pressure.
- Micron — HBM4 product overview — Primary technical source for HBM4 architecture, bandwidth and AI/HPC use.
- Micron — Sanand semiconductor assembly and test facility — Primary source on Micron’s $2.75 billion India facility and its DRAM/NAND assembly-test role.
- PIB — Micron Sanand inauguration — Government confirmation of the Sanand ATMP facility and India semiconductor context.
- PIB — Semicon 2.0 approved — Primary government source for the ₹1,27,500 crore Semicon 2.0 programme.
- PIB — Semicon 2.0 advanced-packaging implementation — Government source on advanced packaging, equipment, fabs, R&D, talent and investment commitments under Semicon 2.0.
Educational disclaimer: RegalTicker provides educational and informational content only. This article is not investment advice, a recommendation to buy or sell SK hynix, Micron, any Indian semiconductor-linked security or any AI-related stock. Industry forecasts, supply estimates, yields and technology roadmaps can change quickly. India’s semiconductor projects remain at different stages of development, and thematic exposure does not guarantee revenue, profit or shareholder returns. Verify current company, government and exchange disclosures before making financial decisions and consider your own objectives, valuation discipline and risk tolerance.
Final takeaway
India does not need to manufacture HBM tomorrow for the shortage to matter
SK hynix’s results make one point unusually clear: memory has become a strategic constraint on the AI build-out. The company sees demand exceeding supply through 2030, HBM4 is moving into the mainstream, and customers are reserving capacity years ahead.
India is not yet competing directly with the leading HBM producers. That is not a reason to dismiss the opportunity. The more credible route is to build capabilities around advanced packaging, memory assembly and test, equipment, materials, electronics, power and data-centre infrastructure while domestic fabs mature.
The investment question is therefore not “Which Indian stock is the HBM winner?” There is no evidence-based answer to that today. The better question is which Indian businesses can turn the global shortage into qualified customers, repeat orders, high utilisation, disciplined capex and sustainable returns.
That is how a global technology bottleneck becomes an Indian investment thesis—slowly, through actual industrial capability rather than a label.


