IPO access is possible, but the funding route matters
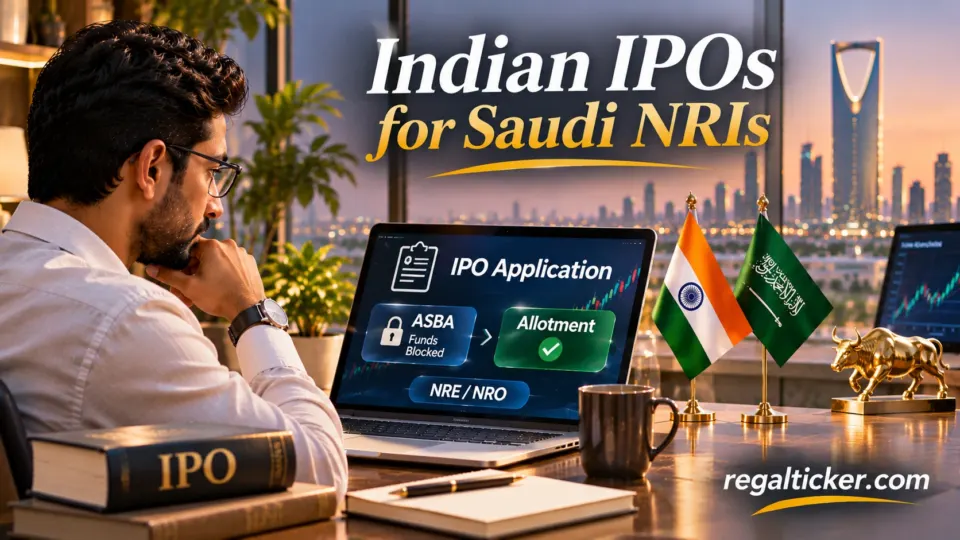
A Saudi-based NRI can subscribe to Indian public issues, but the application should match the investor’s non-resident status and intended repatriation route. The practical setup includes a valid NRI bank account, Demat account, PAN/KYC, an eligible ASBA channel and a clear choice between repatriation and non-repatriation treatment.
⚡ Quick answer
Can an NRI living in Saudi Arabia apply for an Indian IPO?
Yes. NSE confirms that eligible NRIs can subscribe to Indian public issues without obtaining individual RBI permission for each application. IPO payments use ASBA, where the bid amount remains blocked in the investor’s bank account until allotment. The Saudi NRI should use the bank route that matches the intended repatriation treatment.
Key takeaways
Saudi NRIs can apply for eligible Indian IPOs.
Individual RBI permission is not normally required for each eligible public issue.
ASBA is mandatory for public-issue payments.
The application money remains blocked until allotment.
A Demat account is needed to receive allotted shares.
NRE/eligible repatriable funding suits repatriation-basis investing.
NRO suits non-repatriation investing.
After allotment, the shares are taxed like other listed Indian equity when sold.
Saudi Arabia generally does not tax personal investment capital gains at the individual level, but India can still tax gains on Indian shares.
SAR/INR movement can change the real return after sale and repatriation.
Investor note
Decide repatriation before you bid
The IPO application is only the entry point. If you want sale proceeds to return cleanly to Saudi Arabia later, choose the funding route before applying.
1. Saudi NRIs can subscribe to Indian public issues
NSE’s NRI FAQ confirms that NRIs can purchase securities through public issues and that individual NRIs do not need to obtain separate permission when the issuer is using the applicable general/specific permission framework.
Always read the current RHP/prospectus because investor eligibility can differ by issue.
2. What accounts do you need?
A typical Saudi NRI IPO setup includes:
- PAN;
- NRI-compliant KYC;
- NRE/NRO or other eligible bank route;
- Demat account;
- trading/broker relationship;
- ASBA access through an eligible bank/channel.
For the Saudi stock-account setup: https://regalticker.com/how-to-invest-indian-stocks-saudi-arabia
3. ASBA is the core payment mechanism
ASBA means Application Supported by Blocked Amount.
Under ASBA:
- the application amount stays in your own bank account;
- funds are blocked rather than immediately transferred;
- only the amount required for allotted shares is debited;
- the remaining block is released after allotment finalisation.
NSE states that ASBA is mandatory for public issues.
4. NRE or NRO: which should fund the application?
The funding route should match the intended investment character.
Repatriation basis
Use the appropriate repatriable bank route where you want eligible future sale proceeds to retain a repatriable path.
Non-repatriation basis
Use the permitted NRO route where the investment is being made on a non-repatriation basis.
For the banking comparison: https://regalticker.com/nre-vs-nro-saudi-nri
5. UPI is not the same thing as ASBA
UPI can be one application/payment mechanism within the public-issue process, but ASBA is the core framework.
A Saudi NRI should not assume every NRE/NRO account, bank or broker supports the same UPI workflow.
Bank ASBA is often the more reliable reference point for NRI applications.
6. What happens after allotment?
If shares are allotted:
- the required amount is debited;
- the shares are credited to Demat;
- the remaining blocked amount is released.
If no shares are allotted, the blocked amount is released back to the bank account.
7. What category does an NRI fall into?
The category depends on the issue structure, application amount and offer terms.
Do not assume “NRI” itself is one fixed quota.
Read the RHP for:
- retail/individual thresholds;
- non-institutional categories;
- lot size;
- NRI eligibility;
- ASBA/UPI instructions.
8. Listing-day gains are taxable in India
IPO allotment does not create a special capital-gains exemption.
Once listed, gains on sale are taxed under the applicable Indian listed-equity rules.
For the detailed tax guide: https://regalticker.com/nri-capital-gains-tax-tds-indian-shares
9. Saudi tax treatment is separate
Saudi official guidance states that personal investment capital gains are not taxed at the individual level.
That does not remove Indian tax on gains from Indian shares.
10. Repatriating IPO sale proceeds
If the investment was made on a repatriation basis through the appropriate route, eligible sale proceeds can generally follow the corresponding repatriable path after tax and compliance.
If the investment was made on a non-repatriation basis, the proceeds follow the NRO framework.
Saudi repatriation guide: https://regalticker.com/repatriate-money-india-saudi-nri
11. SAR/INR can change the real IPO return
The return path is:
SAR → INR → IPO shares → INR sale proceeds → SAR
A strong listing gain in INR can translate into a weaker SAR result if INR weakens before conversion.
Currency guide: https://regalticker.com/sar-inr-currency-risk-saudi-nri
12. Keep the allotment and bank trail
Retain:
- application number;
- ASBA acknowledgement;
- bank block/debit record;
- allotment statement;
- Demat credit;
- sale contract note;
- tax records.
These can matter later for tax and repatriation.
13. A practical Saudi NRI IPO checklist
Before applying:
- confirm NRI eligibility in the RHP;
- confirm PAN/KYC;
- ensure Demat status is NRI-compliant;
- choose repatriation or non-repatriation treatment;
- use the matching NRE/NRO bank route;
- confirm ASBA support;
- check category and lot size;
- save the application and allotment records.
14. IPO access does not mean the IPO is attractive
Evaluate the company separately:
- business quality;
- valuation;
- promoter history;
- debt;
- cash flow;
- use of proceeds;
- dilution;
- offer-for-sale proportion;
- peer valuation;
- key risks in the RHP.
The cross-border route answers “how to apply,” not “should I buy.”
Investor note
Keep the allotment statement with your tax file
Years later, the acquisition date, cost and original bank route may matter for tax and repatriation.
Frequently asked questions
Can a Saudi NRI apply for an Indian IPO?
Yes. Eligible NRIs can subscribe to Indian public issues subject to the current offer documents and applicable rules.
Does an NRI need RBI permission for each IPO?
NSE states that individual NRIs do not normally need separate RBI permission for an eligible public issue.
Is ASBA mandatory?
Yes. NSE states that public-issue payments use ASBA.
Do I need a Demat account?
Yes. Allotted shares are credited electronically to Demat.
Should I use NRE or NRO?
Use the route that matches whether the investment is intended to remain repatriable or non-repatriable.
Is UPI mandatory for Saudi NRI IPO applications?
No. ASBA is the core framework. UPI availability depends on the bank, platform and issue workflow.
Are IPO gains tax-free?
No. Listed-share capital-gains rules apply when allotted shares are sold.
Can IPO sale proceeds be sent back to Saudi Arabia?
Yes, subject to the original route, Indian tax and FEMA/bank compliance.
Verify through official sources
Official references
- NSE India — NRI Trading Account FAQ — NRI public-issue eligibility and sale-proceeds guidance.
- NSE India — ASBA Procedure — Official explanation of ASBA and blocked-funds processing.
- NSE India — Issue Information — Current issue pages confirming mandatory ASBA usage.
- Reserve Bank of India — Foreign Investment in India Master Direction — Current framework for repatriable and non-repatriation equity investment.
- SEBI — Public Issues — Current public-issue filings and offer documents.
- MISA Saudi Arabia — Investing in KSA — Saudi guidance on personal income tax and personal-investment capital gains.
Final takeaway
Get the route right before the bid
For a Saudi NRI, an Indian IPO is not separate from the rest of the cross-border setup. The same NRE/NRO, Demat, tax, repatriation and SAR/INR considerations still apply. Set the route first, use ASBA correctly, preserve the allotment trail and evaluate the company on fundamentals rather than listing-day excitement.
Educational disclaimer: This article is for investor education only and is not personal investment, tax, legal or IPO advice. IPO eligibility, category rules, bank workflows and offer terms can vary by issue. Read the current RHP/prospectus and confirm the process with your bank, broker and authorised dealer before applying.


