⚡ Quick answer
In India, the two principal kinds of share capital are equity share capital and preference share capital. Equity shares normally represent residual ownership and voting participation, while preference shares receive specified priority over equity for dividend and repayment of capital. Each broad class can carry additional features—for example, equity with differential rights or preference shares that are cumulative, participating, convertible or redeemable.
A crucial beginner distinction is that rights shares, bonus shares, stock splits, sweat equity and ESOP allotments are not separate primary share-capital classes. They describe an issue route, adjustment, employee-benefit mechanism or special form of equity issuance. Always identify the underlying class and read the exact rights attached to the security.
Key takeaways
Indian company law broadly recognises equity share capital and preference share capital as the two main kinds of share capital.
Equity shares normally carry voting participation and the highest exposure to the company’s long-term upside and downside.
Preference shares receive priority over equity for dividend and repayment of capital, but that priority is not a guarantee against loss.
Equity can carry ordinary voting rights or differential rights as to dividend, voting or otherwise, subject to law and company terms.
Preference shares can combine features such as cumulative, non-cumulative, participating, non-participating, convertible, non-convertible and redeemable.
Irredeemable preference shares cannot be issued by a company limited by shares under Section 55 of the Companies Act, 2013.
Rights issues and bonus issues are ways of issuing additional securities; a stock split is a subdivision of existing shares.
An ESOP option is not itself an issued equity share. Shares arise after the applicable vesting, exercise and allotment process.
The name of a security is not enough. Read the articles, offer document, exchange filing and issue terms before assuming its rights.
Neither equity nor preference is automatically “better”; suitability depends on rights, valuation, liquidity, issuer quality and investor objectives.
Investor note
A share is a unit of ownership capital, but not every share carries identical rights. The class of share determines important questions such as who votes, who receives dividend priority and who ranks ahead if capital has to be repaid.
If you have just completed the previous lesson, revisit What Is Market Capitalisation? to see why a company’s market size and the rights attached to its shares are different concepts.
What Are the Main Types of Shares in India?
Section 43 of the Companies Act, 2013 broadly divides the share capital of a company limited by shares into:
- Equity share capital; and
- Preference share capital.
This is the most useful starting point for a beginner because many websites mix legal share classes with methods of issuing shares.
📖 Definition
Share Class
A share class is a category of share capital carrying a defined set of economic, voting, dividend, conversion, repayment or other rights. Two securities issued by the same company can therefore behave differently if their class terms are different.
| Share class | Core economic role | Typical voting position | Dividend position | Repayment position |
|---|---|---|---|---|
| Equity shares | Residual ownership in the business | Normally broad voting participation | Variable; only if validly declared | After creditors and preference capital |
| Preference shares | Capital carrying specified preferential rights | Usually more limited, subject to law and terms | Priority over equity according to terms | Priority over equity, after higher-ranking claims |
Equity Shares: Ownership, Voting and Growth Participation
Equity shares are the ordinary residual ownership capital of a company. Equity shareholders participate in the business after operating expenses, taxes, debt obligations and other senior claims have been met.
When the business grows, earns more and is valued more highly by the market, equity holders may benefit through capital appreciation. When the business weakens, equity holders can also absorb substantial losses because they rank behind creditors and preference capital.
📖 Definition
Equity Share
An equity share represents residual ownership in a company. Equity shareholders normally participate in voting and in the company’s long-term economic outcome, but neither dividends nor market returns are guaranteed.
Voting Rights
Ordinary equity shares generally carry voting rights on resolutions placed before members, with voting power linked to the paid-up equity capital held, subject to the Companies Act, the company’s articles and any differential-rights structure.
Voting can matter for decisions such as appointment of directors, certain capital actions, mergers, alterations to constitutional documents and other shareholder resolutions.
Dividends
Equity dividends are not fixed obligations. A profitable company can retain earnings for expansion, debt reduction, acquisitions, reserves or working capital rather than distribute cash.
This is why a high historical dividend should never be treated as a promise of future payments.
Market Price and Growth Participation
Equity share prices are continuously shaped by buyers, sellers, information and expectations. Read How Are Share Prices Decided? for the price-discovery mechanism rather than treating a quoted price as a fixed company value.
Ordinary Equity vs Equity With Differential Rights
The Companies Act allows equity share capital:
- with voting rights; or
- with differential rights as to dividend, voting or otherwise, subject to the prescribed framework.
A differential-rights class may carry more or less voting power, a different dividend structure or another economic variation. Therefore, two equity securities issued by the same company should not automatically be treated as interchangeable.
⭐ Pro tip
Check the class before comparing two securities
If a company has more than one listed equity class, compare voting ratio, dividend rights, liquidity, conversion terms, listing status and transfer conditions—not just the market price.
Sweat Equity Shares
Sweat equity is a special form of equity issuance to eligible directors or employees for know-how, intellectual-property rights or value addition, subject to Section 54 of the Companies Act and the applicable rules or SEBI regulations for listed companies.
Sweat equity is therefore not a third broad class beside equity and preference. Once issued, the shares carry the rights applicable to that equity class, subject to the governing terms.
Shares Arising From Employee Stock Options
An employee stock option gives an eligible employee a right to acquire shares under a scheme after satisfying the applicable conditions. The option itself is not the issued equity share.
Under the current SEBI Share Based Employee Benefits and Sweat Equity framework for listed companies, employee-benefit schemes can include employee stock options, employee stock purchase schemes, stock appreciation rights and other specified arrangements. Equity shares are created or transferred according to the scheme and applicable process.
Preference Shares: Priority Without Ordinary Equity Rights
Preference shares remain share capital, but they receive preference over equity in two central areas:
- payment of dividend according to the issue terms; and
- repayment of capital when the company is wound up, subject to higher-ranking legal claims.
📖 Definition
Preference Share
A preference share is share capital carrying preferential rights over equity with respect to dividend and repayment of capital. Its voting rights and return profile are usually different from ordinary equity and depend heavily on the issue terms.
Preference does not mean guaranteed safety. A preference holder can still face issuer default risk, liquidity risk, valuation risk, interest-rate sensitivity, legal risk and inadequate asset coverage.
Voting Rights of Preference Shareholders
Preference shareholders generally vote on resolutions directly affecting the rights attached to their shares. The Companies Act also provides circumstances in which wider voting rights can arise, including specified situations involving unpaid preference dividends.
The practical rule is simple: never assume that “shareholder” means identical control rights.
Dividend Priority Does Not Mean a Guaranteed Deposit
Preference shares commonly have a stated dividend rate, amount or formula. However, the payment still depends on the legal framework, the terms of the issue and the company’s ability to make the distribution.
A preference share is therefore not the same as a bank fixed deposit or a guaranteed-return product.
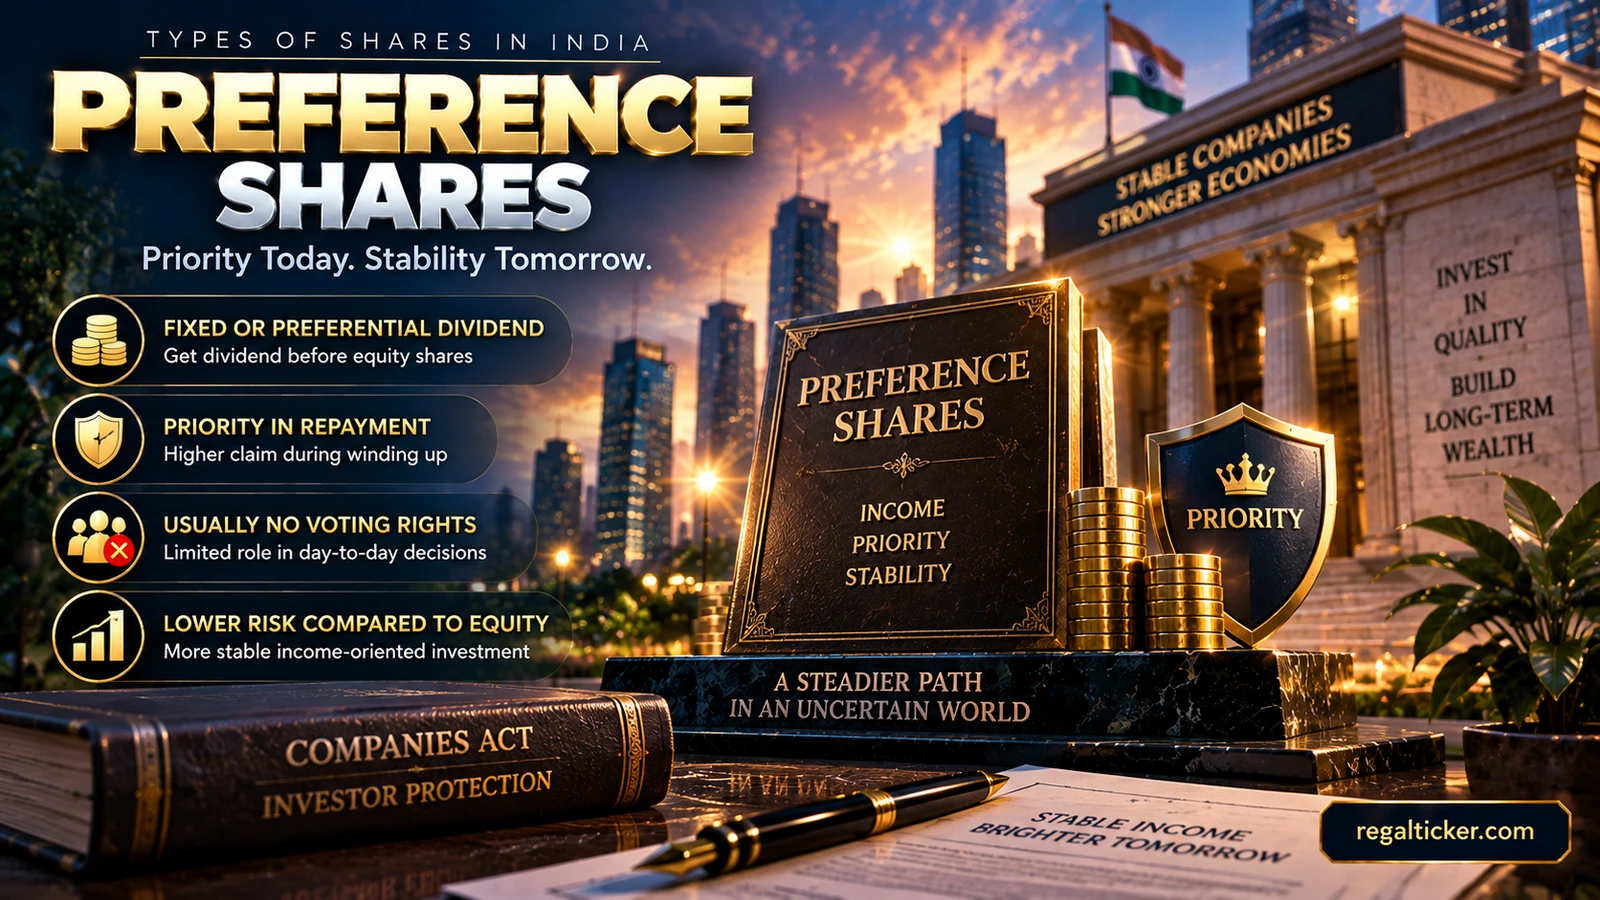
Types of Preference Shares
Preference features can be combined. One issue might be cumulative, non-participating, convertible and redeemable at the same time.
| Preference feature | What it means |
|---|---|
| Cumulative | Unpaid preference dividend accumulates according to the terms for future settlement |
| Non-cumulative | A missed dividend for a period normally does not carry forward |
| Participating | Holder may share in additional profits or surplus assets if the issue terms provide |
| Non-participating | Holder is normally limited to the stated preferential rights |
| Convertible | Can convert into equity under specified dates, ratios or conditions |
| Non-convertible | Remains preference capital and does not convert into equity |
| Redeemable | Repaid or redeemed according to the issue terms and legal framework |
Equity Shares vs Preference Shares
The easiest way to understand the difference is to compare what each class is designed to provide.
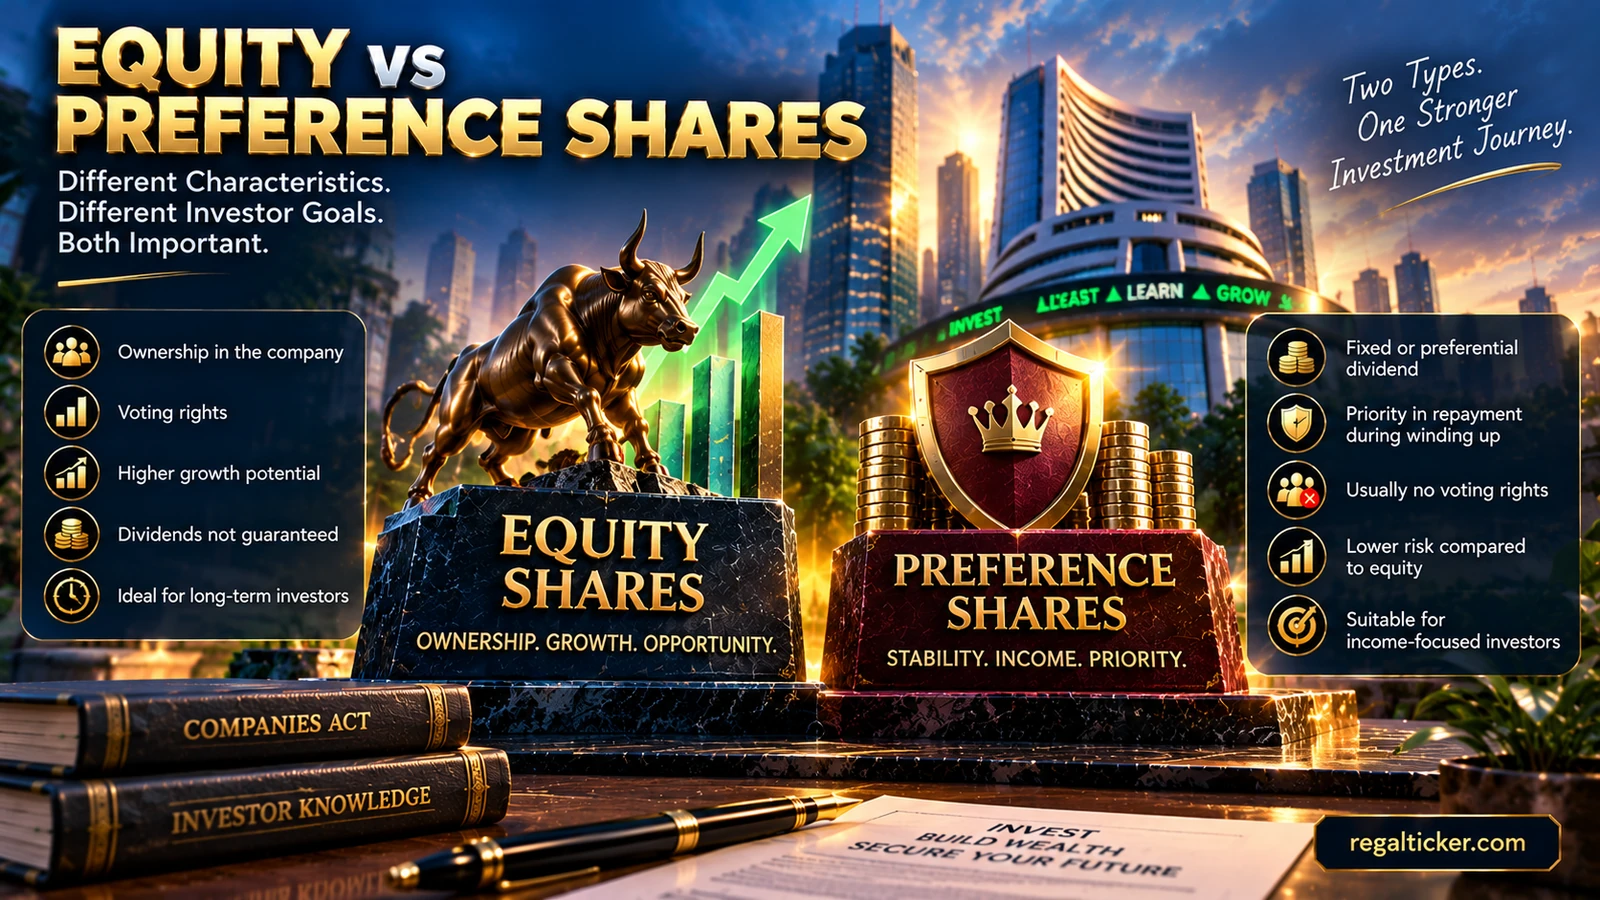
| Point | Equity shares | Preference shares |
|---|---|---|
| Basic role | Residual ownership capital | Capital with preferential rights |
| Voting | Normally broad voting participation | Usually limited; depends on law and terms |
| Dividend | Variable and not guaranteed | Priority according to stated terms |
| Growth participation | Usually greater participation in long-term business upside | Often more defined or limited |
| Price volatility | Can be substantial | Depends on issue, liquidity and market conditions |
| Repayment on winding up | After creditors and preference capital | Before equity, after higher-ranking claims |
| Conversion | Already equity | May be convertible or non-convertible |
| Redemption | No normal fixed redemption date for ordinary equity | Commonly governed by stated redemption terms |
| Investor focus | Ownership and long-term growth | Priority, income structure or specific capital terms |
Investor note
Rights come before labels
When comparing two securities, start with the actual contractual and legal rights: voting, dividend priority, conversion, redemption, participation, liquidity and repayment position. The label “equity” or “preference” is only the first layer of analysis.
Voting, Dividend and Repayment Rights: Who Gets What?
Three questions explain most of the practical difference between share classes.
1. Who Controls the Vote?
Ordinary equity usually provides the broadest shareholder voting participation. Preference voting is more restricted and often becomes relevant mainly when the rights of that class are directly affected or when statutory conditions trigger wider voting.
2. Who Gets Dividend Priority?
Preference shareholders have priority over equity according to their terms. Equity holders receive dividend only after the company validly declares it and after any preferential rights that rank ahead are addressed.
Cumulative preference shares can preserve unpaid dividend entitlement according to the issue terms; non-cumulative preference shares generally do not.
3. Who Gets Capital Back First?
During winding up, shareholders are behind creditors and other higher-ranking claims. Preference capital then ranks ahead of ordinary equity according to its preferential rights. Equity holders receive only the residual amount, if any.
Caution
Priority reduces risk; it does not remove risk
Preference shareholders can still lose part or all of their investment if the issuer fails and available assets are insufficient. Always distinguish “higher priority than equity” from “guaranteed repayment.”
Share Class vs Issue Route: Rights, Bonus, Split and Employee Allotments
This is where beginners most often get confused.
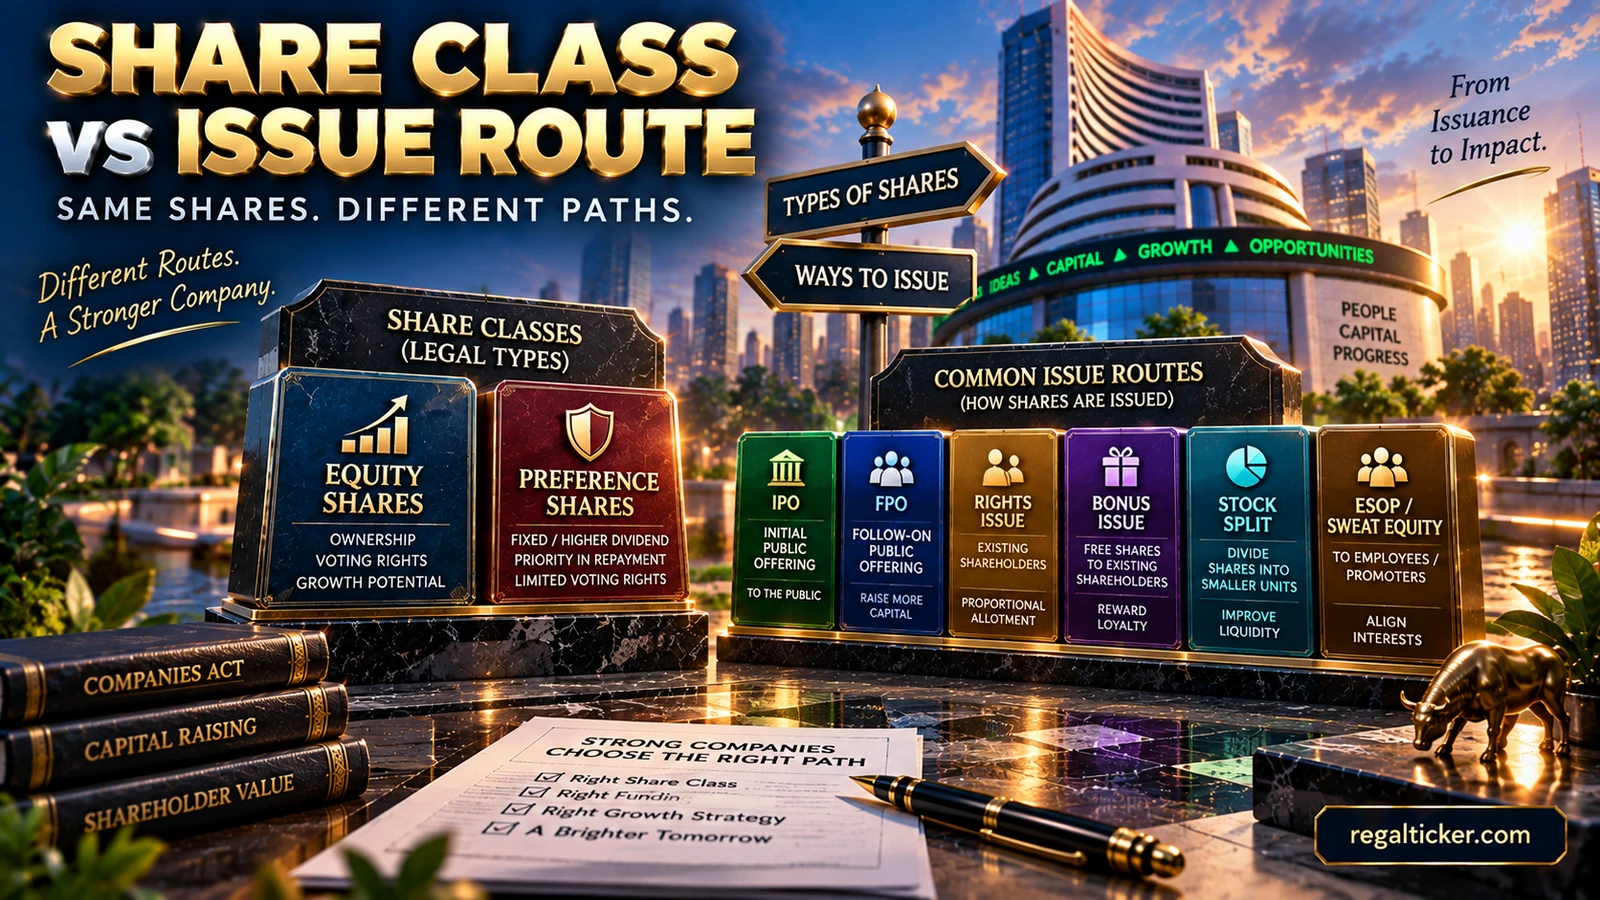
| Term | What it actually describes | Does it create a new principal share class? |
|---|---|---|
| Equity share | Legal/economic class of share capital | Yes — principal class |
| Preference share | Legal/economic class with preferential rights | Yes — principal class |
| Rights issue | Method of offering additional securities to eligible existing shareholders | No |
| Bonus issue | Issue of additional shares to eligible holders without consideration under the applicable framework | No |
| Stock split | Subdivision of existing shares into more lower-face-value units | No |
| Sweat equity | Purpose-specific equity issuance to eligible employees/directors | No — it remains equity |
| ESOP allotment | Shares issued/transferred after exercise under an employee scheme | No — resulting shares belong to an equity class |
Rights Issue
A rights issue offers additional securities to eligible existing shareholders in a stated ratio and at a stated issue price. It raises fresh capital and can affect ownership percentage if an investor does not participate.
Read What Is a Rights Issue? for Rights Entitlement, dilution and TERP. When you need the arithmetic, use the Rights Issue Calculator.
Bonus Issue
A bonus issue gives eligible shareholders additional shares in a stated ratio without an immediate cash payment. It increases the number of shares but does not automatically create new economic value merely because the quantity rises.
Read What Are Bonus Shares?, then use the Bonus Share Calculator for entitlement and theoretical adjustment calculations.
Stock Split
A stock split subdivides existing shares into a larger number of lower-face-value shares. It changes denomination rather than creating a new legal share class.
Read What Is a Stock Split? and use the Stock Split Calculator when you need to calculate the adjusted quantity or theoretical price.
Corporate Actions Belong in Their Own Learning Path
If you want to understand why companies use dividends, bonus issues, splits, rights issues, buybacks and demergers, continue in the Corporate Actions Academy. This lesson should teach share classes, while that academy owns the deeper corporate-action mechanics.
How Share Type Connects With Market Capitalisation and Price
Share class and market value answer different questions.
Share class tells you what rights the security carries.
Share price tells you the market price of one traded unit at a particular moment.
Market capitalisation measures the market value of the company’s outstanding equity using the applicable share count and market price.
This distinction prevents a common error: assuming that a ₹50 equity share is automatically “cheaper” than a ₹500 share, or that a preference share with a stated dividend rate can be compared with ordinary equity using price alone.
Before comparing companies, read What Is Market Capitalisation?. Market cap, valuation, business quality and share-class rights should be analysed separately.
⭐ Pro tip
Compare like with like
When comparing two listed securities, first confirm that they are the same type of claim. Comparing an ordinary equity share directly with a preference share, DVR security or temporarily traded Rights Entitlement without understanding the legal rights can lead to incorrect conclusions.
How to Check the Exact Rights Attached to a Share
Before investing in an unfamiliar security, verify the details rather than relying on a broker label or social-media post.
Check:
- exact security name and ISIN;
- whether the security is equity or preference capital;
- voting rights and any differential voting ratio;
- dividend rate, priority and cumulative status;
- participating or non-participating rights;
- conversion ratio and conversion date, if applicable;
- redemption date, redemption price and conditions;
- listing status and normal trading liquidity;
- lock-in or transfer restrictions;
- promoter and public holding structure where relevant;
- company articles and terms of issue;
- offer document, exchange filing and corporate announcement.
Where Should You Verify?
Use primary sources wherever possible:
- the company’s official investor-relations filings;
- NSE/BSE corporate filings and announcements;
- the applicable prospectus, letter of offer or information memorandum;
- statutory documents and the Companies Act;
- SEBI regulations for listed-company employee schemes and other regulated issues.
Investor note
The exact terms control the answer
Two securities with similar names can carry different rights. A textbook definition helps you understand the category, but the company’s actual issue terms determine the security you own.
Common Beginner Mistakes With Types of Shares
Mistake 1: Calling Bonus Shares a Separate Primary Share Class
Bonus describes how additional shares are issued to existing shareholders. The resulting shares normally belong to the relevant underlying equity class.
Mistake 2: Calling a Rights Entitlement an Ordinary Equity Share
A Rights Entitlement is a temporary entitlement connected to a rights issue. Receiving or buying an RE does not by itself mean that final equity shares have been allotted.
Mistake 3: Treating Preference Shares as Risk-Free Income Products
Preference provides priority over equity, not a sovereign guarantee. Issuer strength, liquidity, redemption terms and purchase price still matter.
Mistake 4: Assuming All Equity Shares Have Identical Voting Rights
Differential-rights equity can alter voting or economic rights. Always check the class terms.
Mistake 5: Assuming a Low Share Price Means a Cheap Company
Market price per share does not tell you total company value or valuation. Use market capitalisation and fundamental analysis rather than share price alone.
Mistake 6: Listing Irredeemable Preference Shares as a Normal Current Indian Type
Current Companies Act Section 55 prohibits a company limited by shares from issuing irredeemable preference shares. Use current law rather than outdated textbook lists.
Mistake 7: Confusing ESOP Options With Issued Shares
An option is a contractual employee benefit. The final equity share arises only after the relevant scheme conditions and allotment/transfer process are completed.
Risk
Do not buy a security until you understand its rights
A high dividend rate, unusual voting structure or discounted issue price can look attractive in isolation. Confirm the issuer’s financial strength, liquidity, valuation, conversion/redemption terms and legal rights before making an investment decision.
Conclusion
For an Indian beginner, the cleanest way to understand the types of shares is to start with two principal classes: equity shares and preference shares.
Equity normally offers residual ownership, broad voting participation and greater exposure to the company’s long-term upside and downside. Preference shares provide specified priority for dividend and repayment, but normally have more limited voting rights and a different risk-return profile.
Within these categories, rights can vary. Equity may carry differential voting or dividend rights. Preference shares may be cumulative, participating, convertible or redeemable in different combinations.
Most importantly, do not confuse a share class with an issue route. Rights issues, bonus issues, stock splits, sweat equity and ESOP allotments describe how securities are issued, adjusted or earned—not a replacement for the fundamental equity-versus-preference classification.
The next Stock Market Basics lesson is Bull Market, Bear Market and Sideways Market Explained, where the focus shifts from company ownership rights to the direction and behaviour of the broader market.
Frequently asked questions
What are the main types of shares in India?
The two principal kinds of share capital under Section 43 of the Companies Act, 2013 are equity share capital and preference share capital. Each class can carry additional features and rights.
What is the difference between equity shares and preference shares?
Equity shares normally provide residual ownership and broader voting participation, while preference shares receive specified priority over equity for dividend and repayment of capital. Their voting rights are generally more limited and depend on law and issue terms.
What are the types of equity shares?
Equity can include ordinary shares with voting rights and equity with differential rights as to dividend, voting or otherwise. Sweat equity and shares arising from employee schemes are special issuance mechanisms within the equity framework rather than a third principal class.
What are the common types of preference shares?
Preference shares may be cumulative or non-cumulative, participating or non-participating, convertible or non-convertible, and redeemable. A single preference issue can combine several of these features.
Can a company issue irredeemable preference shares in India?
No. Section 55 of the Companies Act, 2013 states that a company limited by shares cannot issue irredeemable preference shares. Investors should check the actual redemption terms of the issue.
Are bonus shares and rights shares types of shares?
They are better understood as issue routes or corporate actions. Bonus shares are additional shares issued to eligible shareholders without consideration under the applicable framework, while a rights issue offers additional securities to eligible existing shareholders, usually for fresh payment.
Are preference shares risk-free?
No. Preference shareholders have priority over equity in specified areas, but they can still face issuer, liquidity, market, legal and repayment risks.
Can preference shareholders vote?
Yes, but their voting rights are generally narrower than ordinary equity. They normally vote on matters affecting their rights, and the Companies Act provides additional circumstances in which wider voting rights may arise.
What are DVR shares?
DVR commonly refers to equity shares with differential voting rights. Their voting, dividend or other rights differ from ordinary equity according to the class terms and applicable rules.
Is an ESOP the same as an equity share?
No. An employee stock option is a right under an employee scheme. The equity share is created or transferred only after the applicable vesting, exercise and allotment or transfer process.
Educational disclaimer: This article is for education and financial awareness only. It is not investment, legal or tax advice. Share-class rights, voting terms, dividend provisions, conversion terms, redemption conditions and issue structures can vary by company and security. Always verify the latest company filing, offer document, exchange announcement and applicable regulation before making an investment decision. Investments in securities markets are subject to market risks.