Moving money back to Singapore depends on where the money sits and how it was earned
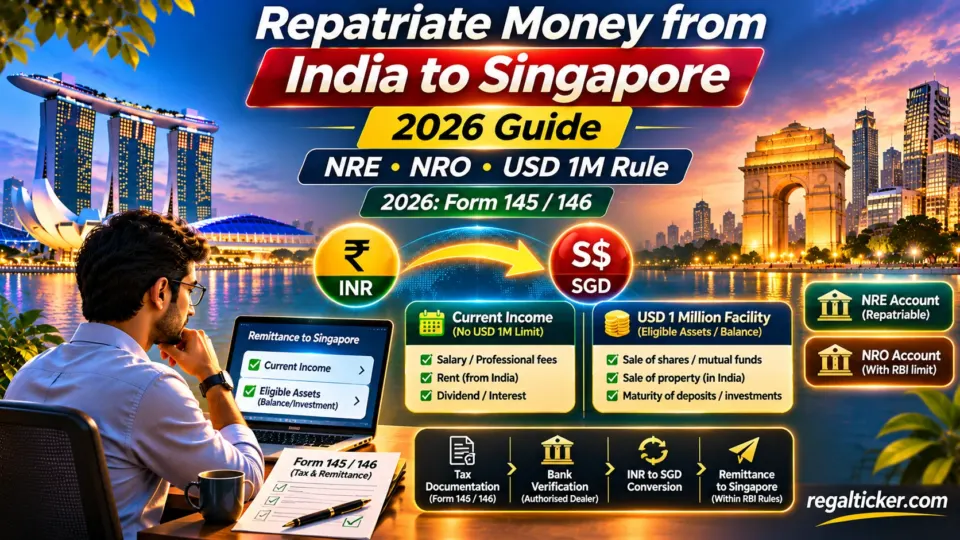
For a Singapore-based NRI, repatriation is not one single process. Money in an NRE account can generally move abroad under the applicable FEMA framework, while NRO money follows a different route. Current income such as eligible rent, pension, dividend and interest can be remitted subject to compliance, while eligible NRO capital balances and asset-sale proceeds can use the separate USD 1 million per financial year facility.
⚡ Quick answer
Can an NRI send money from India to Singapore?
Yes. NRE balances are generally repatriable. NRO current income can also be remitted abroad subject to tax and bank checks. Eligible NRO balances and specified assets can be remitted up to USD 1 million per financial year under RBI’s remittance-of-assets framework. From 1 April 2026, the Income Tax Act, 2025 uses Form 145 and Form 146 in place of the old Form 15CA/15CB framework for relevant foreign-remittance reporting.
Key takeaways
NRE and NRO money do not follow the same outward-remittance route.
NRE balances are generally repatriable.
NRO current income can be remitted abroad subject to applicable tax compliance and bank verification.
Eligible NRO capital balances and assets can use the USD 1 million per financial year facility.
The USD 1 million ceiling is an annual RBI facility, not a tax exemption.
From 1 April 2026, Forms 145 and 146 replace the old Form 15CA/15CB framework for relevant remittances.
The authorised dealer bank can ask for source-of-funds and tax documents.
India-to-Singapore remittance and India–Singapore DTAA relief are separate questions.
The final SGD amount depends on INR/SGD conversion and banking costs.
Investor note
First identify the bucket
Before asking a bank how to send money to Singapore, identify whether the amount is NRE balance, current income in NRO, or eligible capital/asset proceeds in NRO. The correct remittance route follows that classification.
1. NRE repatriation is the simplest route
NRE accounts are designed for eligible non-resident funds with repatriable character. RBI guidance treats NRE balances as repatriable, so eligible principal and permitted credits can generally be remitted abroad, subject to normal bank checks and the underlying transaction rules.
A typical flow is: Singapore savings → NRE → Indian investment/deposit → eligible proceeds → NRE → Singapore
Using NRE does not make every investment tax-free. Tax on the underlying investment must still be settled.
2. NRO current income follows a different route
NRO is commonly used for Indian rupee income and other permitted local credits. RBI allows NRO accounts to be debited for remittance of current income abroad.
Examples can include eligible rent, pension, dividend, interest, salary or professional income arising in India where the remittance is otherwise permitted.
Current income is not automatically subject to the USD 1 million capital-remittance ceiling, but tax and bank-document checks still apply.
3. What the USD 1 million facility actually covers
RBI permits NRIs and PIOs to remit up to USD 1 million per financial year from eligible NRO balances and specified assets, subject to the remittance-of-assets framework.
This can be relevant for property-sale proceeds, investment sale proceeds, maturity proceeds and other eligible NRO capital balances.
The limit runs from April to March. It is not permission to remit unexplained money. The authorised dealer bank must be satisfied about source, eligibility and tax compliance.
4. Current income and capital remittance are different buckets
Eligible current income and capital/assets use different concepts.
Rent or interest may be remitted as current income subject to conditions. Eligible capital or asset-sale proceeds may use the USD 1 million annual facility.
Do not count every NRO remittance against the same bucket without identifying the receipt first.
5. NRO to NRE transfer can use the same annual facility
RBI permits eligible transfer from NRO to NRE within the USD 1 million per financial year facility.
The bank can still require source-of-funds and tax evidence. Moving money into NRE does not erase its history.
For the Singapore-specific account comparison: https://regalticker.com/nre-vs-nro-singapore-nri
6. The 2026 tax-form change: Forms 145 and 146
For remittances on or after 1 April 2026, the Income Tax Department states that:
- Form 145 is the new information form corresponding to old Form 15CA.
- Form 146 is the new CA certificate corresponding to old Form 15CB.
The substantive purpose remains similar: reporting the remittance, determining chargeability and confirming tax/TDS treatment.
Do not use a stale checklist that says only “15CA/15CB” for a 2026 remittance.
7. When Form 146 may be needed
The current framework retains a threshold-based structure broadly similar to the old rules.
Where the remittance is taxable and exceeds the prescribed threshold, a CA certificate in Form 146 may be required unless an appropriate Assessing Officer certificate/order is available.
Income Tax Department guidance notes that the ₹5 lakh threshold structure continues under the new rules.
8. Tax must be settled before the bank treats the remittance as clean
Repatriation is not a route around Indian tax.
If the money arises from rent, property sale, shares, mutual funds, interest, dividend or professional/business income, the underlying tax position should be determined first.
The bank may ask for capital-gains computation, TDS certificates, tax-payment evidence, source documents, Form 145 acknowledgement and Form 146 where applicable.
For Indian share gains: https://regalticker.com/nri-capital-gains-tax-tds-indian-shares
9. DTAA relief is separate from RBI repatriation permission
The India–Singapore DTAA answers income-tax questions. RBI/FEMA rules answer whether and how money can be remitted.
A treaty benefit does not automatically make NRO capital freely repatriable, and RBI permission does not determine the tax rate.
Treaty guide: https://regalticker.com/india-singapore-dtaa-nri-tax
10. Documents a Singapore NRI should keep ready
A practical file can include PAN, passport, NRI-status evidence, Singapore address proof, bank statements, source-of-funds proof, property or investment statements, capital-gains computation, TDS certificate, tax-payment evidence, Form 145 acknowledgement, Form 146 where applicable and prior remittance records.
Collect these before transfer day.
11. Track the annual USD 1 million facility
If you use more than one Indian bank, keep a simple ledger showing date, source, bank, INR amount, USD equivalent and remaining annual facility.
That helps the authorised dealer verify that the ceiling has not been exceeded.
12. INR-to-SGD conversion is the hidden second cost
After regulatory and tax compliance, the transfer still has an FX layer.
Your final SGD amount depends on the INR/SGD rate, bank spread, transfer fee, correspondent-bank charge and any receiving-bank fee.
For large transfers, compare the all-in SGD received rather than only the quoted exchange rate.
13. Singapore tax after the money arrives
IRAS states that overseas income received in Singapore is generally not taxable for individuals, subject to specific exceptions.
So the act of moving eligible Indian money into a Singapore bank account does not automatically create a new Singapore tax charge for a normal individual.
Indian tax can still apply before remittance.
14. A practical India-to-Singapore sequence
For a typical NRO capital remittance:
- Identify the source.
- Classify it as current income or eligible capital/asset amount.
- Calculate and settle Indian tax.
- Check how much of the USD 1 million annual facility has already been used.
- Prepare Form 145 and, where required, Form 146.
- Submit source, tax and bank documents to the authorised dealer.
- Bank verifies FEMA and tax compliance.
- INR is converted.
- Funds are transferred to Singapore.
- Keep the remittance advice and tax file.
Investor note
Record the SGD received, not only the INR sent
For household planning, save the actual SGD amount credited after conversion spreads and bank charges. That is the number that matters for your real cross-border return.
Frequently asked questions
Can NRE money be sent to Singapore?
NRE balances are generally repatriable under RBI/FEMA rules, subject to normal transaction and bank checks.
Is all NRO money limited to USD 1 million per year?
No. Eligible current income can be remitted separately. The USD 1 million facility applies to eligible NRO balances and specified assets/capital remittances.
Can property-sale proceeds be sent to Singapore?
Eligible property-sale proceeds may use the remittance-of-assets framework, including the USD 1 million annual facility where conditions are met.
Can I transfer NRO money to NRE?
RBI permits eligible NRO-to-NRE transfers within the USD 1 million annual facility, subject to tax and documentation.
Are Forms 15CA and 15CB still used in 2026?
For remittances on or after 1 April 2026, Form 145 and Form 146 are the corresponding forms under the Income Tax Act, 2025. Older forms remain relevant to earlier remittances governed by the old Act.
Is Form 146 needed for every remittance?
No. The requirement depends on chargeability, amount and whether an Assessing Officer certificate/order exists.
Does the USD 1 million limit reset every calendar year?
No. It follows the Indian financial year, April to March.
Does Singapore tax the money when it arrives?
IRAS says overseas income received in Singapore is generally not taxable for individuals, subject to listed exceptions. Indian tax can still apply first.
Verify through official sources
Official references
- Reserve Bank of India — Accounts in India by Non-residents — RBI guidance on NRE repatriability, NRO current-income remittance and the USD 1 million annual facility.
- Reserve Bank of India — NRO Account Instructions — RBI instructions on NRO credits, current-income remittance and eligible USD 1 million repatriation.
- Income Tax Department — Income Tax Forms — Current guidance on Form 145 and Form 146 for remittances from 1 April 2026.
- IRAS — Income Received from Overseas — Singapore guidance on overseas income received by individuals.
Final takeaway
Repatriation is easiest when the money trail is clean
For a Singapore NRI, the simplest strategy is to preserve the right account route from the beginning. Keep repatriable foreign money clean in NRE where appropriate, keep Indian-source flows properly documented in NRO, separate current income from capital remittances, and maintain the 2026 Form 145/146 tax file before approaching the bank. The paperwork is much easier when the source trail was designed correctly when the money was earned or invested.
Educational disclaimer: This article is for investor education only and is not personal tax, legal, FEMA or banking advice. Repatriation eligibility depends on the source of funds, account type, asset history, tax treatment, documentation and bank verification. Confirm the current process with your authorised dealer bank, RBI, Income Tax Department and a qualified adviser before remitting funds.